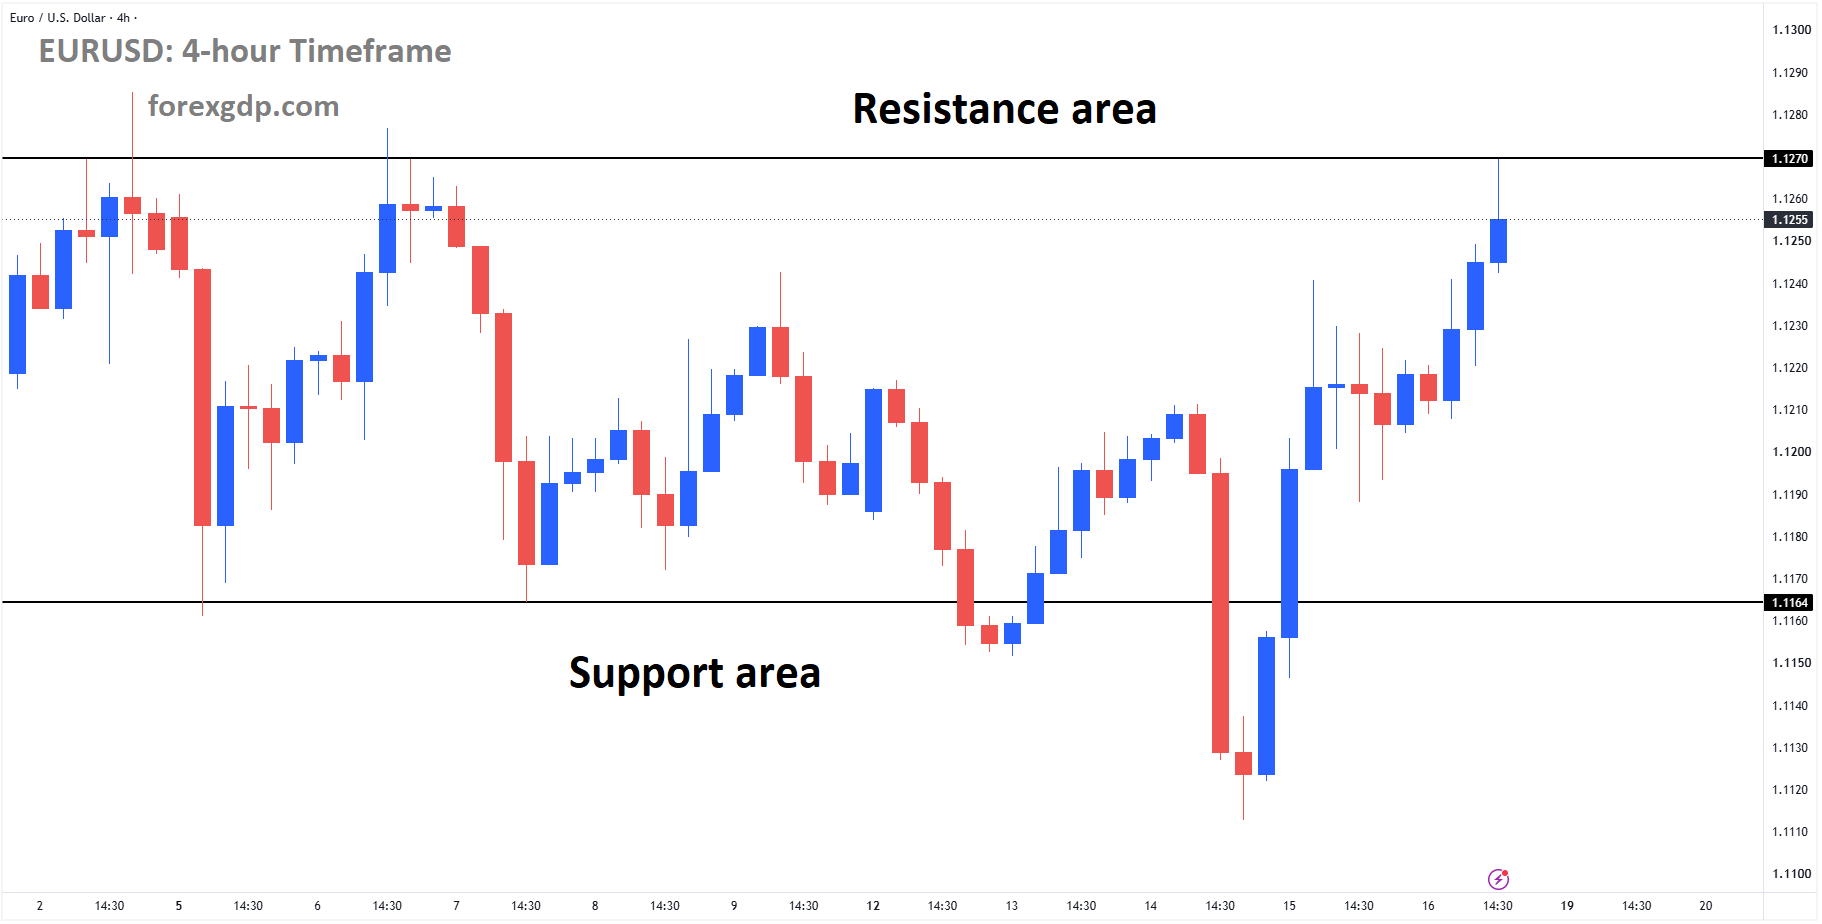
EURUSD reached the resistance area of the box pattern
EURUSD Extends Recovery as Tech Jitters Shake US Currency
The Euro is gaining ground against the US Dollar as concerns about artificial intelligence investment put pressure on American assets. What began as a strong source of confidence in the US economy is now drawing closer attention from investors who want to know whether the spending boom can maintain its pace.
For EURUSD, that shift matters. The Dollar has benefited from expectations that AI spending will help the United States grow faster and attract global capital. When those expectations become less certain, some of the currency’s support can weaken.
At the same time, the Federal Reserve remains focused on price stability. Comments from Fed Chair Kevin Warsh underline that commitment, although they provide little fresh guidance on the direction of monetary policy.
Together, these developments are shaping a currency market in which changes in confidence toward the United States are giving the Euro room to recover.
Euro Gains as Confidence in US Assets Softens
The Euro’s recovery reflects a change in how investors view the Dollar rather than a sudden improvement in the European economic outlook.
For much of the recent market story, the United States has attracted attention because of its economic resilience and the strength of its technology sector. Large investments in AI have added to that appeal, encouraging expectations of stronger business activity and future productivity gains.
Those expectations have helped draw money toward American companies and financial assets. Such demand can also support the Dollar, as overseas investors often need the currency to make those investments.
Now, questions surrounding the financing and returns of AI projects are making that outlook less comfortable. Investors are becoming more selective about where they place their money, and the Dollar is feeling the effects.
That creates an opening for the Euro. EURUSD can strengthen when demand for the US currency fades, even without a major positive development in the eurozone.
Why AI Spending Matters to the Dollar
AI investment has become an important part of the broader US growth story. Its influence reaches beyond technology shares.
Spending on data centres, computing equipment, energy capacity and related services can support activity across several industries. Businesses involved in construction, infrastructure and digital services may all benefit from the expansion.
Investors have also looked beyond the immediate spending. Many expect AI adoption to help companies work more efficiently, reduce some costs and develop new products over time.
These hopes have strengthened the appeal of US assets. When investors believe American businesses offer better growth opportunities, they may direct more capital toward the country.
However, that relationship creates a vulnerability. If confidence in AI investment weakens, the benefits that previously supported the Dollar can begin to fade.
The key issue is not whether AI has useful applications. It is whether the scale of investment, the financing behind it and the expected commercial returns remain aligned. Even a modest change in those expectations can affect markets that have placed considerable weight on the sector.
Why Market Caution Is Not Lifting the Dollar
The Dollar often attracts demand when investors become nervous. Its widespread use in global trade and finance makes it a familiar place to hold funds during periods of uncertainty.
But that response is not automatic.
Strategists at OCBC highlight that the source of market stress matters. When concerns are centred on the United States, investors may reduce their exposure to American assets instead of increasing their Dollar holdings.
The current AI debate illustrates this distinction. If investors become less confident about an important driver of US growth, they may reassess both American investments and the currency connected to them.
This helps explain why a cautious market mood can exist alongside a weaker Dollar. Investors are not simply reacting to global uncertainty. They are questioning part of the investment story that has supported the United States.
For EURUSD, this changes the usual relationship between risk sentiment and currency demand. A nervous market does not necessarily prevent the Euro from advancing when the main concern is focused on US assets.
Lower Treasury Yields Add Another Layer
The bond market provides another explanation for the Dollar’s softer performance.
During periods of uncertainty, investors may buy US government bonds for their perceived safety. Stronger demand raises bond prices and lowers their yields.
Lower Treasury yields can then reduce the income advantage of holding certain Dollar assets. That may make the currency less attractive relative to alternatives, depending on how interest-rate expectations develop elsewhere.
As a result, demand for US government bonds and weakness in the Dollar can occur at the same time.
There is no need for investors to abandon every American asset for the currency to come under pressure. They can seek safety in government debt while becoming more cautious about US equities or the broader growth outlook.
This combination helps explain the market response described by OCBC: greater caution, falling Treasury yields and a softer Dollar.
Fed Focus on Price Stability Leaves Policy Questions Open
Federal Reserve policy remains an important part of the EURUSD outlook, even as AI concerns attract attention.
Fed Chair Kevin Warsh has emphasised the central bank’s commitment to price stability while offering limited detail about the future policy path.
That leaves investors without a clear new signal on how interest rates might change. A commitment to controlling inflation establishes a priority, but it does not by itself explain the timing or direction of the next policy decision.
The distinction matters for currencies. Interest-rate expectations influence the returns investors expect from holding assets in different countries.
Without more specific guidance, markets must continue assessing inflation, economic activity and future Fed communication. For now, Warsh’s remarks reinforce the central bank’s focus without settling the wider policy debate.
Summary
EURUSD is recovering as doubts about AI investment weaken some of the confidence that has supported the US Dollar. The move shows how closely currency demand can be tied to expectations about economic growth and investment returns.
OCBC views the latest concerns as a disruption rather than a collapse in the broader AI investment story. Even so, the episode highlights a meaningful vulnerability: a growth theme that strengthens the Dollar can also weigh on it when confidence fades.
The Euro’s next moves will depend partly on whether those concerns ease or deepen. Alongside that, Treasury yields and clearer Federal Reserve guidance will remain important influences on the balance between the two currencies.
GBPUSD Extends Recovery as Traders Await Fed’s Next Move
The British Pound is gaining ground against the US Dollar as investors weigh stronger UK economic growth and fresh comments from central bank officials. The latest developments have brought renewed attention to the different challenges facing the Bank of England and the US Federal Reserve.
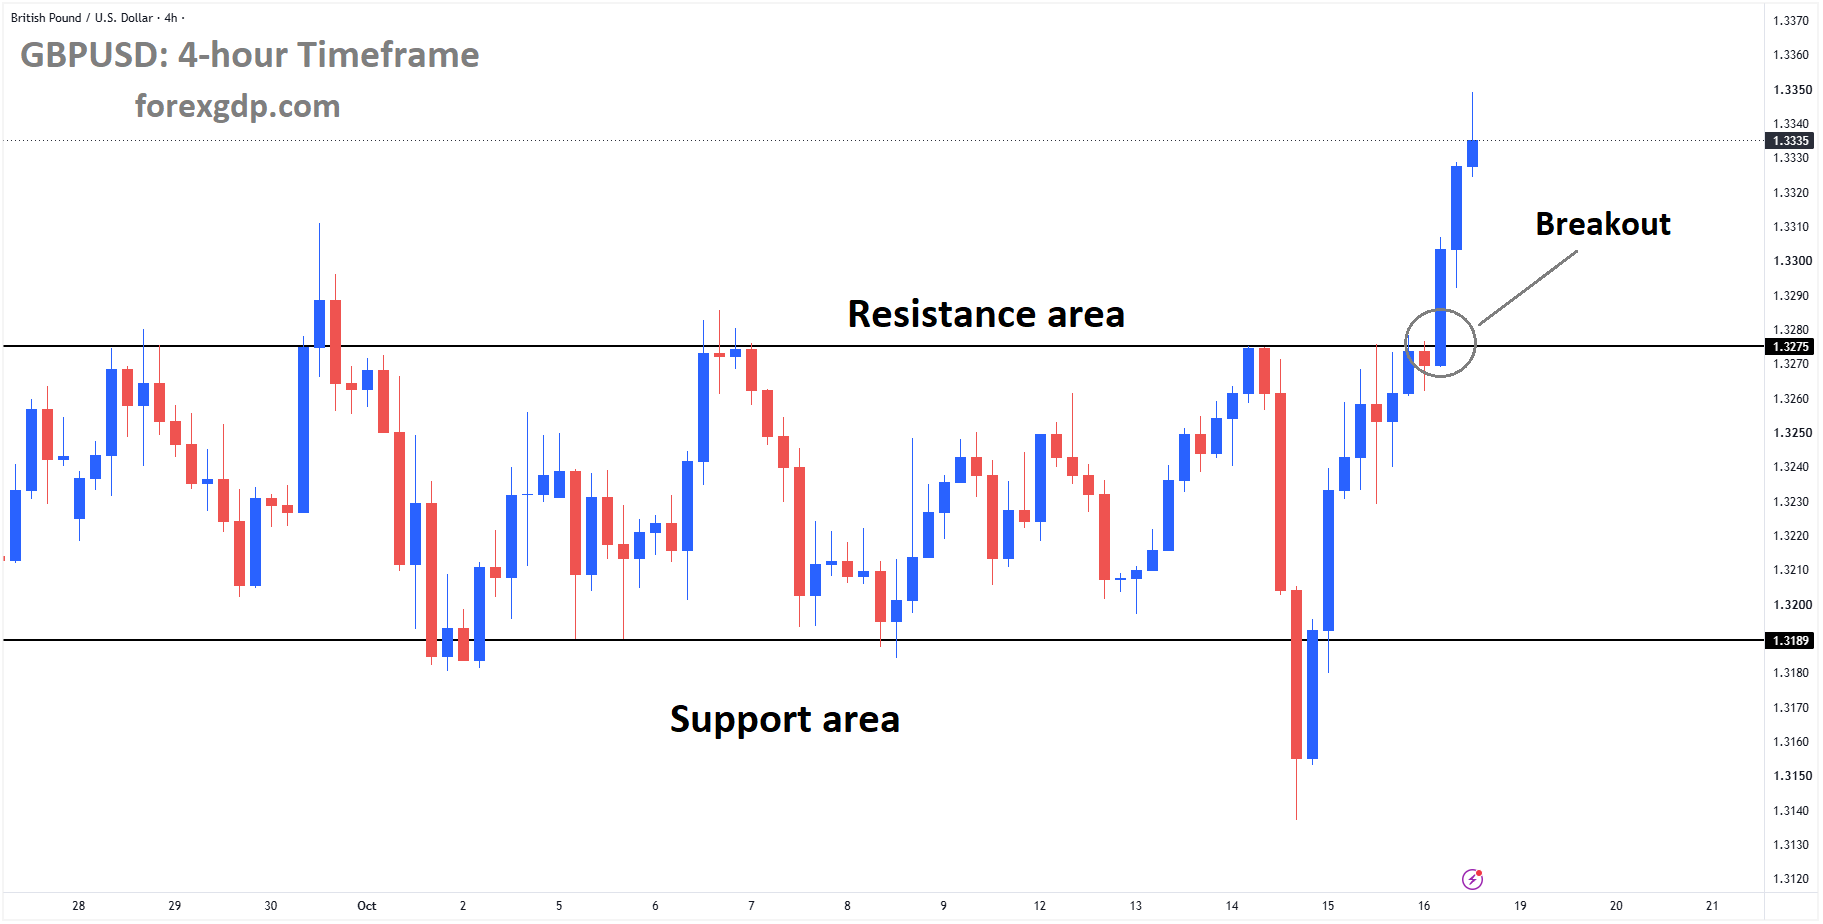
GBPUSD has broken the box pattern to the upside
For the Pound, better economic data offers some encouragement. However, uncertainty over energy costs and inflation means the outlook remains complicated. In the United States, policymakers are keeping their options open, leaving investors to assess whether another interest rate increase is necessary.
Together, these factors are shaping GBPUSD sentiment, with expectations for borrowing costs playing a central role.
Stronger UK Growth Gives the Pound a Lift
Stronger UK Gross Domestic Product data has helped support the British Pound. A healthier economy can give the Bank of England more room to keep borrowing costs elevated if inflation remains difficult to control.
Economic growth matters because interest rate decisions involve a careful balance. Higher borrowing costs can help slow inflation, but they can also reduce household spending and make businesses more cautious about investing.
When growth holds up better than expected, concerns about the damage caused by restrictive monetary policy may ease. That can encourage investors to reconsider how quickly the central bank might be able to lower rates—or whether it may need to raise them again.
Still, a stronger GDP report does not settle the wider debate. Investors also need to understand what is driving that growth and whether it can continue while households and companies face higher energy expenses.
For now, the improvement in economic activity has given Sterling a more supportive backdrop.
Bailey Highlights Limited Wider Effects From Energy Inflation
Bank of England Governor Andrew Bailey has drawn attention to the impact of rising energy costs on the broader economy.
His message was cautious. Although energy has become more expensive, evidence of a wider spread into other British prices remains limited so far. However, he also made clear that it is too early to reach a firm judgment.
This distinction matters for monetary policy. A direct increase in energy costs can lift inflation without necessarily creating a lasting rise in prices across the economy.
The greater concern is that businesses begin passing higher costs on to customers more broadly, while workers seek larger pay increases to protect their purchasing power. Those responses can make inflation harder to bring under control.
These are often called second-round effects. Their strength and duration can influence whether the Bank of England sees a need for further action.
Bailey’s comments therefore leave room for different outcomes. Limited spillovers could reduce the urgency to tighten policy, while stronger evidence of lasting inflation pressure could strengthen the case for higher rates.
Bank of England Expectations Remain Important for Sterling
The supplied Reuters poll points to expectations among many economists that the Bank of England could begin raising interest rates at its next meeting.
That outlook reflects concern about the inflation consequences of the US-Iran conflict and the associated rise in energy costs. The central bank has kept policy unchanged since the conflict began, giving officials time to assess how the economic impact develops.
Expectations of higher UK interest rates can support the Pound because they may improve the appeal of Sterling-denominated assets. However, the reason behind a potential increase matters as much as the increase itself.
If borrowing costs rise while the economy remains resilient, investors may view the decision more positively. If rates rise because inflation is worsening while growth weakens, the effect on confidence could be less favourable.
The next stage of the debate will depend on whether incoming data shows that price pressures are spreading beyond energy.
Warsh Keeps the Federal Reserve’s Options Open
On the US side, Federal Reserve Chair Kevin Warsh has avoided giving a clear advance signal about the next policy decision.
Speaking at an International Monetary Fund event, he stressed that he does not decide the outcome of interest rate meetings beforehand. His remarks left both an increase and an unchanged decision open for consideration.
That approach keeps attention on the evidence available before the October and December meetings. Rather than offering investors a fixed path, the Fed is preserving flexibility as it assesses the economic situation.
For the US Dollar, this creates uncertainty. Clear expectations of higher borrowing costs can support the currency, but cautious communication may make investors less willing to commit to that outcome.
Warsh’s comments do not establish that a rate increase is coming. They indicate that the decision remains under review.
Other Fed Officials See Less Urgency to Raise Rates
Comments from San Francisco Fed President Mary Daly and Fed Vice Chair for Supervision Michelle Bowman have added another perspective to the discussion.
Both indicated that an immediate interest rate increase might not be necessary. Their remarks suggest that at least some policymakers see value in waiting for more information before making another adjustment.
That does not remove inflation concerns. It highlights the judgment involved in deciding whether existing policy is already doing enough.
Raising rates too soon could place unnecessary pressure on economic activity. Waiting too long could allow inflation to become more persistent. Officials must weigh both possibilities.
For GBPUSD, a less urgent approach from the Fed can give the Pound some breathing room, particularly when UK data is improving. Even so, the Dollar’s response will depend on whether future US releases support patience or point toward further tightening.
Energy Costs Connect the UK and US Policy Debates
Energy remains a shared source of uncertainty for both economies.
Higher fuel and power costs can squeeze household budgets, reduce business margins and complicate efforts to control inflation. However, the effects may differ across countries depending on how costs reach consumers and how businesses respond.
This means the Bank of England and the Federal Reserve may reach different decisions even while facing the same global disruption.
Currency investors will therefore be watching the relative picture: which economy remains stronger, where inflation proves more persistent and which central bank feels greater pressure to act.
Final Summary
GBPUSD is finding support from stronger UK growth and expectations that the Bank of England may need to raise borrowing costs. Bailey’s cautious assessment of energy-related inflation, however, shows that the policy outlook is still developing.
Meanwhile, Warsh has kept the Fed’s upcoming decisions open, while Daly and Bowman have suggested that an immediate increase may be unnecessary.
The Pound’s next moves will depend on how economic growth, energy costs and inflation influence the balance between UK and US interest rate expectations.
USDJPY Retreats as Yen Draws Strength From BoJ
USDJPY moves lower as comments from the Bank of Japan give the Japanese Yen fresh support, while uncertainty over the Federal Reserve’s next decision weighs on the US Dollar. Traders are reassessing the outlook for both central banks as inflation remains a central concern in Japan and the United States.
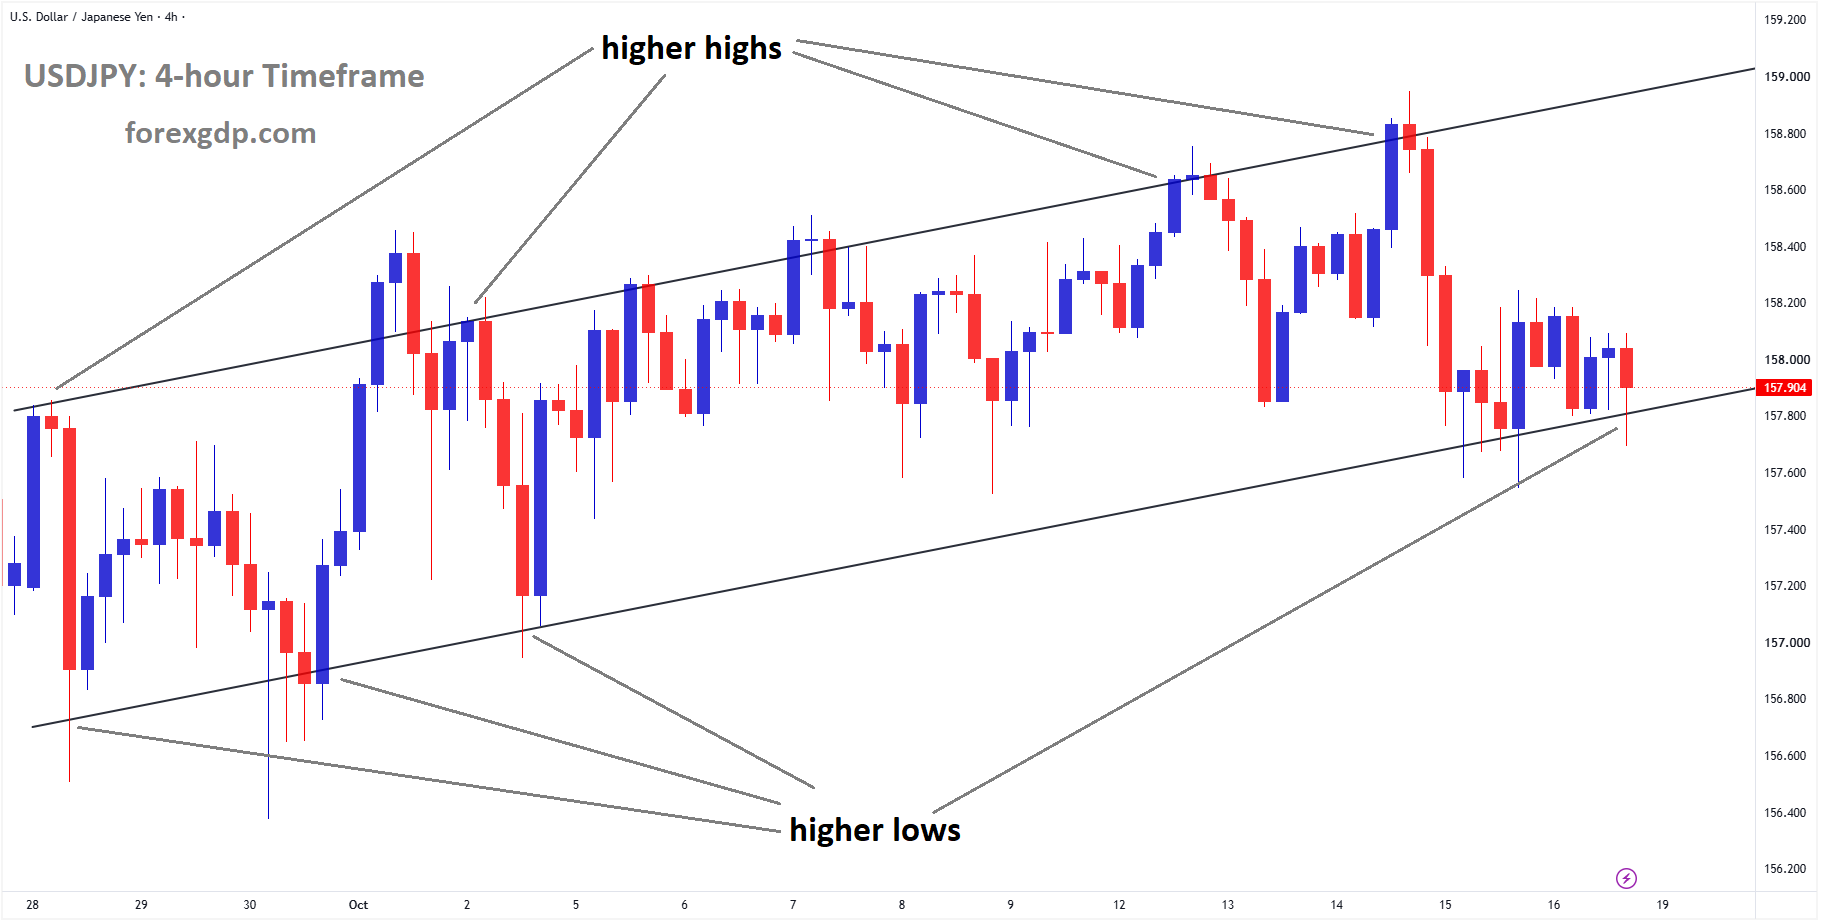
USDJPY reached a higher low area of the ascending channel
The latest remarks from BoJ board member Junko Koeda suggest that further interest rate increases remain under consideration. Her message challenges the idea that Japan’s central bank needs to move especially slowly when responding to rising prices.
Meanwhile, Fed Chair Kevin Warsh has avoided giving a clear indication of what policymakers might decide at their October meeting. That leaves investors balancing an uncertain policy outlook against stronger US producer inflation.
For USDJPY, the key question is how these two policy paths develop and whether the difference between Japanese and US borrowing costs begins to narrow.
Koeda’s Comments Give the Japanese Yen Fresh Support
Koeda’s remarks have brought renewed attention to the possibility of additional monetary tightening in Japan. She argued that the BoJ cannot afford to be overly cautious about raising interest rates when there are considerable risks that inflation could move higher.
Her comments matter because investors closely follow how willing Japanese policymakers are to continue adjusting borrowing costs. A stronger willingness to raise rates can improve the Yen’s appeal by increasing the potential return on assets held in the currency.
Koeda also said that Japan’s financial conditions remain supportive, even after previous rate increases. In her assessment, there is little evidence that higher borrowing costs have significantly weakened household spending or business activity.
That suggests she sees room for further adjustments without placing excessive pressure on the economy. However, her comments represent one policymaker’s assessment and do not guarantee a particular outcome at the next meeting.
The broader message is that the BoJ’s discussion remains focused on when further action may be appropriate, alongside how the economy responds to earlier decisions.
Japan’s Inflation Outlook Shapes the Rate Debate
The BoJ faces the challenge of managing inflation while protecting the country’s economic recovery. Moving too slowly could allow price pressures to become more difficult to control. Moving too quickly could weaken demand and discourage investment.
Koeda’s remarks place greater emphasis on the first of those concerns. By highlighting upside inflation risks, she signals that waiting also carries a cost.
She called for timely interest rate adjustments based on economic conditions and the outlook for prices. She also referred to the estimated neutral interest rate, which is the level at which monetary policy neither encourages nor restrains economic activity.
That level cannot be measured precisely. Policymakers must judge where it may sit and assess whether current borrowing costs are still providing substantial support to the economy.
For currency traders, this debate matters because it helps shape expectations about how much further Japanese rates could rise. If the BoJ becomes more confident that inflation requires additional action, the Yen could receive further backing.
The October BoJ Meeting Takes on Greater Importance
The BoJ’s policy meeting scheduled for October 29–30 will give investors an opportunity to assess the board’s collective position.
Alongside its interest rate decision, the central bank is expected to publish updated projections for economic growth and inflation. Those forecasts could help explain whether officials see price pressures becoming more persistent or economic activity becoming more vulnerable.
A stronger inflation outlook could strengthen the argument for higher borrowing costs. A weaker growth assessment could encourage greater caution.
Investors will also examine how the BoJ describes the effects of its earlier rate increases. Koeda’s view that households and businesses have remained resilient is encouraging for those expecting further tightening. The updated assessment will show how widely that view is reflected in the central bank’s outlook.
The decision itself will therefore be only part of the story. The forecasts and accompanying explanation may have a lasting influence on expectations for the Yen.
Warsh Leaves the Fed’s Next Decision Open
On the US side, Warsh has declined to signal whether the Federal Reserve will raise interest rates again at its October meeting.
Speaking at an International Monetary Fund event, he emphasized that he does not want to prejudge policy decisions. His remarks reinforced his preference for allowing incoming economic information to guide expectations.
That approach leaves investors with less certainty about the Fed’s immediate plans. It also means that individual data releases can take on greater importance as markets try to judge what policymakers are likely to do.
The Dollar faced selling after his comments, helping USDJPY move lower. However, the absence of a clear signal does not mean that another rate increase has been ruled out.
Warsh’s position keeps the decision open. Investors must now assess whether the evidence available before the meeting gives the Fed a stronger reason to tighten policy or hold borrowing costs steady.
Strong US Producer Inflation Complicates the Dollar Outlook
The latest US Producer Price Index report provides a reason for investors to remain cautious about expecting a prolonged Dollar decline.
Producer inflation accelerated to an annual rate of 6.3% in September, up from a revised 5.6% in the previous month. The result exceeded expectations for a 5.3% increase and marked the largest annual rise since 2022.
Producer prices measure changes in the prices businesses receive for their goods and services. Strong increases can point to inflation pressures within the economy, although they do not automatically translate into an equal rise in consumer prices.
For the Fed, the report adds to the challenge of deciding whether inflation is sufficiently under control. Persistent pressure could keep further tightening under consideration.
For the Dollar, that possibility may help limit losses. Even without clear guidance from Warsh, stronger inflation gives investors a reason to remain alert to the prospect of higher US borrowing costs.
Summary
USDJPY is under pressure as Koeda’s comments strengthen expectations that the BoJ remains willing to raise interest rates. Her assessment that Japan’s economy has handled earlier increases adds weight to that discussion.
The Dollar faces uncertainty after Warsh declined to outline the Fed’s next move. However, stronger US producer inflation keeps another rate increase in the debate.
Attention now turns to incoming economic reports and the October policy meetings. The balance between Japan’s willingness to tighten and the Fed’s response to inflation will remain central to the outlook for USDJPY.
USDCAD Under Pressure as Oil Rally Lifts Canadian Dollar
USDCAD remains under pressure as a weaker US Dollar and firm crude oil prices give the Canadian Dollar an advantage. The pair has declined for a second consecutive session, reflecting a combination of lower US bond yields and changing expectations around Canadian monetary policy.
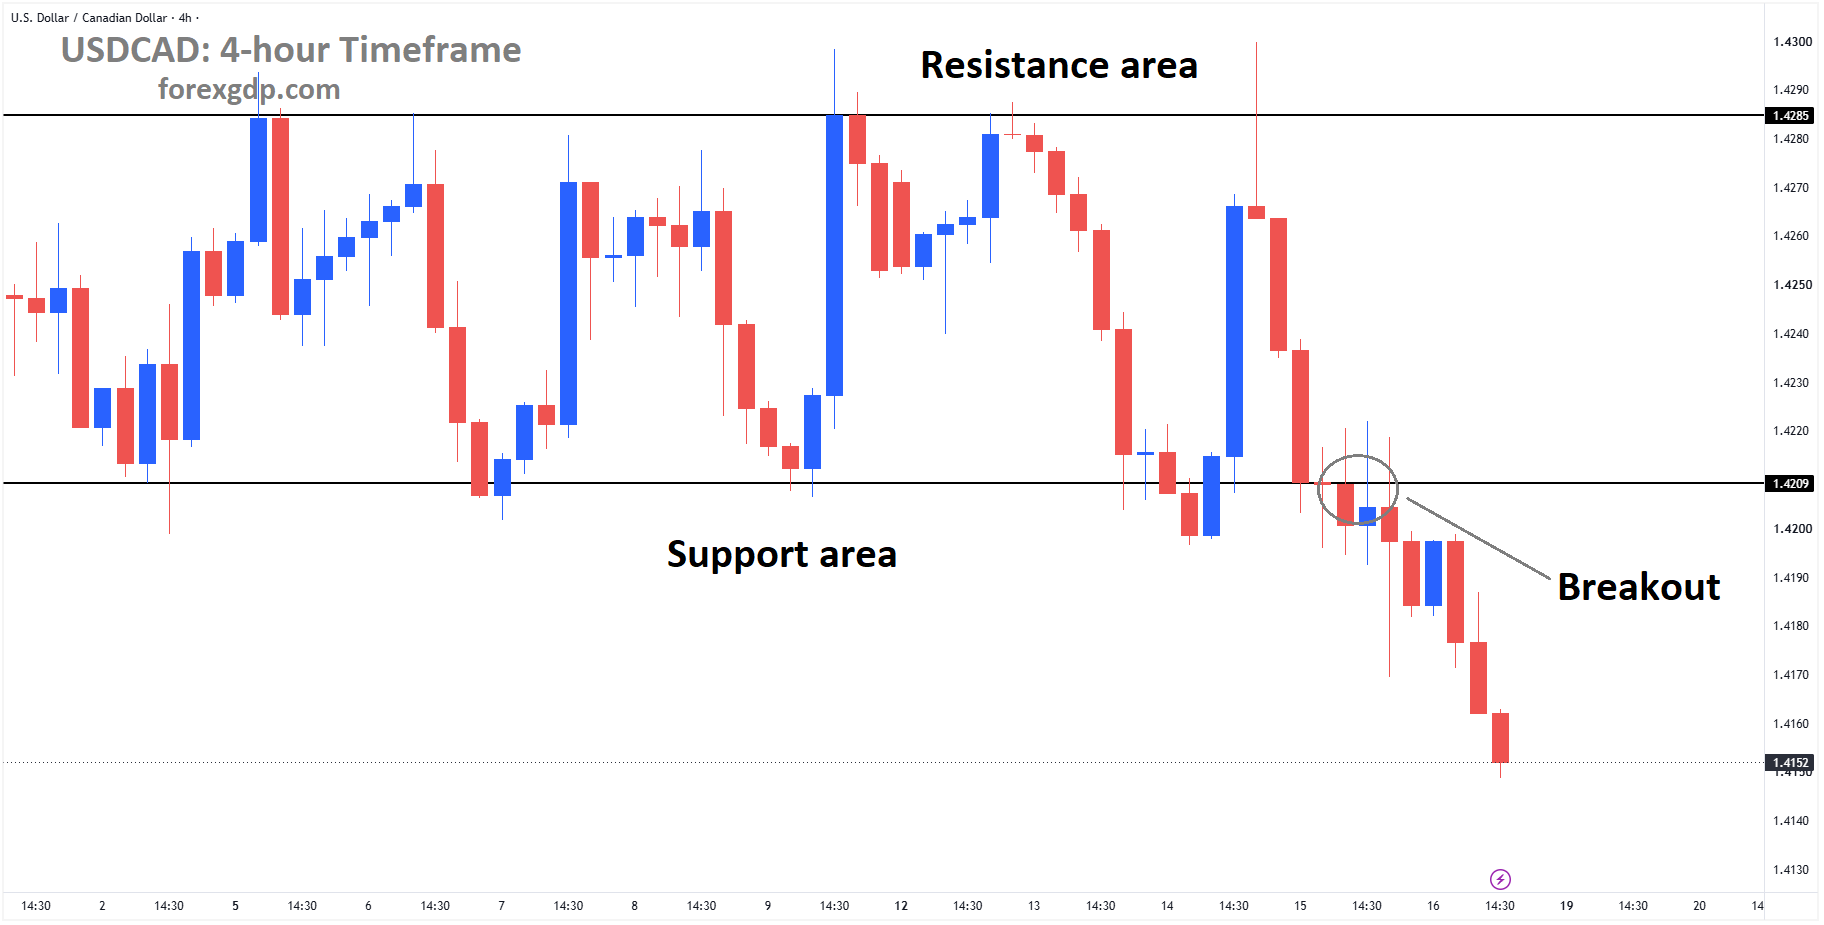
USDCAD has broken the support area of the box pattern
The US Dollar has struggled to regain strength, even after remarks from Federal Reserve Chair Kevin Warsh. His comments offered little reason for investors to change their expectations for interest rates, leaving falling Treasury yields as a more immediate influence on the currency.
Meanwhile, the Canadian Dollar has received support from the oil market and a tougher message on inflation from Bank of Canada Governor Tiff Macklem. However, uncertainty around US-Canada trade relations and tensions in the Middle East could complicate the outlook.
Lower US Bond Yields Weigh on the Dollar
Declining US Treasury yields have been a key source of pressure on the US Dollar. When yields fall, dollar-denominated investments can become less attractive to investors seeking stronger returns. This can reduce demand for the currency and give other major currencies room to strengthen.
The latest dollar weakness follows a strong earlier advance. As that move fades, investors are reassessing how much support the currency can receive from the Federal Reserve’s policy outlook.
Warsh’s neutral remarks did little to interrupt this adjustment. His message did not provide a clear new reason to expect a more forceful response from the central bank, leaving investors focused on bond markets and incoming economic information.
For USDCAD, this softer dollar backdrop has coincided with improving support for the Canadian currency. Together, those forces have kept the pair under selling pressure.
Firm Crude Oil Gives the Canadian Dollar Support
Crude oil remains an important influence on the Canadian Dollar because Canada is a major energy exporter. Stronger oil prices can improve the value of Canadian exports and support income across the country’s energy sector.
With oil holding near its strongest levels in several weeks, the Loonie has benefited from a more favourable commodity backdrop. That support has added to the pressure on USDCAD.
However, the relationship between oil and the Canadian Dollar is not always straightforward. The reason behind an oil rally matters. Stronger global demand can help Canada’s export outlook, while supply concerns linked to conflict can create broader economic uncertainty.
Higher energy costs can also increase expenses for households and businesses. This means Canada may benefit from stronger export earnings while still facing inflation challenges at home.
That balance is becoming increasingly relevant as the Bank of Canada considers how to respond to persistent price pressures.
Macklem’s Inflation Message Draws Attention
Bank of Canada Governor Tiff Macklem has drawn attention with comments suggesting that policymakers may find it harder to overlook rising energy costs if those increases continue.
Central banks sometimes look past temporary energy shocks because interest rates cannot directly increase oil supply or resolve transport disruptions. But a prolonged rise in energy costs can spread through the economy, making that approach more difficult.
Businesses may pass higher shipping and production costs on to customers. Households may also begin to expect inflation to remain elevated, potentially influencing wage demands and spending decisions.
Macklem’s remarks suggest that the Bank of Canada remains alert to these risks. Investors could therefore become less confident about future rate cuts and more open to the possibility of tighter policy.
That shift can support the Canadian Dollar. Still, a stronger warning about inflation does not amount to a commitment to raise rates. Future decisions will depend on how energy costs affect broader prices, demand and economic activity.
US Inflation Keeps Fed Tightening in Focus

Although the US Dollar has weakened, recent US inflation reports provide a reason for investors to remain cautious about expecting a sustained decline.
The Consumer Price Index and Producer Price Index reports pointed to price pressures extending beyond energy. This matters because broader inflation can be harder to bring under control than a temporary increase concentrated in one category.
Consumer inflation shows how household expenses are changing, while producer inflation helps reveal cost pressures facing businesses. Persistent increases across both can strengthen concerns that inflation is becoming more deeply embedded.
Those concerns have kept the possibility of another Federal Reserve rate increase in December in focus. Higher borrowing costs could eventually offer support to the dollar if economic data reinforce expectations for further tightening.
For now, however, that policy outlook has not been enough to offset the immediate effect of falling bond yields. The currency’s next move may depend on whether interest rate expectations and Treasury markets begin to point in the same direction.
Trade Friction Could Restrain the Loonie
US-Canada trade tensions remain a potential obstacle for the Canadian Dollar. Canada’s close economic relationship with the United States makes developments in cross-border trade particularly important.
Uncertainty over market access or future trade restrictions can make businesses more cautious about investment, production and hiring. Exporters may delay decisions if they cannot confidently estimate future costs or demand.
This creates a competing influence on the currency. Firm oil prices and a more cautious Bank of Canada can support the Loonie, while trade concerns may limit investors’ willingness to increase their exposure.
A deterioration in trade relations could therefore weaken the Canadian Dollar’s recent advantage, especially if it begins to affect expectations for Canadian growth.
Middle East Tensions Add Uncertainty
Escalating conflict in the Middle East adds another layer of uncertainty to USDCAD.
A deadly missile attack by the Iran-backed Houthi group targeting the presidential palace in Aden has added to regional concerns. At the same time, the US-Iran standoff over the Strait of Hormuz has kept attention on potential disruptions to energy shipments.
These developments can influence the currency pair through two different channels. Threats to oil supplies may support crude prices and benefit the Canadian Dollar. However, a broader increase in global risk aversion can encourage investors to seek the liquidity of the US Dollar.
The overall effect will depend on how events develop. An energy-focused response could favour the Loonie, while a wider move toward defensive assets could restore demand for the dollar.
Final Summary
USDCAD is facing pressure from falling US bond yields, a softer dollar and firm oil prices. Macklem’s warning about lasting energy inflation has also strengthened attention on the Bank of Canada’s policy outlook.
However, the balance remains unsettled. Broad US inflation pressures could reinforce expectations for further Fed tightening, while trade friction may restrain Canadian Dollar demand. Middle East tensions could support oil and the Loonie, but they could also revive defensive demand for the US Dollar.
USDCHF Gains Ground as Swiss Franc Loses Its Grip
USDCHF is finding some support after a sharp decline in the previous session, but its recovery remains uncertain. The US Dollar faces pressure as investors assess comments from American financial officials, while the Swiss Franc continues to attract demand during unsettled market conditions.
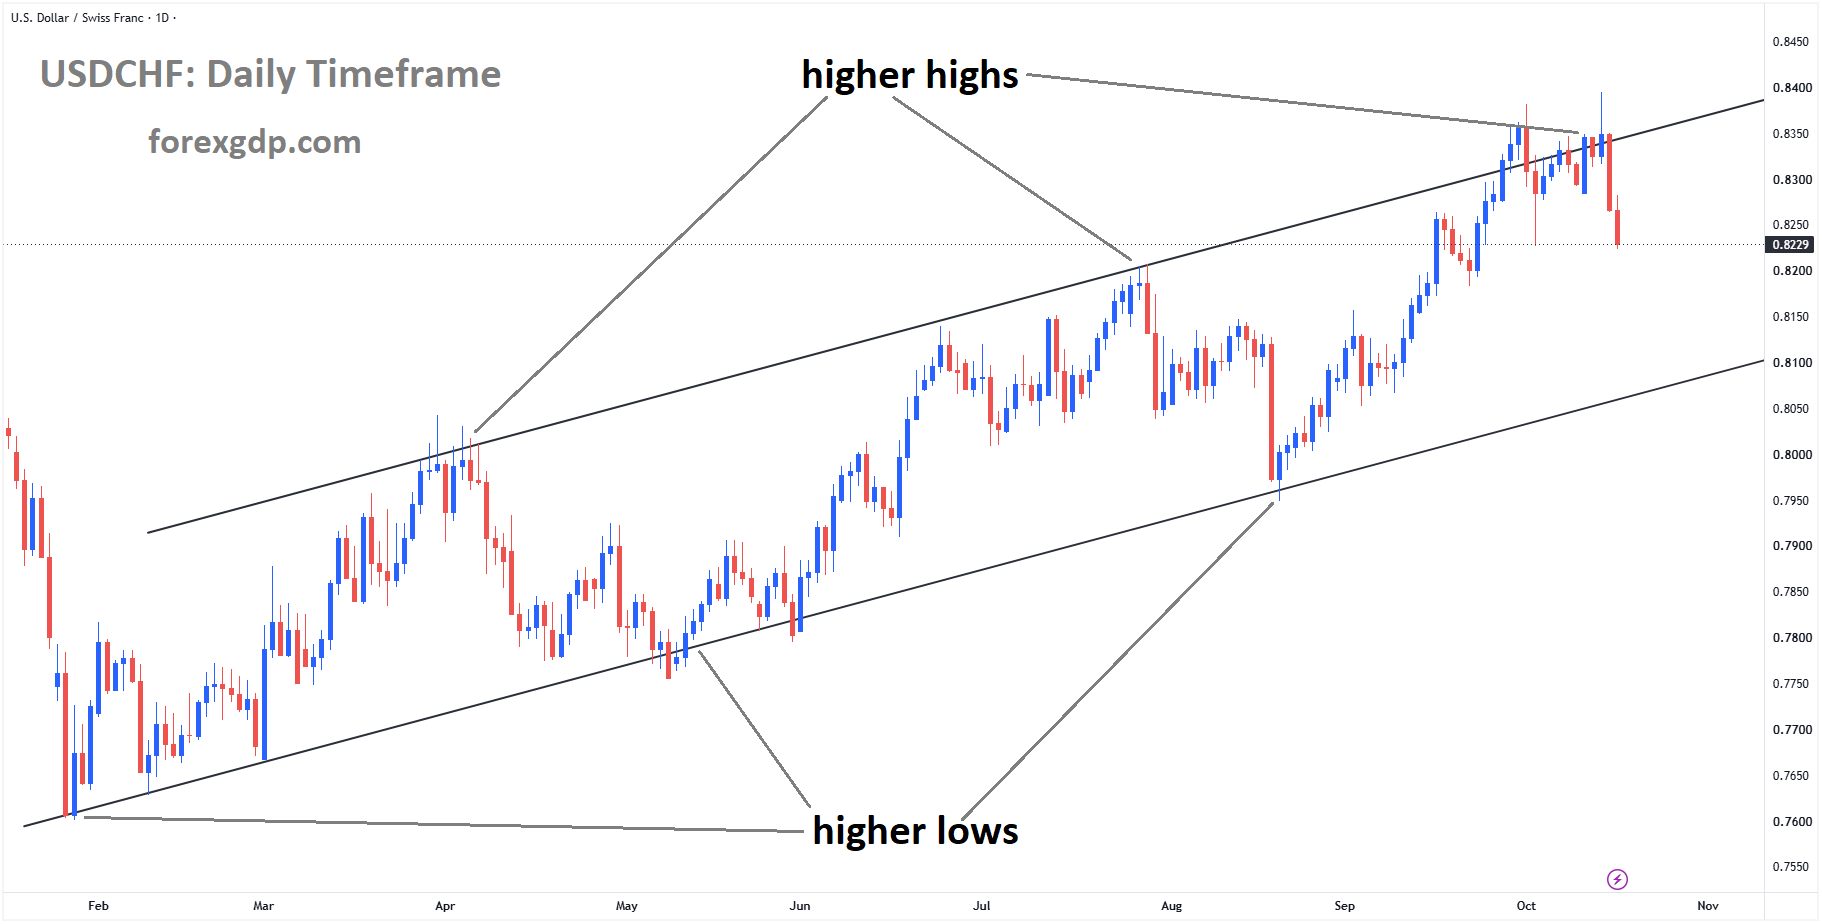
USDCHF is falling from the higher high area of the ascending channel
The pair reflects two competing forces. Expectations that US interest rates could stay elevated may offer the Dollar some support. At the same time, concerns about the economic effects of expensive borrowing are encouraging investors to seek the relative safety of the Swiss Franc.
Federal Reserve policy, inflation concerns and the outlook for major investment projects are all influencing sentiment. For USDCHF, the key question is whether the appeal of higher US interest rates can outweigh growing caution across financial markets.
Federal Reserve Keeps Price Stability at the Centre
Federal Reserve Chairman Kevin Warsh has reinforced the central bank’s commitment to price stability while avoiding any promise about upcoming interest rate decisions.
During a discussion with International Monetary Fund Managing Director Kristalina Georgieva in Bangkok, Warsh made it clear that policymakers were not ready to prejudge future meetings. His comments left investors weighing several possible policy outcomes rather than preparing for one clear direction.
That distinction matters for the US Dollar. A firm commitment to controlling inflation can support expectations of restrictive monetary policy. However, it does not automatically confirm that another rate increase is coming.
Markets must therefore consider both the Fed’s inflation concerns and its willingness to wait for further evidence. This uncertainty can make it difficult for the Dollar to sustain a recovery, even when expectations for higher interest rates remain part of the discussion.
Warsh also described the investment surge as a major source of strength for the global economy. His remarks highlighted the challenge facing policymakers: preserving economic progress while keeping inflation under control.
Higher Borrowing Costs Raise Questions About AI Spending
Stronger-than-expected US inflation figures have increased expectations of a possible Federal Reserve rate hike in October. That has brought the cost of financing back into focus, especially for industries that depend on large amounts of capital.
Artificial intelligence is one of the clearest examples. Expanding AI infrastructure requires spending on data centres, advanced computing equipment, electricity supplies and related facilities. These projects often involve substantial upfront costs, with returns developing over time.
When borrowing becomes more expensive, companies face tougher decisions about which projects to fund and how quickly to expand. Higher financing costs can also reduce the appeal of investments that depend on optimistic assumptions about future earnings.
This does not mean the AI investment cycle will stop. It does mean investors may examine spending plans more closely and become less willing to accept uncertain returns.
For currency markets, the effects extend beyond the technology sector. Concerns about investment spending can weaken broader confidence, encouraging investors to reduce exposure to risk and increase holdings of currencies associated with safety.
Swiss Franc Benefits From a More Cautious Market
The Swiss Franc has gained support from its safe-haven role as investors respond to market volatility and uncertainty over US monetary policy.
Higher US interest rate expectations do not always produce a stronger Dollar against the Franc. The reason behind those expectations matters. If investors believe tighter policy will control inflation without seriously damaging growth, the Dollar may benefit. If they fear it will place too much pressure on businesses and investment, demand for safety can become more influential.
That helps explain the Franc’s recent appeal. Investors are considering the potential strain of prolonged high borrowing costs alongside the possibility of another Fed rate increase.
Switzerland’s reputation for stability can attract capital during such periods. This demand may support the Franc even when Swiss interest rates remain much lower than those in the United States.
For USDCHF, the balance between interest rate expectations and investor caution remains central. A favourable rate gap alone may not be enough to lift the pair when defensive positioning dominates market behaviour.
US Treasury Comments Put Currency Volatility in Focus
US Treasury Undersecretary for International Affairs Erin Browne has added another dimension to the discussion by urging the IMF to take a stronger approach to identifying global economic imbalances.
She also called for a balanced assessment of the outlook, including the potential benefits of positive economic developments led by the United States.
Her remarks point to a broader debate about how investment, growth and international capital flows are changing the global economy. Stronger US investment could support economic activity, but its benefits must be considered alongside inflation pressures and differences in performance between countries.
Browne also warned that sharp and disorderly currency movements could spread volatility across financial markets.
Sudden exchange rate changes can complicate business planning, alter the cost of international trade and affect returns on overseas investments. Her comments underline why currency stability remains relevant beyond the foreign exchange market itself.
SNB Expectations Add Another Layer to the Outlook
The Swiss National Bank is widely expected to leave its policy rate unchanged through the end of the year. Policymakers have also softened warnings about active measures to influence the currency.
This leaves the Franc exposed to changes in global sentiment as well as domestic policy expectations. When investors become cautious, safe-haven demand can strengthen the currency even without expectations of higher Swiss interest rates.
Low Swiss borrowing costs also give the Franc a separate role as a funding currency. Investors may borrow in Francs to finance investments in assets offering higher returns elsewhere.
However, those positions can become less attractive when market uncertainty rises. Closing them can involve buying back the Franc, potentially adding to demand during periods of stress.
The currency’s role therefore changes with market conditions. Its low financing costs can encourage borrowing in calmer periods, while its defensive appeal can attract buyers when confidence weakens.
Summary
USDCHF is attempting to recover as investors weigh Federal Reserve uncertainty against continued demand for the Swiss Franc.
Warsh’s focus on price stability keeps restrictive US policy expectations in view, but his refusal to commit to future decisions leaves the outlook open. Meanwhile, concerns about borrowing costs and capital-heavy AI investment are encouraging a more cautious approach across markets.
With the SNB expected to hold policy steady, global sentiment remains an important influence on the Franc. The direction of USDCHF will depend on how investors balance US interest rate prospects, confidence in economic growth and the appeal of safety.
AUDUSD Finds Fresh Momentum as Greenback Loses Steam
The Australian Dollar is gaining ground against the US Dollar as traders weigh uncertain US monetary policy against weaker employment conditions in Australia. Selling pressure on the greenback has helped AUDUSD move higher, even as Australia’s latest jobs report reduces expectations for another interest rate increase.
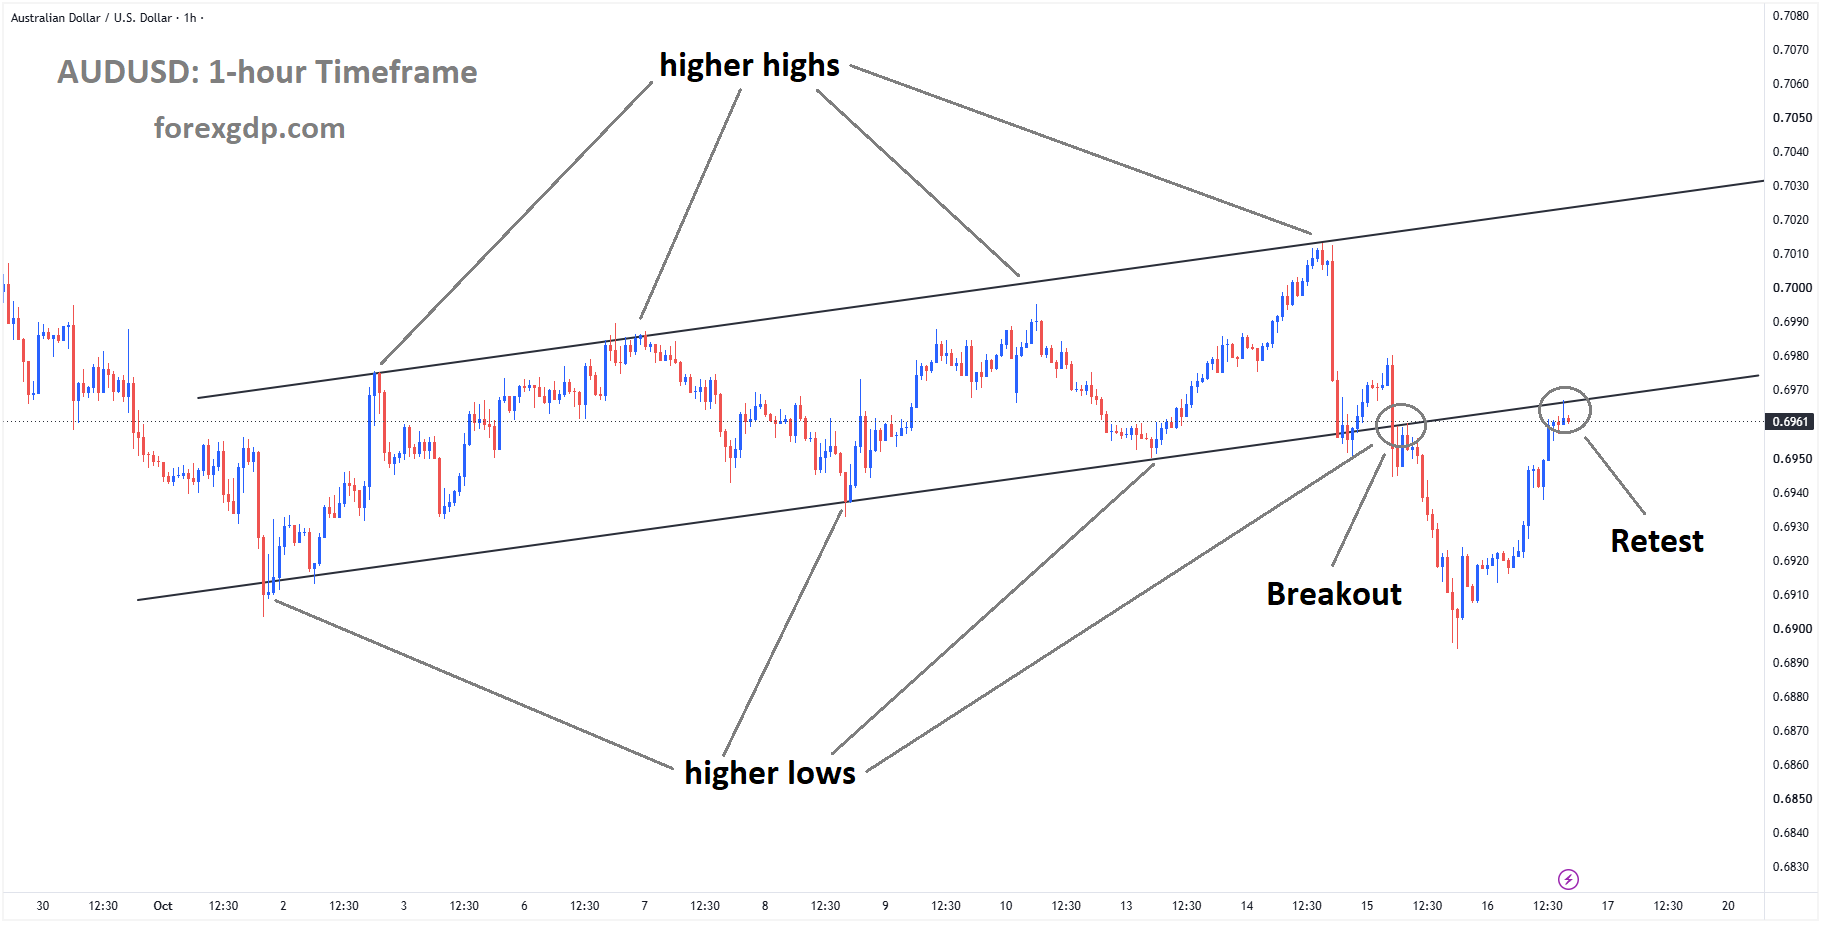
AUDUSD reached the retest area of the broken ascending channel
Comments from Federal Reserve Chair Kevin Warsh have left investors without a clear view of the central bank’s next move. His cautious approach has encouraged markets to reassess the outlook for US interest rates, putting some pressure on the Dollar.
Meanwhile, rising Australian unemployment and a decline in employment have given the Reserve Bank of Australia more to consider before its November policy meeting. These competing developments leave AUDUSD sensitive to economic releases and central bank communication.
Fed Comments Leave the US Dollar Without Clear Direction
The latest weakness in the US Dollar followed Warsh’s appearance at an International Monetary Fund event. Rather than outline a likely policy decision, he stressed that the Fed would assess conditions at its remaining meetings in October and December.
His message was that decisions would depend on the economic situation at the time. He also referred to the policy adjustment made about a month earlier, while avoiding any commitment about what would follow.
For currency traders, that leaves an important question unanswered: how will the Fed respond to the next round of economic data?
Interest rate expectations influence the appeal of a currency. When investors expect US rates to stay elevated, the Dollar can benefit from the prospect of stronger returns on Dollar-denominated assets. When confidence in that outlook fades, some of that advantage can weaken.
Warsh’s comments did not promise a particular outcome. However, they also gave traders little reason to become more confident about the future policy path. The resulting uncertainty contributed to selling pressure on the greenback, helping the Australian Dollar advance.
Australian Employment Data Changes the RBA Debate
While developments in the United States supported AUDUSD, Australia’s domestic figures presented a more difficult backdrop for the Aussie.
Data from the Australian Bureau of Statistics showed that unemployment rose to 4.7% in September, its highest level in nearly five years. Total employment also fell by 39,300, marking a noticeable deterioration in labour market conditions.
Employment matters because it connects household income, consumer spending and business activity. When fewer people are working, households may become more careful with their money. Those who remain employed may also delay larger purchases if they feel less secure about their jobs.
For the RBA, the report adds a reason to examine how the economy is responding to existing policy settings. Raising interest rates can help contain inflation, but it can also make borrowing more expensive and reduce demand.
A weaker labour market therefore complicates the case for further tightening. Policymakers must consider whether another increase is necessary and how much additional pressure households and businesses can absorb.
One monthly report cannot explain the entire economy. Still, the combination of higher unemployment and falling employment is significant enough to influence expectations ahead of the next meeting.
November Rate Hike Expectations Fall
Financial markets reacted to the employment figures by reducing the estimated likelihood of an RBA rate increase in November.
According to the supplied Bloomberg reporting, the probability fell below 20%, compared with around 35% before the data. That adjustment suggests investors now see a stronger chance that the central bank will leave rates unchanged.
Market expectations are not a promise of what the RBA will do. They reflect how investors interpret the information currently available, and they can change as new figures arrive.
Even so, the shift matters for the Australian Dollar. Expectations of higher interest rates can attract demand for a currency. When those expectations ease, that source of support becomes less certain.
This helps explain why the Aussie’s advance carries a mixed message. AUDUSD is benefiting from US Dollar weakness, while the domestic employment report is making investors more cautious about Australian interest rates.
Why AUDUSD Can Rise After Weak Australian Data
A currency pair reflects the relationship between two currencies. That means the Australian Dollar can strengthen against the US Dollar even when Australia releases disappointing economic news.
In this case, traders are assessing both sides of the pair. Australia’s weaker jobs report has reduced expectations for an RBA hike, but uncertainty surrounding Fed policy has also weighed on the greenback.
The immediate balance has favoured AUDUSD. That does not mean investors have dismissed Australia’s employment concerns. It means pressure on the US Dollar has been strong enough to help the pair gain ground.
The distinction matters when assessing the broader outlook. A move driven mainly by weakness in the opposing currency may tell a different story from one supported by improving domestic conditions.
For the Australian Dollar to gain broader backing, investors will want to see how employment, inflation and household demand develop together.
RBA Communication Takes on Greater Importance
Attention is also turning to the RBA’s annual report. Following the employment release, investors will examine its discussion of the economy for clues about how policymakers view the balance between inflation and slowing activity.
Rabobank analysts highlighted the deterioration in September employment and noted that the decline reversed job gains recorded in July. Their assessment underlined why the labour market has become an important part of the policy debate.
The annual report may provide useful context, although it does not replace a formal interest rate decision. Its discussion of employment and economic conditions could help investors understand the central bank’s concerns.
Future policy communication will matter alongside fresh data. A cautious assessment of growth could reinforce expectations for unchanged rates, while continued concern about inflation could keep the possibility of further tightening open.
Final Summary
AUDUSD is gaining support from a softer US Dollar after the Fed declined to offer a clear signal about its remaining policy meetings. At the same time, weaker Australian employment has reduced expectations for an RBA interest rate increase in November.
The pair’s outlook now depends on how these two policy stories develop. US economic releases will shape expectations for the Fed, while Australian labour and inflation figures will guide the RBA debate. For now, Dollar weakness is helping the Aussie advance, but Australia’s domestic slowdown remains an important concern.
NZDUSD Advances as Easing US Rate Outlook Lifts Kiwi
The New Zealand Dollar is gaining ground against the US Dollar as changing interest rate expectations reshape currency demand. Lower US Treasury yields and cautious comments from Federal Reserve officials have reduced the appeal of the Greenback, giving the Kiwi more room to advance.
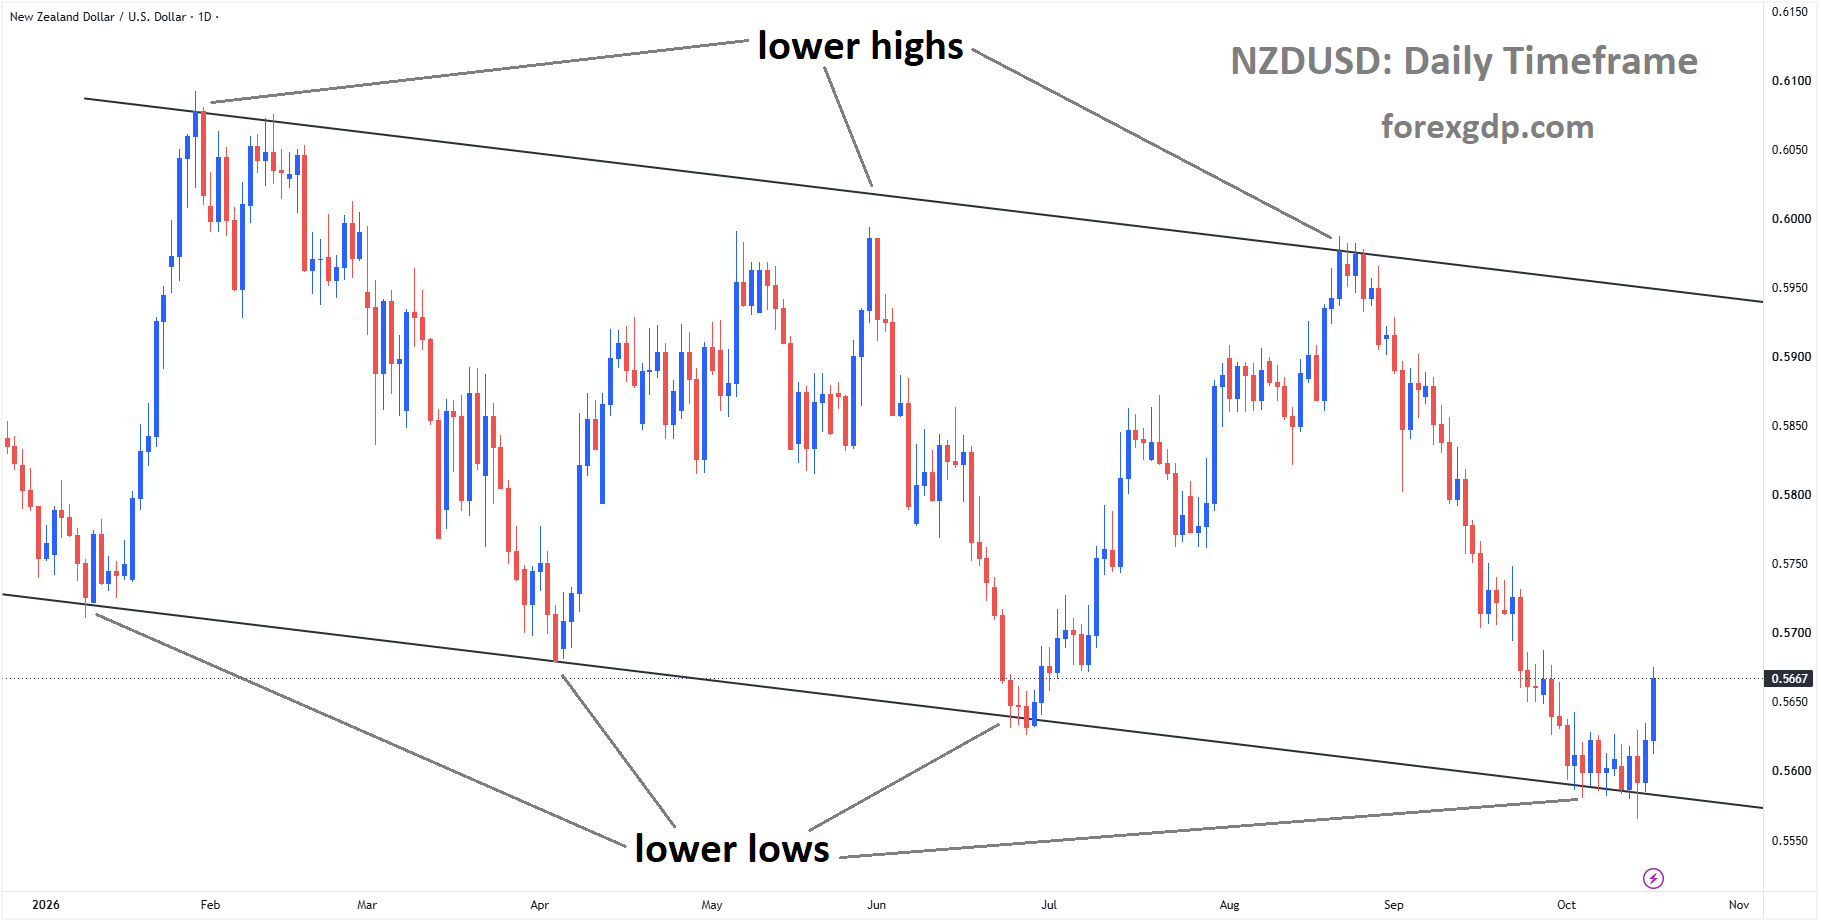
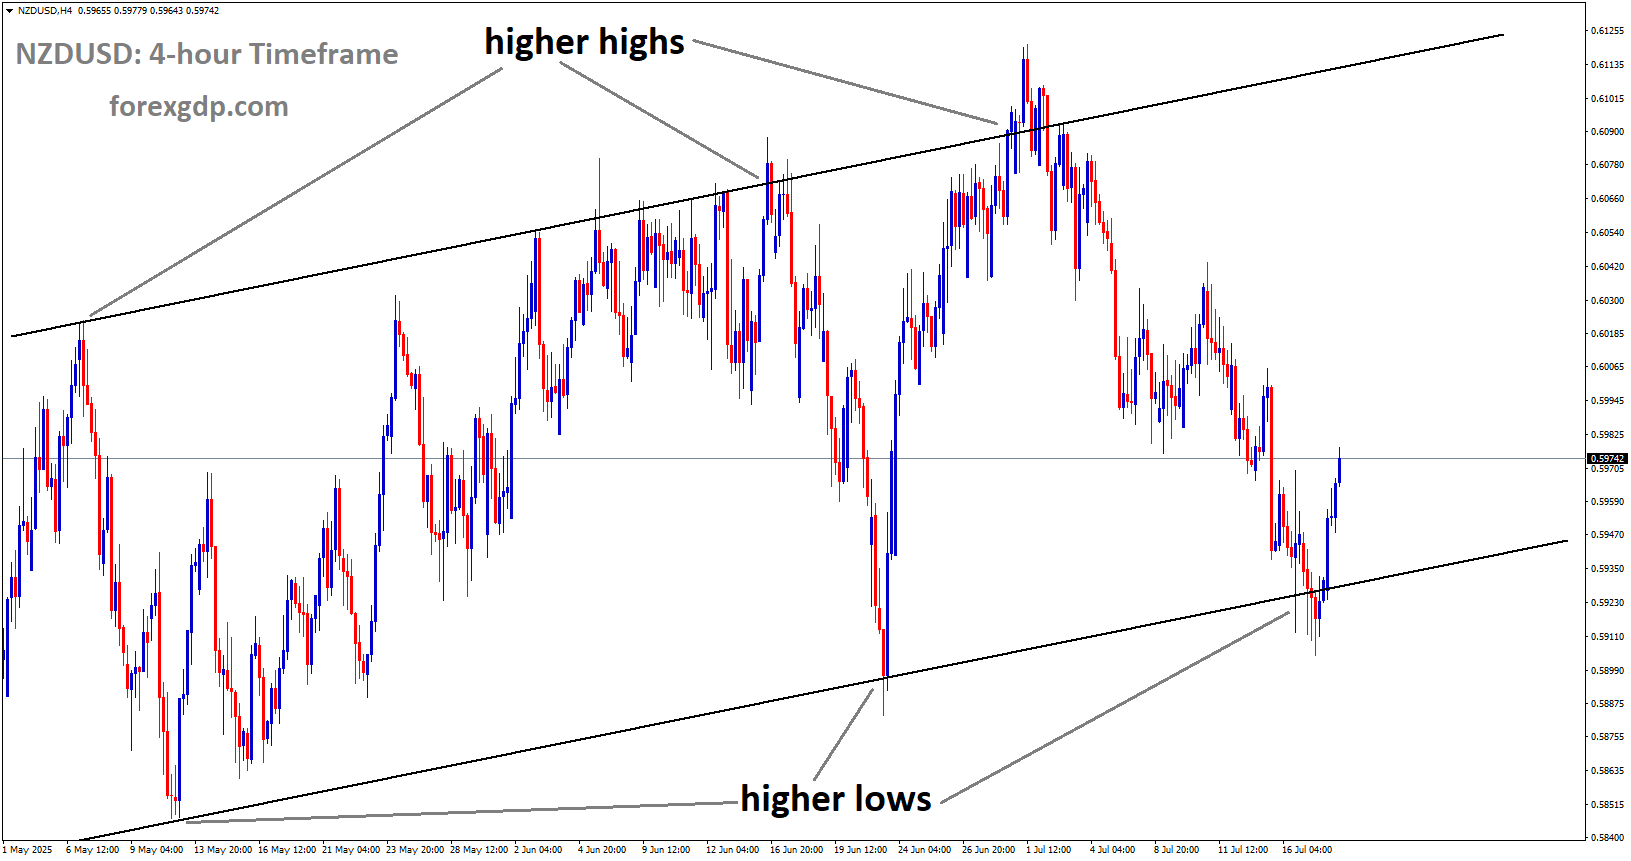
NZDUSD is rebounding from the lower low area of the descending channel
However, the outlook for NZDUSD involves more than a weaker US currency. New Zealand faces its own difficult mix of rising inflation and weak economic activity. An upcoming consumer inflation report could influence expectations for the Reserve Bank of New Zealand and determine whether the Kiwi can maintain its recent strength.
For now, investors are weighing two competing forces: reduced expectations for another immediate US rate increase and the possibility that New Zealand’s central bank may need to act against inflation.
A Softer US Dollar Gives the Kiwi Room to Advance
The New Zealand Dollar has emerged as one of the stronger major currencies during the latest trading session. Its advance reflects a shift in the wider financial environment, particularly the decline in US government bond yields.
Treasury yields influence the appeal of holding US Dollar investments. When those yields fall, investors may become less willing to favour the Greenback over other currencies. This can provide breathing room for currencies such as the New Zealand Dollar, which often responds to changes in global investment sentiment.
Recent Federal Reserve comments have added to that pressure on the US currency. Several officials have suggested that the central bank may keep interest rates unchanged at its October meeting while reviewing the effects of September’s increase.
That message has weakened expectations for another immediate move. As traders adjust their outlook, some of the demand that previously supported the Dollar has faded.
The Kiwi has benefited from this adjustment, although its continued progress will depend partly on whether US borrowing costs remain lower.
Strong US Economic Data Fails to Restore Dollar Demand
Recent US economic releases presented a picture of persistent inflation alongside resilient consumer spending.
Producer inflation accelerated more than expected in September, showing that price pressures remain a concern. Retail spending also held up, suggesting that households continued to spend even as they faced higher costs.
Normally, this combination could strengthen expectations for tighter monetary policy. Firm demand can make it harder for inflation to ease, while rising business costs may create further pressure on consumer prices.
Yet the Dollar did not receive a lasting boost from these figures. Investors appeared to place greater weight on the Federal Reserve’s cautious policy message.
This reaction highlights an important feature of currency markets: economic data matters, but its impact depends on how investors believe the central bank will respond.
If traders expect officials to wait before making another decision, even stronger figures may have a limited effect on rate expectations. In this case, the prospect of a pause has continued to weigh on the Greenback.
Warsh Leaves the Near-Term Policy Outlook Open
Federal Reserve Chair Kevin Warsh offered an optimistic assessment of economic resilience during remarks at an International Monetary Fund forum in Bangkok. However, he did not provide a clear signal about the next interest rate decision.
His comments left investors with little reason to make a firm judgment about the immediate policy path.
An economy that remains resilient gives the Federal Reserve room to assess conditions carefully. At the same time, persistent inflation means officials cannot easily dismiss the possibility that further action may become necessary.
For currency traders, that leaves considerable uncertainty. Confidence in the economy does not automatically translate into a commitment to higher interest rates.
Without a stronger policy signal, attention remains on incoming data and further comments from Federal Reserve officials. Until those provide a clearer direction, the Dollar may struggle to rebuild the demand it enjoyed when expectations for additional tightening were stronger.
Lower Bond Yields Carry a Mixed Message for the Kiwi
Falling US Treasury yields have helped the New Zealand Dollar, but the reasons behind that decline deserve attention.
Part of the move into government bonds has reflected demand for safety as concerns grow about stretched valuations linked to artificial intelligence. Buying bonds pushes their prices higher and their yields lower.
This creates a complicated environment for the Kiwi.
Lower US yields can reduce the Dollar’s interest rate advantage. However, the New Zealand Dollar is also sensitive to global risk appetite. If concerns about technology valuations spread into a broader retreat from risk, investors could become less willing to hold currencies associated with growth and market confidence.
The current benefit from lower yields therefore does not guarantee lasting support.
Much depends on whether financial conditions settle or whether the search for safety becomes more intense. The same bond market move that helps the Kiwi through lower US yields could eventually signal a less favourable backdrop for it.
New Zealand Inflation Puts the RBNZ in a Difficult Position
Attention is also turning to New Zealand’s upcoming Consumer Price Index report.
The release could play a major role in shaping expectations ahead of the Reserve Bank of New Zealand’s next monetary policy meeting. Renewed inflation pressure has already encouraged investors to consider the possibility of another rate increase.
Commerzbank analyst Volkmar Baur has highlighted the difficult balance facing policymakers. Inflation remains a concern, but economic activity is weak, making the case for tighter policy less straightforward.
Higher interest rates could help contain price pressures by slowing borrowing and spending. However, they could also add strain to households and businesses at a time when demand is already subdued.
The central bank must therefore assess both the strength of inflation and the economy’s ability to absorb further restraint.
Weak Demand Complicates Expectations for Higher Rates
Another key question is whether inflation is spreading more widely through the economy.
Baur has pointed to the continued absence of clear second-round effects. These can develop when an initial increase in prices leads to broader wage demands and repeated business price increases, making inflation harder to bring under control.
Without strong evidence of that process, policymakers may have more reason to examine the data carefully before acting.
For the Kiwi, the upcoming report could either reinforce expectations for higher rates or encourage investors to reconsider them. A strong headline reading alone may not settle the debate if underlying demand remains weak.
Final Summary
NZDUSD has gained support from lower US Treasury yields and reduced expectations for an immediate Federal Reserve rate increase. Resilient US data has not been enough to reverse that shift.
New Zealand’s inflation report now becomes an important focus. The RBNZ faces pressure to contain rising prices while protecting an already weak economy. The Kiwi’s next direction will depend on how that policy balance develops, alongside changes in US rate expectations and global investor sentiment.
EURGBP Extends Decline as UK Resilience Draws Investor Interest
The Euro remains under pressure against the British Pound as differences between the UK and Eurozone economies draw attention. Better-than-expected British growth figures have helped the Pound, while disappointing European industrial data has left the Euro struggling to regain ground.
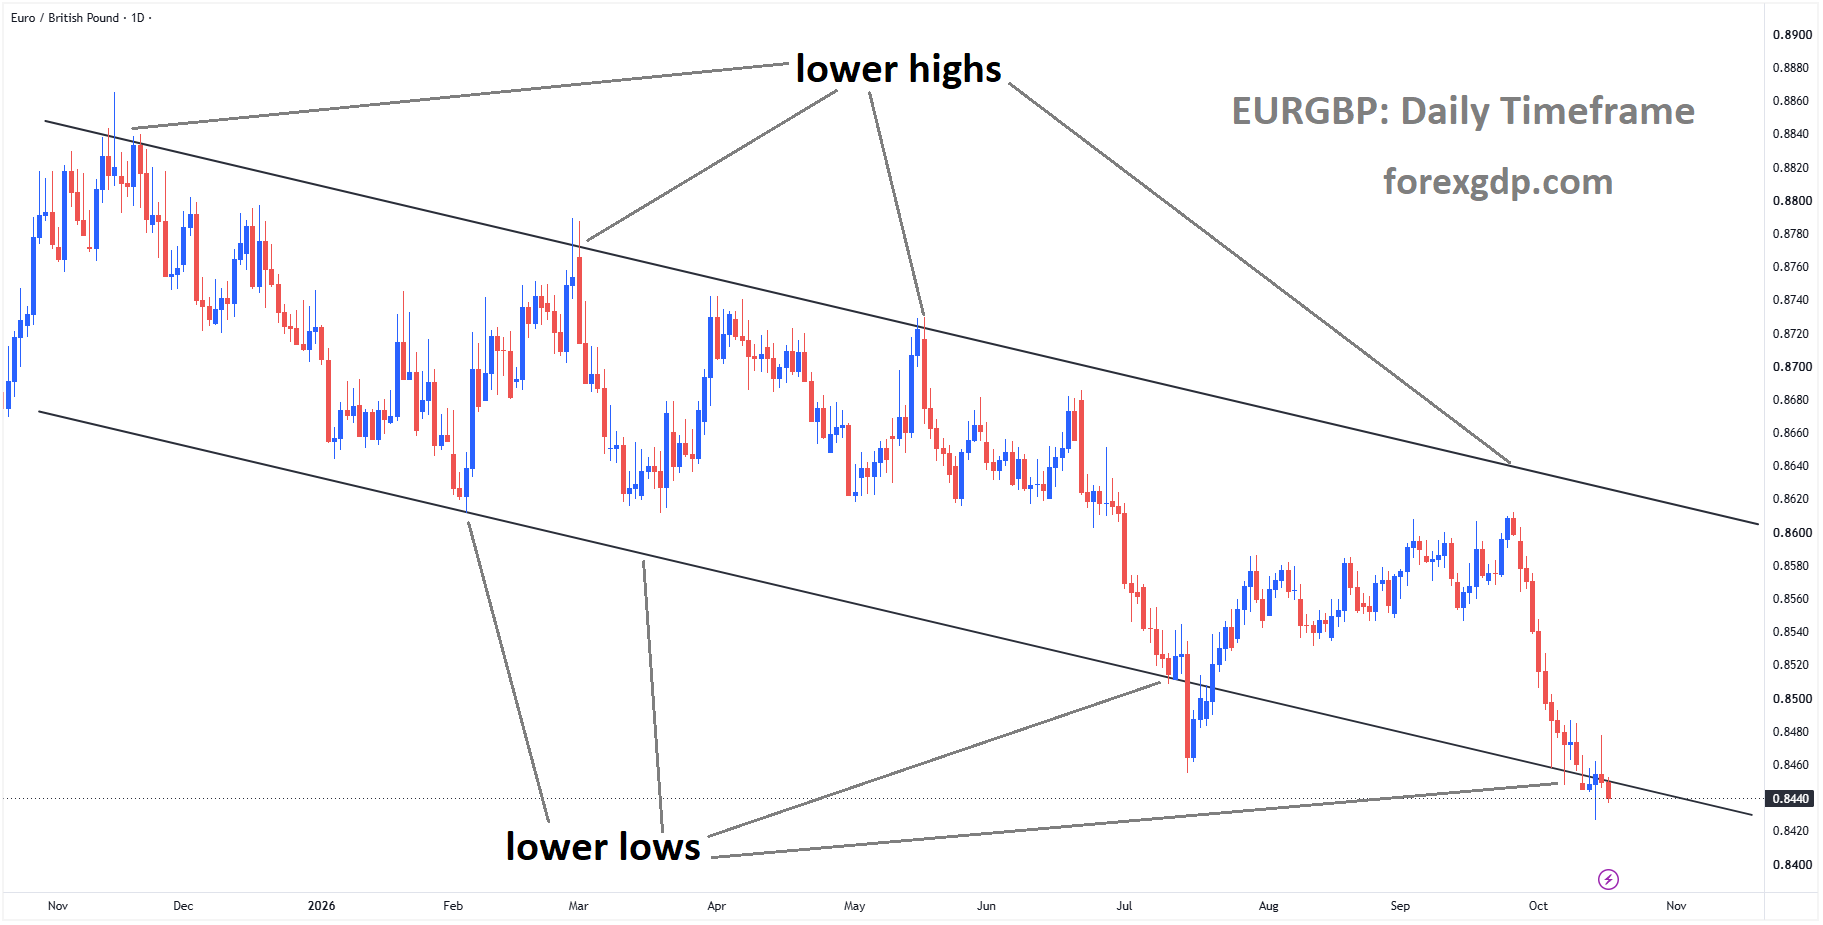
EURGBP reached the lower low area of the descending channel
The latest figures show that both economies face challenges, but the immediate picture looks more encouraging for the UK. Britain avoided an expected monthly contraction, giving investors a reason to reassess its economic strength. In contrast, Eurozone industrial activity fell, adding to concerns about the region’s manufacturing sector.
Comments from Bank of England Governor Andrew Bailey have also shaped the discussion. He remains concerned about lasting inflation, but his remarks offered little sign of an urgent push toward aggressive interest rate increases. For EURGBP, the focus remains on relative economic performance and what it could mean for monetary policy.
UK Growth Gives the Pound a Lift
The UK economy expanded by 0.1% in August, beating expectations for a contraction of the same size. Although the increase was small, the gap between the forecast and the actual result mattered.
When investors expect an economy to shrink, even modest growth can improve sentiment. The report suggested that British activity was holding up better than feared, helping the Pound attract demand against the Euro.
However, the details were less balanced than the headline result might suggest. Strong industrial activity helped offset softer performance in services and construction. This means the economy’s progress depended on strength in some areas while others continued to struggle.
That distinction matters because a lasting recovery needs broader participation. A stronger industrial sector can lift a single month’s growth, but continued weakness elsewhere could make future gains harder to maintain.
For now, the report has reduced some immediate concern about the UK economy. It has also given Sterling an advantage against a Euro facing weaker domestic economic news.
Eurozone Industrial Weakness Weighs on the Euro
The Eurozone’s industrial production report offered a less encouraging picture. Output fell by 0.5% in August, compared with expectations for an unchanged reading.
The disappointment did not end there. July’s figures were revised to show a 0.3% decline, larger than the previously reported 0.2% fall. Together, the latest result and the revision pointed to a weaker industrial backdrop than investors had expected.
Industrial production provides a useful view of activity across factories and other parts of the production economy. Falling output can suggest that businesses are responding to softer demand or facing difficult operating conditions. The figures alone do not explain every cause, but they do show that the sector is struggling to deliver consistent growth.
This creates a challenge for the Euro. Investors comparing the two economies have recently seen Britain outperform expectations while the Eurozone has fallen short.
Currency movements often reflect that difference. The Pound does not need a booming economy to gain against the Euro; it can benefit when British data looks relatively stronger.
Bailey Remains Watchful on Inflation
Andrew Bailey’s comments highlighted the difficult balance facing the Bank of England. Inflation remains a concern, yet economic growth is still weaker than policymakers would like.
The central issue is whether an initial rise in costs develops into more lasting inflation. This can happen when businesses repeatedly raise prices or when wage demands increase as workers try to protect their spending power.
These developments are often described as second-round effects. They matter because they can keep inflation elevated even after the original source of pressure begins to ease.
Bailey indicated that it was too early to reach firm judgments about the strength of such effects. He also described the signs so far as subdued.
His remarks suggested continued caution rather than an immediate case for forceful tightening. The Bank of England still needs to watch inflation closely, but the evidence presented did not point to an urgent change in approach.
The Pound’s reaction was limited. The stronger UK growth figures appeared to provide a clearer near-term influence on sentiment than Bailey’s measured comments.
Why Interest Rate Expectations Matter for EURGBP
Economic reports affect currencies partly because they can change expectations about interest rates. Stronger activity may give a central bank more room to keep borrowing costs elevated, while weaker growth can make that decision more difficult.
However, the relationship is rarely straightforward. A central bank must consider inflation, employment, wages and business conditions together.
For the Bank of England, unexpectedly positive growth offers some reassurance, but the uneven performance across sectors still calls for care. Policymakers cannot assume that one better month marks the start of a durable recovery.
The Eurozone faces a similarly difficult balance. Weak industrial output raises concerns about growth, while rising consumer inflation could complicate decisions about borrowing costs.
For EURGBP, the key question is how these pressures develop relative to one another. A change in expectations for either central bank can influence the appeal of the Euro or the Pound.
Eurozone Inflation Becomes the Next Focus
The final Eurozone Harmonised Index of Consumer Prices report is the next important release in the supplied economic calendar. It is expected to confirm that annual headline inflation accelerated to 3.8% in September from 3.2% in August.
Core inflation, which excludes energy and food, is expected to show a smaller increase, rising to 2.5% from 2.4%.
The difference between headline and core inflation helps investors assess how widely price pressures are spreading. A sharper rise in the headline measure alongside a modest core increase presents a different picture from a broad acceleration across both.
If the final figures match the preliminary estimates, attention may turn toward what is driving inflation and whether those pressures are likely to last. A meaningful revision could prompt investors to reconsider their expectations.
Either way, the report will add another piece to the Eurozone’s difficult mix of weak industrial activity and rising consumer prices.
Final Summary
EURGBP remains under pressure as better-than-expected UK growth gives the Pound an advantage over the Euro. Britain’s modest expansion offered reassurance, although softer services and construction activity showed that the recovery remains uneven.
Meanwhile, falling Eurozone industrial production and a downward revision to earlier data have weakened confidence in the region’s growth outlook. Bailey’s cautious inflation comments have done little to change that comparison.
The next stage will depend on whether British activity can maintain its recent resilience and how Eurozone inflation develops. Together, those developments will help shape expectations for both central banks and the direction of EURGBP.
EURCAD Jumps as Canadian Dollar Loses Ground to Euro
EURCAD has extended its advance for a second consecutive day, with the Euro finding support from stronger-than-expected inflation figures across the Eurozone. The data has encouraged investors to reconsider the European Central Bank’s next policy steps and increased interest in assets linked to the single currency.
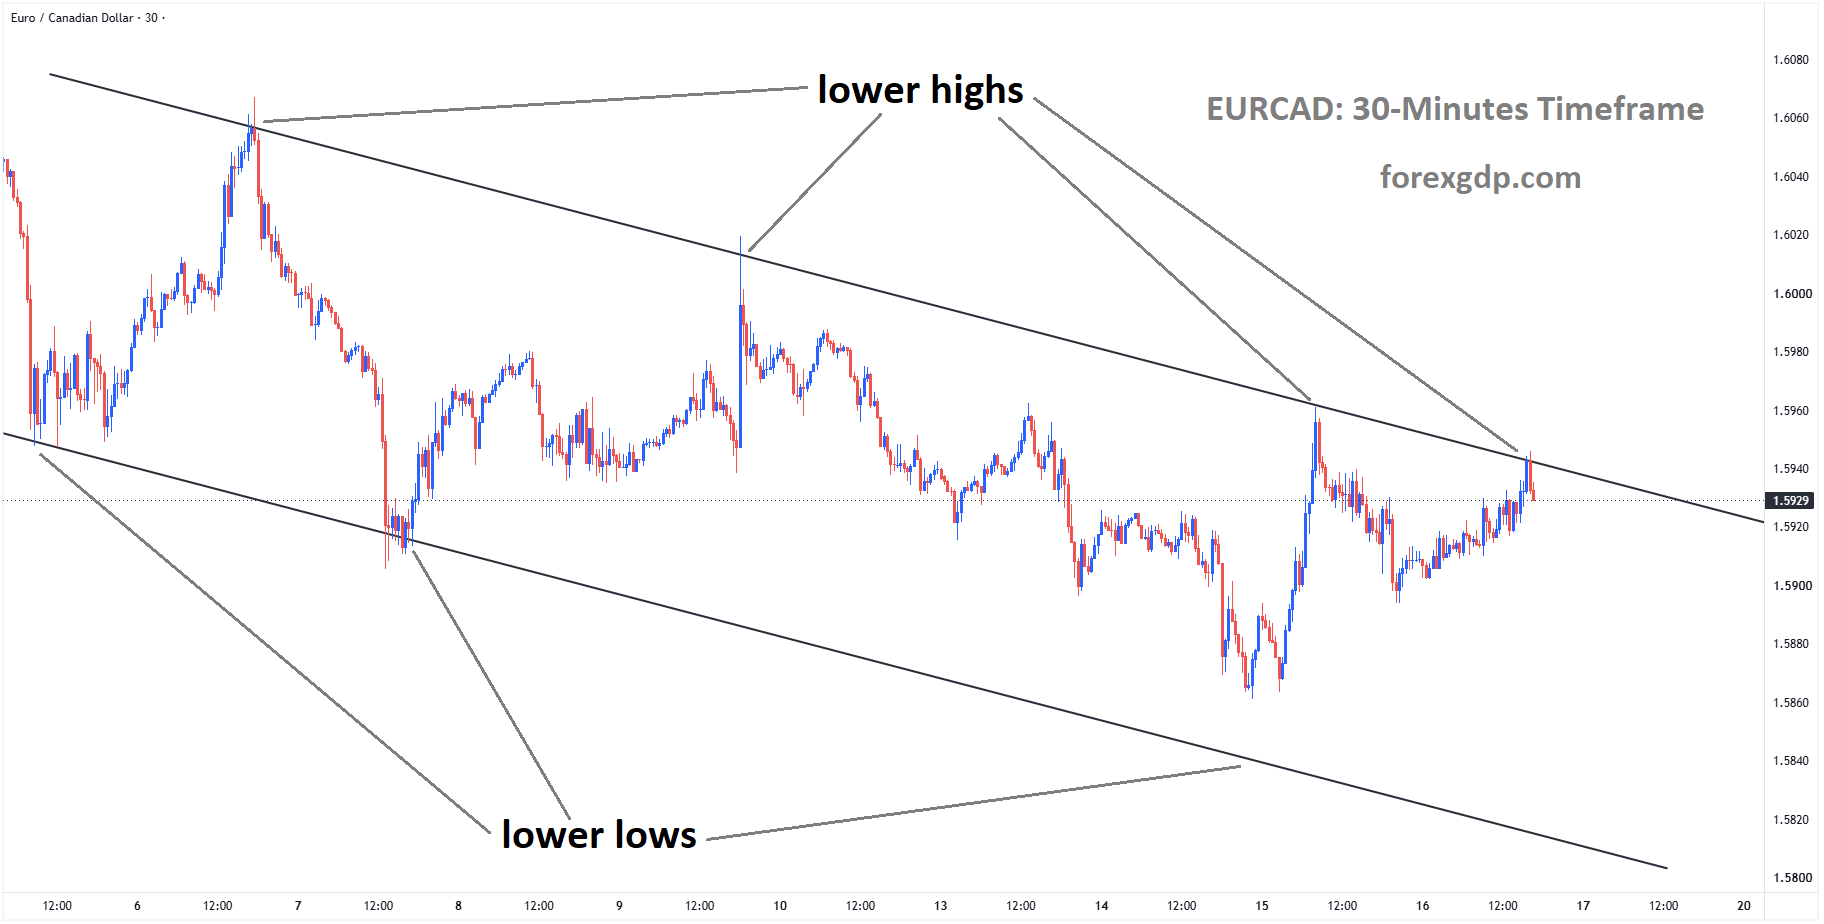
EURCAD reached the lower high area of the descending channel
However, the Euro faces several challenges. Political uncertainty in France and concerns about government debt could weaken investor confidence. At the same time, rising oil costs may provide support for the Canadian Dollar, giving the currency pair competing forces to respond to.
The wider picture brings together European inflation, French public finances, and growing concerns about global energy supplies. Each factor affects the two currencies differently, making the outlook more complicated than the recent gains alone suggest.
Eurozone Inflation Gives the Euro Fresh Support
Stronger inflation figures across Eurozone economies have helped improve sentiment toward the Euro. When inflation proves more stubborn than expected, investors often reassess how long a central bank may keep borrowing costs elevated or whether further tightening could become necessary.
These expectations matter because interest rates influence the appeal of holding a currency. If investors anticipate a firmer response from the ECB, euro-denominated assets may attract greater attention.
However, the reason behind rising inflation is just as important as the headline figures. An increase caused mainly by energy costs creates a different challenge from inflation driven by strong consumer spending or rapid wage growth.
Higher energy bills can lift inflation while reducing the money households have available for other purchases. Businesses may also face rising operating expenses, potentially weakening economic activity.
For the Euro, this creates a delicate balance. Inflation can strengthen expectations of tighter monetary policy, but it can also raise concerns about the health of the economy.
ECB Faces a Difficult Policy Decision
The ECB must judge whether energy-related inflation will remain limited or spread more widely through the economy.
Christine Lagarde’s comments, as described in the report, suggest that higher energy costs have not yet produced a broad increase in inflation across other areas. That assessment supports a careful approach, giving policymakers time to examine incoming evidence.
Other comments point to the possibility of a stronger response. ECB policymaker Gediminas Šimkus indicated that a rate increase could remain an option if conditions require it.
These views highlight the uncertainty facing the central bank. Policymakers need to prevent inflation from becoming entrenched without placing unnecessary pressure on businesses and households.
Investors will therefore pay close attention to more than energy bills. Wage developments, service-sector inflation, and consumer demand will help determine whether the recent inflation pressure is temporary or becoming more persistent.
For EURCAD, changes in those expectations could influence demand for the Euro even before the ECB makes its next decision.
French Debt Concerns Complicate the Euro’s Advance
Political uncertainty in France remains a potential obstacle for the single currency. Questions about government stability can make investors less confident about the country’s ability to deliver a credible plan for its public finances.
France’s debt position adds another layer of concern. Reducing budget pressures often requires difficult choices involving spending, taxation, or both. Political divisions can make those decisions harder to agree on and carry out.
Lagarde’s emphasis on fiscal consolidation places responsibility on France to address its debt challenges. Her remarks also temper expectations that the ECB could simply resolve the situation through purchases of French government bonds.
This distinction matters for investors. Monetary policy can influence financial conditions, but lasting improvements in public finances depend on government decisions.
Because France is a major Eurozone economy, uncertainty surrounding its finances can affect confidence beyond its borders. Even encouraging inflation data may offer only limited support for the Euro if political developments create fresh doubts about financial stability.
Oil Strength Offers the Canadian Dollar a Helping Hand

The Canadian Dollar has its own source of potential support through the energy market. Canada is a significant oil exporter, so stronger crude markets can improve expectations for export earnings and activity in the energy industry.
The reported weekly advance in West Texas Intermediate reflects growing concern about supply disruptions in the Middle East. For the Canadian currency, that backdrop may help offset some of the Euro’s recent strength.
Still, the relationship between oil and the Canadian Dollar is not automatic. Investors also consider domestic economic conditions, interest-rate expectations, and the broader appetite for risk.
A rise in oil driven by healthy demand can carry a different message from one caused by threatened supplies. Supply disruptions may benefit some exporters while increasing costs and uncertainty across the global economy.
As a result, oil strength gives the Canadian Dollar a supportive influence, but it does not guarantee gains against every major currency.
Shipping Disruptions Raise Energy Market Uncertainty
Concerns surrounding the Strait of Hormuz have added to anxiety over the movement of oil supplies. The reported attack on a Singapore-flagged container ship has increased doubts about how quickly normal shipping activity can resume.
Disruption along an important energy route can affect more than the availability of crude. Shipping delays, higher insurance expenses, and increased tanker costs can all make deliveries more expensive.
Buyers may respond by seeking supplies from alternative locations. This can shift demand between different sources of crude and change the relative appeal of shipments that face fewer transport difficulties.
Further violence in Yemen adds to the region’s instability. While separate incidents can have different effects on energy infrastructure, continued attacks make it harder for businesses to assess transport risks with confidence.
For currency markets, the key issue is whether these disruptions remain contained or begin to cause wider economic damage.
US Inventory Decline Adds Another Supply Concern
The reported fall in US crude inventories has added another reason for investors to monitor supply conditions closely.
A substantial inventory draw means less oil remains in storage to absorb unexpected changes in demand or deliveries. However, a single weekly reading does not establish a lasting shortage. Refinery activity, imports, exports, and temporary disruptions can all influence the figures.
The report also points to lower shipping costs helping attract demand for American crude. This shows how transport conditions can redirect buying interest even when the broader energy market faces uncertainty.
For the Canadian Dollar, sustained strength in the oil market could remain helpful. The wider effect will depend on how energy demand, available supply, and global economic conditions develop together.
Final Summary
EURCAD is responding to competing influences. Stronger Eurozone inflation has supported the Euro by encouraging expectations of a firmer ECB policy stance. French political uncertainty and debt concerns, however, could reduce that support.
Meanwhile, the Canadian Dollar may benefit from stronger oil markets, with shipping disruptions and falling US inventories keeping supply concerns in focus. The pair’s direction will depend on how these forces evolve, particularly whether European inflation broadens and whether energy disruptions continue to affect global trade.
GBPJPY Pushes Higher as Sterling Outshines the Japanese Yen
The British Pound has gained against the Japanese Yen as investors weigh Japan’s changing interest rate outlook and prepare for important economic reports from the United Kingdom. The move reflects a mixed picture for the Yen, which has struggled to attract stronger demand even after firm comments from Bank of Japan Governor Kazuo Ueda.
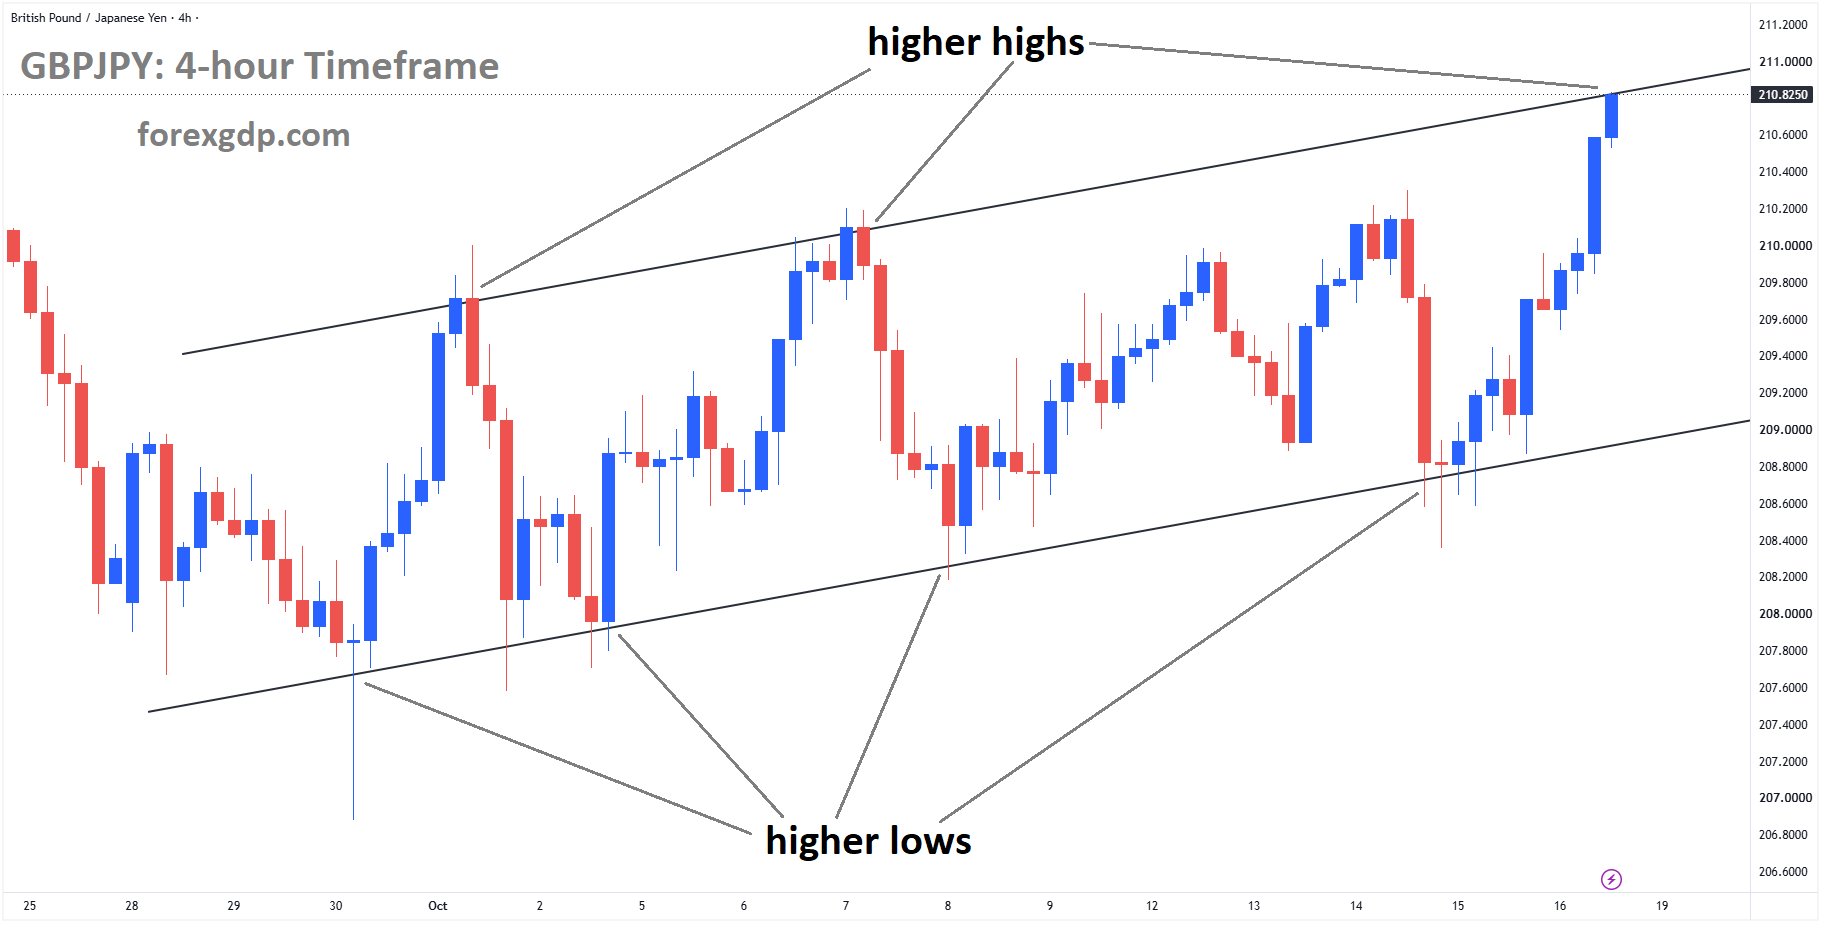
GBPJPY reached the higher high area of the ascending channel
Ueda’s message points toward further interest rate increases if Japan’s economy and inflation develop as expected. However, currency markets respond to more than the possibility of higher borrowing costs. Investors also consider how quickly those changes might arrive and how Japanese interest rates compare with those elsewhere.
For the Pound, attention is turning toward UK employment and inflation figures. These releases could influence expectations for the Bank of England’s next policy decisions, making them important for the GBPJPY outlook.
Pound Advances While the Yen Struggles for Support
The Pound’s rise against the Yen shows that a firm central bank message does not always produce an immediate currency recovery. Although Ueda has supported further policy tightening, investors still need to judge how much his comments change the likely timing of future decisions.
A central bank can signal that rates will rise gradually without suggesting that an increase is close. That distinction matters for the Yen. If investors already expect a cautious series of increases, another statement supporting that approach may offer limited fresh encouragement.
GBPJPY also reflects expectations about both economies. Demand for Sterling can remain steady while investors wait for UK figures, especially when those reports could change the outlook for British interest rates.
The result is a currency pair pulled by two separate policy debates: how far Japan can move away from very low borrowing costs, and how much room the Bank of England has to ease policy.
Ueda Keeps Further Interest Rate Increases in Focus
Ueda’s remarks suggest that the Bank of Japan remains committed to adjusting monetary policy as underlying inflation moves closer to its target.
Underlying inflation matters because it helps policymakers assess whether price growth can last beyond temporary changes in food or energy costs. The central bank wants evidence that inflation is supported by broader economic activity, including wages, spending, and business pricing decisions.
If those forces remain strong enough, further rate increases could become appropriate. However, Ueda’s approach remains tied to incoming evidence rather than a fixed schedule.
That leaves room for the Bank of Japan to respond to changes in the economy. Stronger domestic demand could support another increase, while weaker activity or unexpected global pressures could encourage officials to wait.
For investors, the key question is therefore about both direction and timing. A commitment to gradual tightening matters, but the pace of that process will help determine its influence on the Yen.
Japan’s Shift Away From Deflation Changes the Policy Debate
Japan’s long experience with weak price growth helps explain why its monetary policy adjustment attracts so much attention.
For years, policymakers focused on encouraging spending and preventing falling prices from becoming deeply established. Very low borrowing costs formed an important part of that effort.
A more durable inflation environment changes the challenge. The Bank of Japan must now consider how to keep price growth stable without placing unnecessary pressure on households and businesses.
Raising rates too quickly could weaken demand. Moving too slowly could make it harder to control inflation if wage growth and business costs continue feeding into consumer prices.
This balancing act helps explain Ueda’s measured language. Further increases remain possible, but officials want each decision to reflect the economy’s ability to handle higher borrowing costs.
The Yen’s response will depend partly on whether investors see this transition gathering speed or continuing cautiously.
UK Employment Data Could Reshape Pound Expectations
The upcoming UK labour market report will give investors a clearer view of hiring conditions and wage growth.
Pay growth is particularly important for the Bank of England because it can influence household spending and the costs businesses face. When wages rise strongly, some firms may pass higher expenses on to customers, especially in labour-intensive services.
If employment remains resilient and wage pressures stay elevated, investors may expect the Bank of England to take more time before lowering interest rates. That could provide support for Sterling.
A weaker report could lead to a different response. Slower hiring, softer pay growth, or rising unemployment may suggest that economic demand is cooling.
However, one figure rarely tells the whole story. Investors will need to consider wages, employment, and unemployment together to understand whether the labour market is easing gradually or losing strength more quickly.
Inflation Figures Add Another Important Test
The UK inflation report will provide a second major piece of evidence for the Pound.
Headline inflation shows the overall change in consumer prices, but policymakers also examine the details. Services inflation and measures that exclude volatile items can help reveal whether domestic price pressures remain persistent.
If inflation proves difficult to bring down, expectations for interest rate cuts could weaken. Investors may then see a stronger case for the Bank of England to maintain its cautious approach.
Softer inflation would give policymakers more room to consider easing, particularly if employment data also points toward slower economic activity.
The relationship between the two reports matters. Strong wages alongside stubborn inflation would send a different message from weaker hiring combined with easing price pressures. Mixed results could leave investors uncertain and produce sharper changes in Sterling demand as expectations adjust.
Final Summary
GBPJPY has advanced as the Yen struggles to benefit fully from Ueda’s support for further interest rate increases. Japan’s policy direction remains important, but the timing and pace of future moves will determine how strongly that message influences the currency.
For the Pound, UK employment and inflation figures are the next major focus. Together, they will help investors assess whether the Bank of England has room to lower borrowing costs or needs to remain cautious. The balance between those British data signals and Japan’s gradual policy adjustment will remain central to the pair’s outlook.
BTCUSD Bulls Feel the Strain as October Gains Slip Away
October often brings fresh optimism to the cryptocurrency market. Many traders call it “Uptober,” hoping Bitcoin and other digital assets will enjoy a strong month. This time, however, that confidence has faced a difficult test.
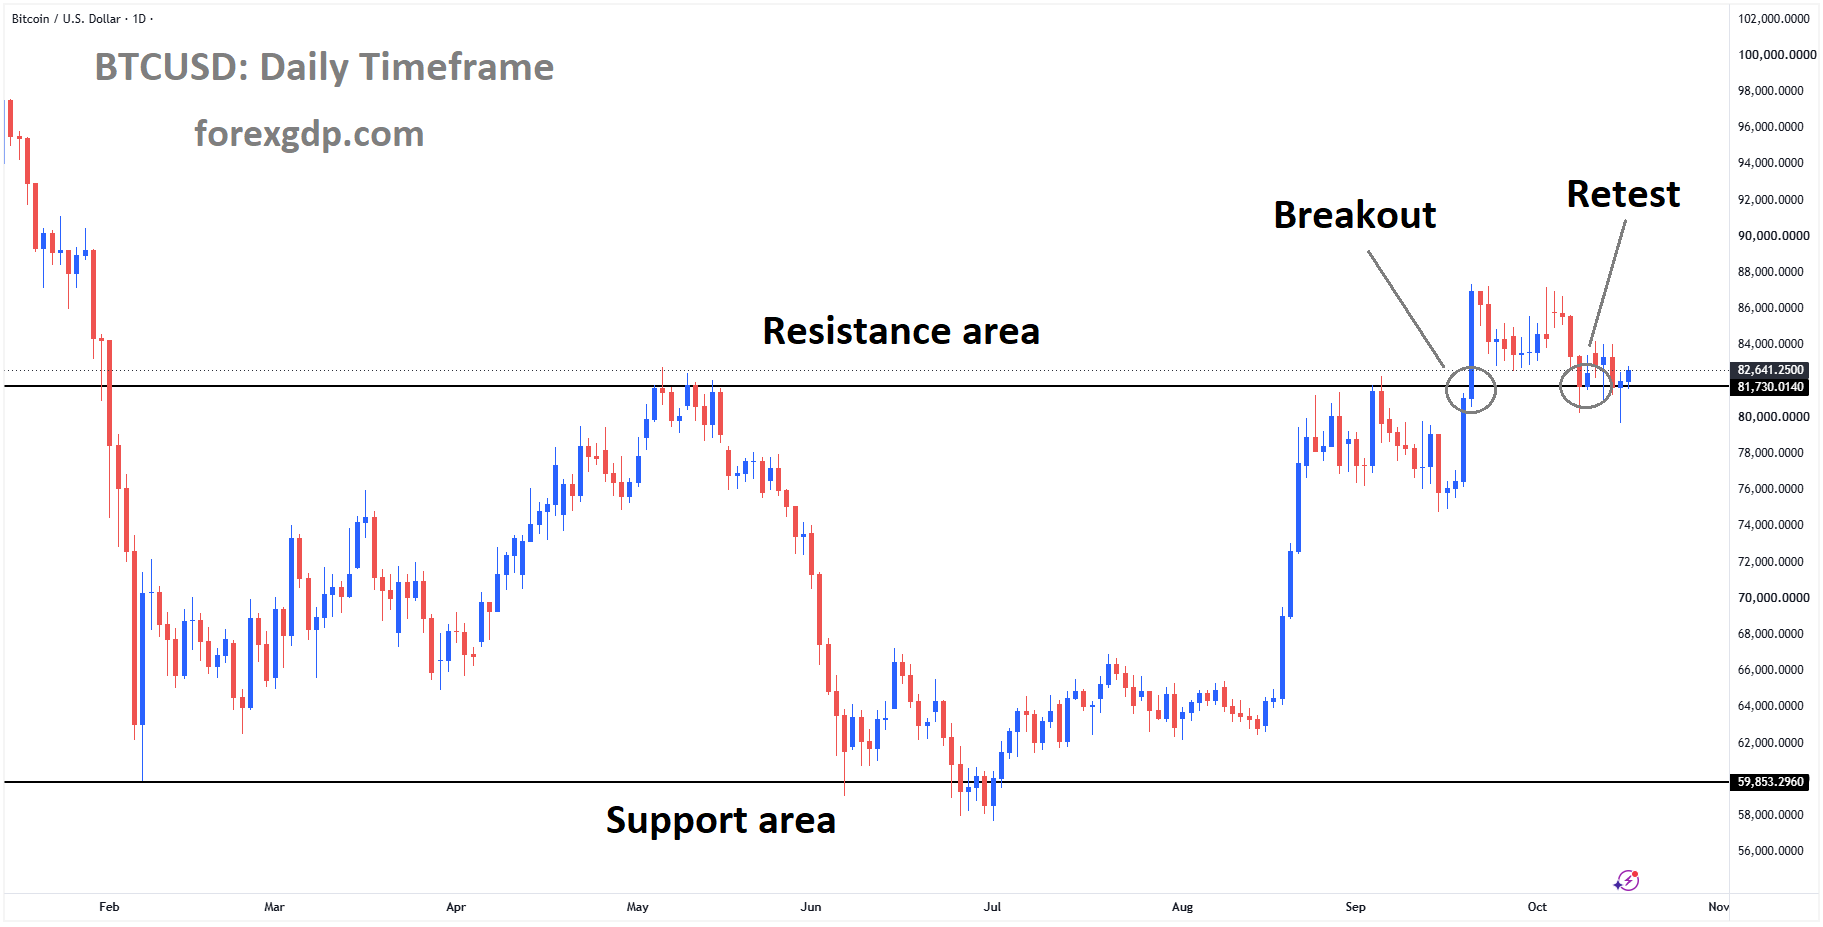
BTCUSD reached the retest area of the broken box pattern
Bitcoin has struggled to maintain its recovery attempts as selling pressure, forced trade closures, and concerns about the wider economy weigh on sentiment. Instead of the gains many expected, the market has experienced uncertainty and repeated setbacks.
That disappointment has brought another nickname into the conversation: “Rektober.” The term describes an October when losses replace the rally traders had hoped to see.
Behind the change in mood are several connected forces. Heavy borrowing has left some traders exposed, government bonds offer competition for investment money, and inflation concerns have complicated expectations for Federal Reserve policy.
Forced Liquidations Add to Bitcoin’s Selling Pressure
One major source of weakness has been the closure of leveraged long positions. These are trades that use borrowed money to increase exposure to an expected rise in Bitcoin.
Borrowing can increase profits when the market moves in a trader’s favour. However, it also increases the risk of rapid losses. When those losses become too large, an exchange may automatically close the position. This process is called liquidation.
When many bullish positions are liquidated together, the resulting sales can deepen a market decline. That creates a difficult cycle: falling markets trigger forced closures, and those closures generate additional selling.
The liquidation activity described in the market report suggests that many traders entered October expecting gains. Their positioning left them vulnerable when buying demand failed to meet those expectations.
This helps explain why Bitcoin can face sharp pressure even without a single major negative announcement. Sometimes, the structure of existing trades makes the market more sensitive to disappointment.
A reduction in borrowed exposure may eventually leave the market less vulnerable to forced selling. However, that process alone does not guarantee a recovery. Sustained demand still needs to return.
Higher Treasury Yields Create Competition for Investor Money
Bitcoin also faces competition from US government bonds.
When Treasury yields are elevated, investors can earn income from assets generally viewed as carrying relatively low credit risk. That can influence how they divide money between established investments and more volatile assets.
Bitcoin does not pay interest simply because someone holds it. Investors generally depend on future appreciation to earn a return, which makes the decision to hold it different from buying an interest-paying bond.
For institutions managing large portfolios, this comparison matters. Attractive bond income can reduce the urgency to increase exposure to cryptocurrency, particularly when economic conditions remain uncertain.
Higher borrowing costs can also make investors more cautious about taking risks. Businesses, funds, and individuals may have less room to finance speculative investments when credit becomes expensive.
This does not mean Bitcoin and Treasury yields always move in opposite directions. Cryptocurrency demand responds to many influences. Still, elevated yields can create a challenging environment when investors are already questioning the strength of a recovery.
A Stronger US Dollar Adds Another Challenge
Dollar strength can place additional pressure on the cryptocurrency market by affecting both purchasing power and investor confidence.
Because Bitcoin is commonly valued in US dollars, a stronger dollar can make purchases more expensive for people using other currencies. That may discourage some buyers or reduce the amount they can invest.
The dollar also plays a central role in global borrowing and financial transactions. When it strengthens, financial conditions can become more demanding for borrowers outside the United States.
In that environment, investors may prefer to hold cash or reduce exposure to volatile investments. Bitcoin can then struggle to attract fresh capital, even when interest in its long-term role remains intact.
The combined effect of dollar strength and attractive bond returns is particularly relevant. Investors have more reasons to remain patient, while cryptocurrency markets need committed buying to absorb ongoing sales.
Inflation Concerns Complicate the Federal Reserve Outlook

Inflation remains another important influence on Bitcoin sentiment.
When consumer prices rise faster than expected, investors may question whether the Federal Reserve has enough room to lower interest rates. Persistent inflation can strengthen the case for keeping monetary policy restrictive.
Producer prices also matter because they reveal changes in costs faced by businesses. Companies may absorb those costs, pass some of them to customers, or reduce spending elsewhere. The outcome depends on demand, competition, and profit margins.
A single inflation report does not settle the policy outlook. However, repeated signs of price pressure can make investors less confident that easier financial conditions will arrive soon.
For cryptocurrency markets, that uncertainty matters because expectations can influence investment decisions well before the Fed acts. If traders anticipate expensive borrowing and limited liquidity for longer, they may reduce their willingness to hold speculative positions.
Bitcoin’s reputation as a possible long-term hedge against currency weakness does not remove this short-term sensitivity. During periods of financial uncertainty, investors may sell it alongside other volatile assets to raise cash.
Cautious Fed Communication Leaves Traders Waiting
The supplied account of Federal Reserve communication points to a cautious approach toward upcoming interest-rate decisions. A refusal to commit in advance leaves investors assessing each new economic release.
That uncertainty can produce changing expectations. Remarks interpreted as less aggressive may ease concerns about an immediate rate increase, but they do not necessarily signal that rate cuts are approaching.
There is a meaningful difference between keeping rates unchanged and making policy less restrictive. Borrowing costs can remain a burden even when the central bank takes no further action.
For Bitcoin, this means a brief improvement in sentiment may need stronger support from economic conditions and investment demand before it becomes lasting confidence.
Summary
Bitcoin’s difficult October reflects several pressures working together. Leveraged liquidations have intensified selling, while elevated Treasury yields and dollar strength have made the investment environment more demanding.
Inflation concerns have added uncertainty about how long Federal Reserve policy may remain restrictive. Meanwhile, the failure of the expected “Uptober” rally has challenged traders who relied heavily on seasonal optimism.
A more durable improvement would depend on renewed buying interest, less fragile positioning, and greater confidence in the economic outlook. Until those conditions develop, expectations alone may struggle to carry the cryptocurrency market forward.
Don’t trade all the time, trade forex only at the confirmed trade setups
Get more confirmed trade signals at premium or supreme – Click here to get more signals, 2200%, 800% growth in Real Live USD trading account of our users – click here to see , or If you want to get FREE Trial signals, You can Join FREE Signals Now!