XAUUSD Faces Massive Selling Pressure as US Rate Hike Expectations Unsettle Gold Investors
Gold is experiencing one of its most challenging periods in recent months as growing uncertainty across global financial markets forces investors to rethink their investment strategies. The precious metal fell to its weakest level since September 2025 during Friday’s Asian trading session, extending a sharp decline that has unsettled investors.
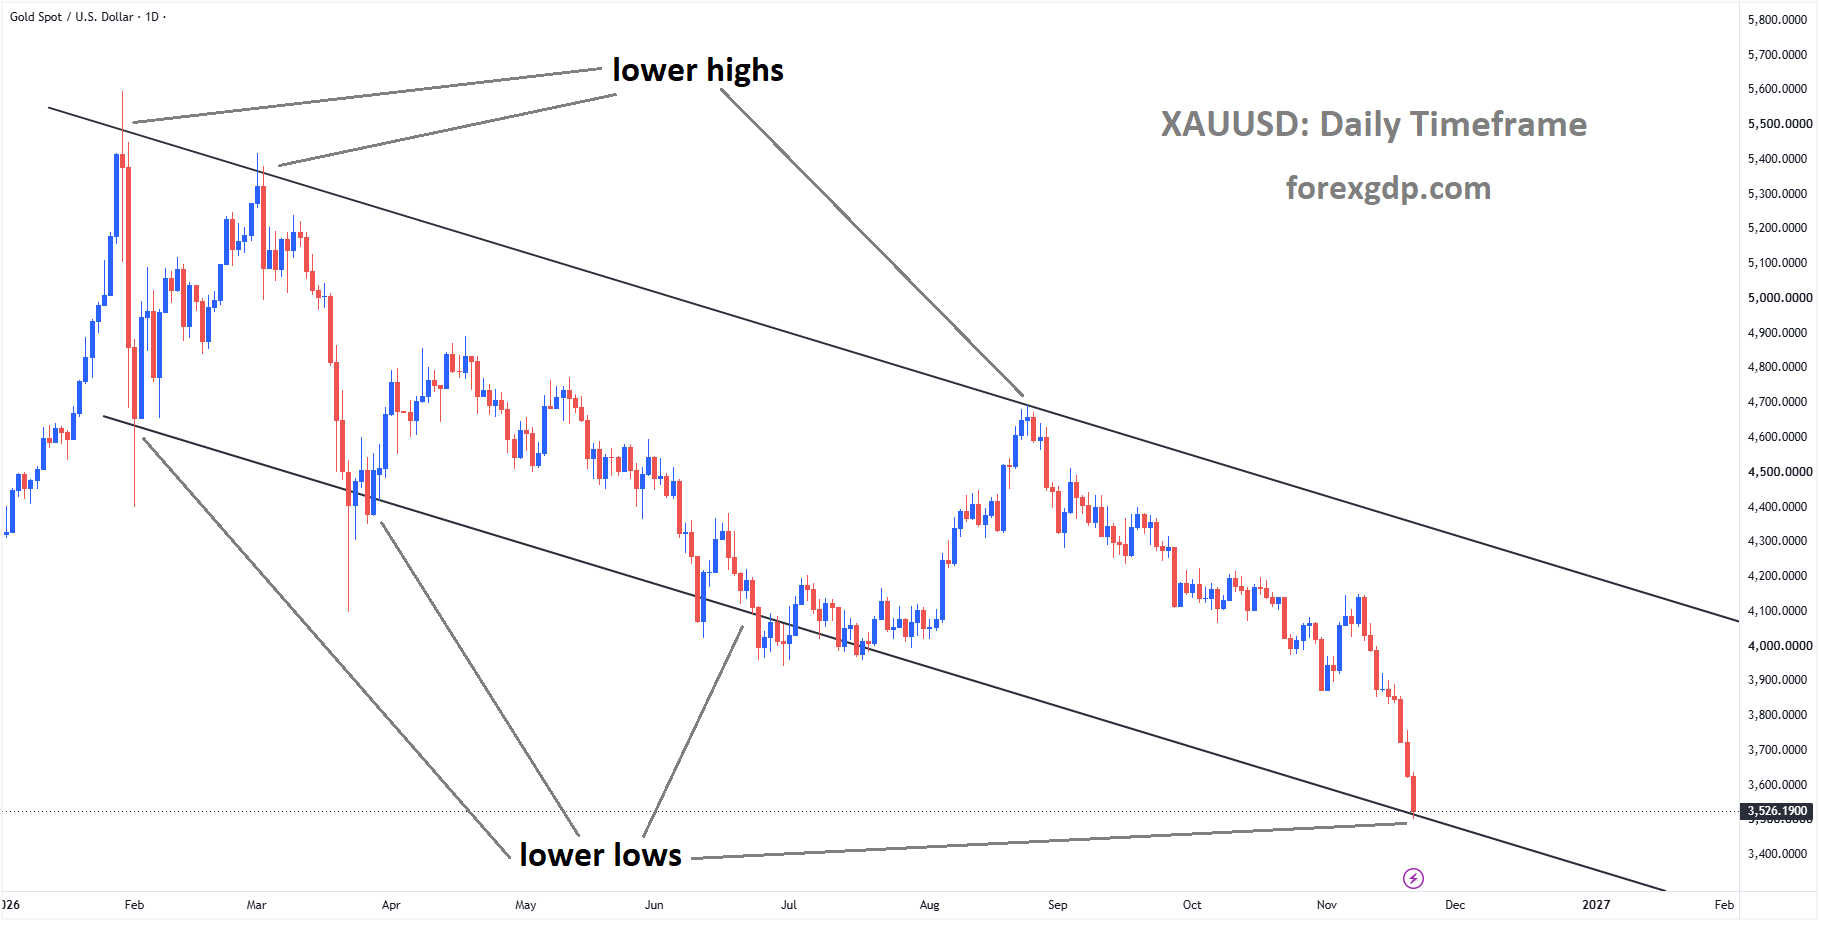
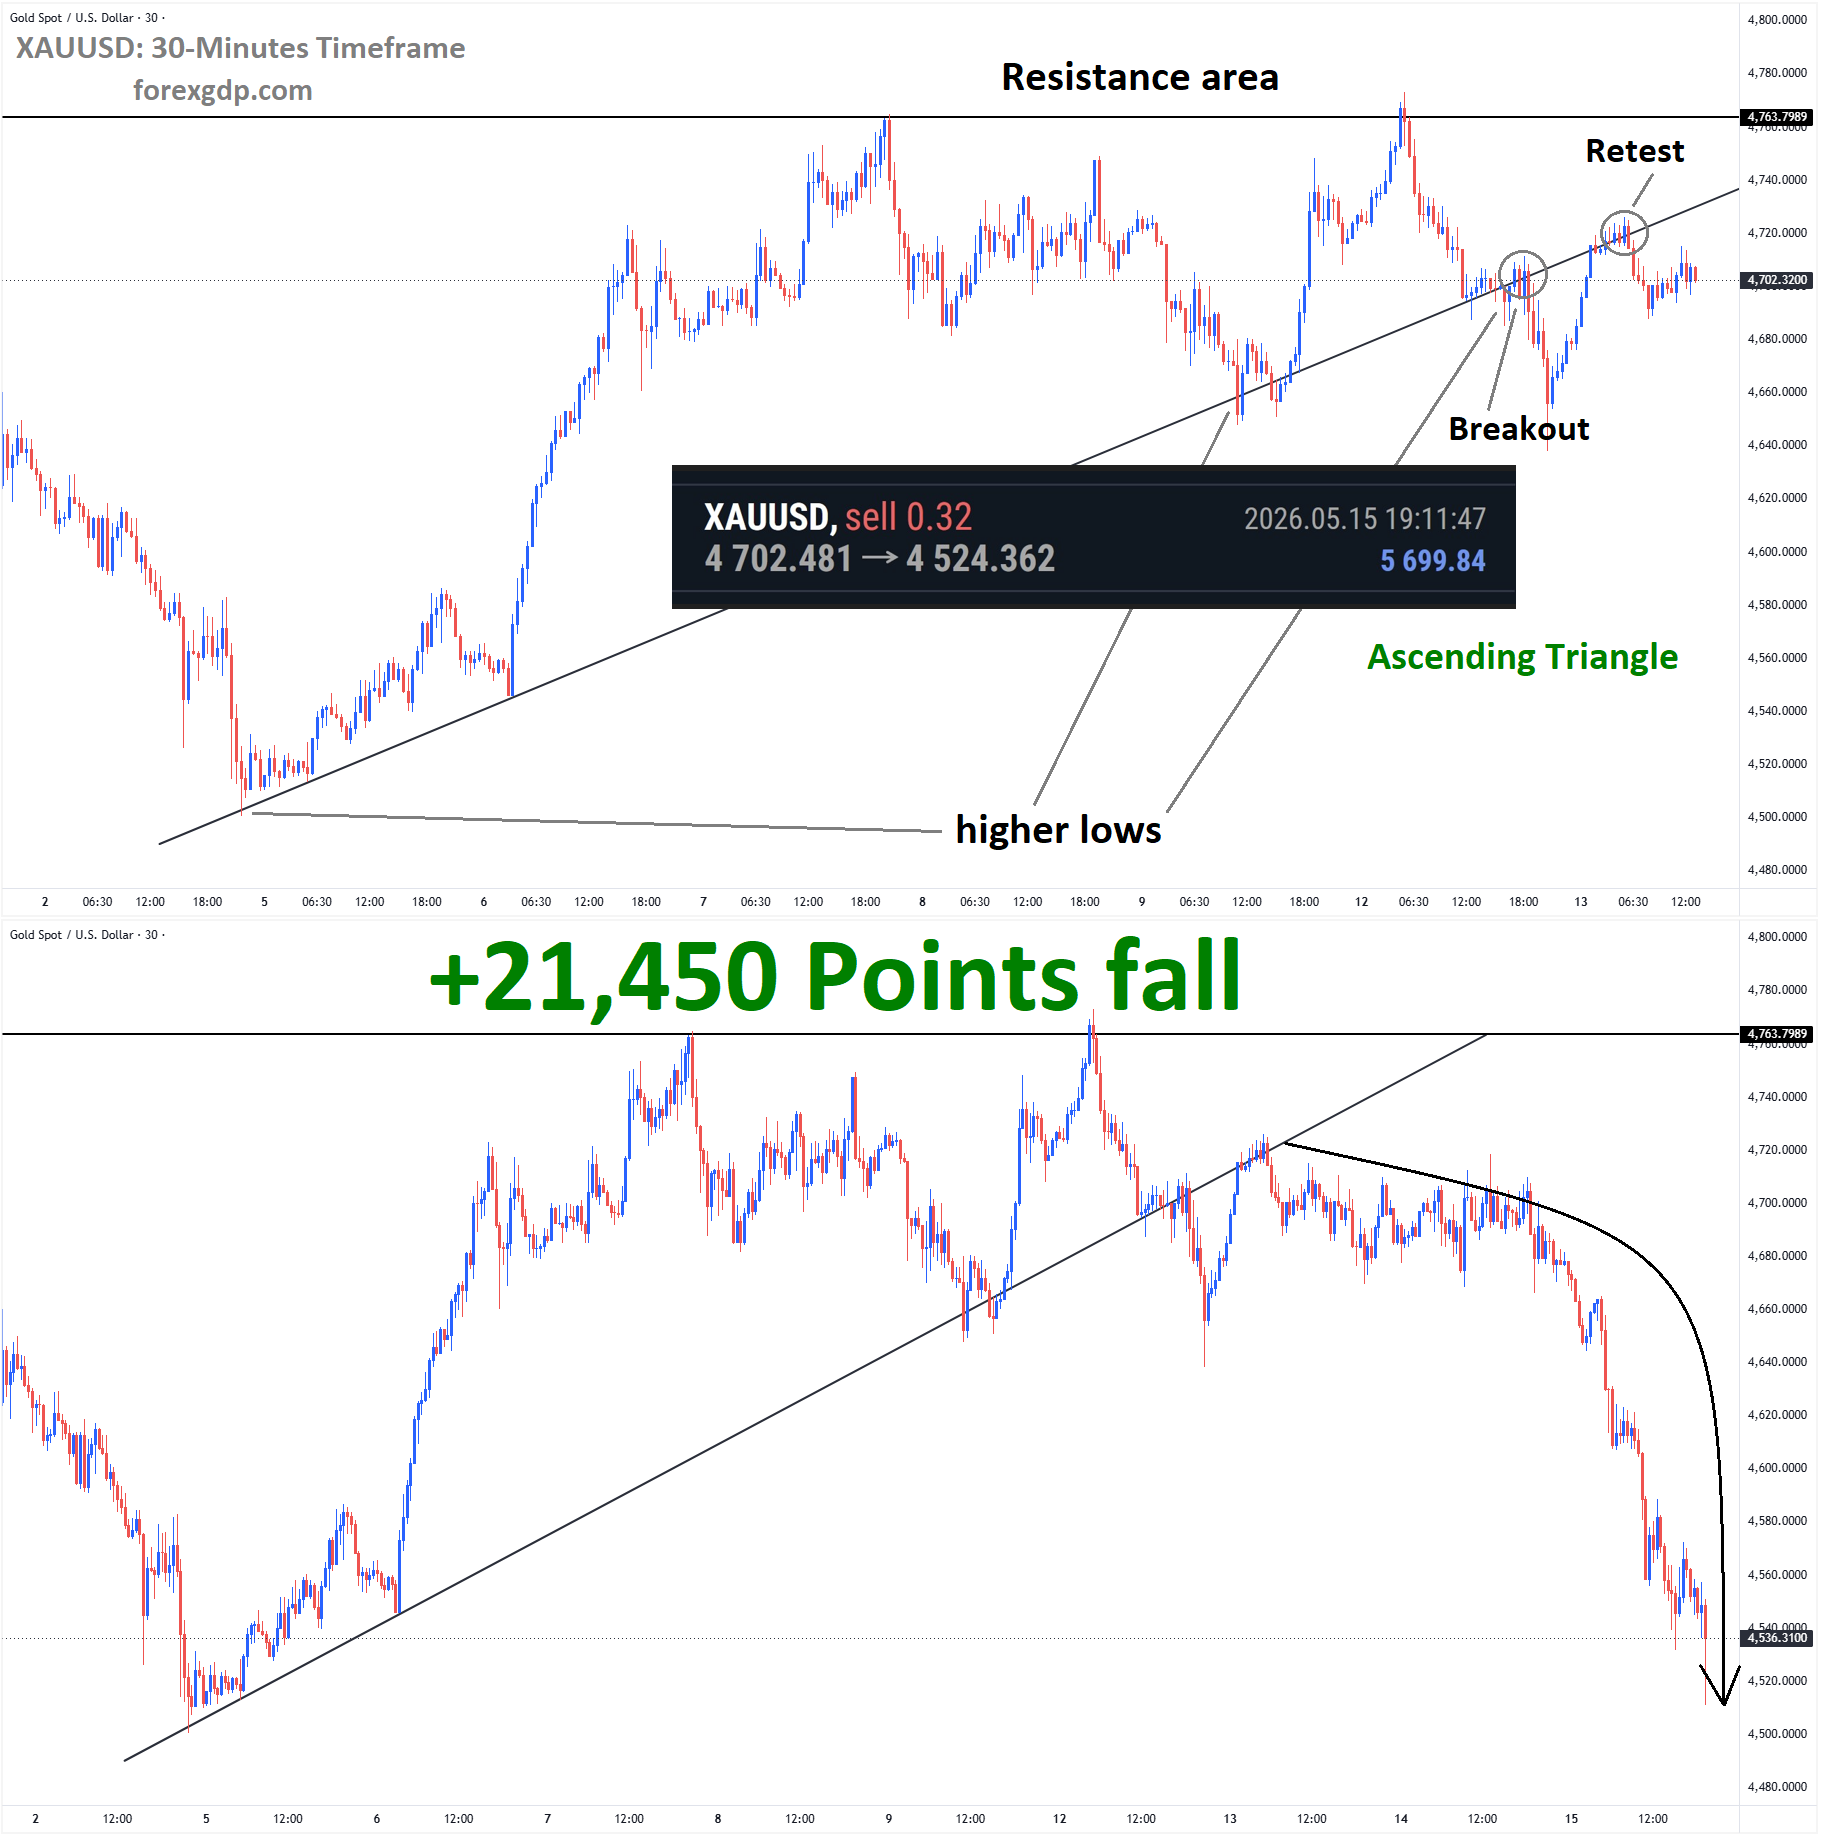
XAUUSD reached a lower low area of the descending channel
The latest weakness comes as global stock markets face widespread selling, while expectations of further interest rate increases by the US Federal Reserve add pressure to the precious metal.
Although gold is traditionally considered a safe-haven asset during periods of economic uncertainty, the current market environment has created an unusual situation. Investors facing losses in other investments appear to be selling their gold holdings to raise cash and manage financial risks.
Meanwhile, concerns about persistent inflation and the possibility of tighter monetary policy continue to influence investor sentiment. These developments have created a difficult environment for gold, despite ongoing uncertainty in the global economy.
Global Stock Market Sell-Off Adds Pressure on Gold
The sharp decline in global equities has become one of the major factors affecting gold’s performance. US stock markets have experienced substantial losses as investors grow increasingly concerned about economic conditions, corporate valuations, and the future direction of monetary policy.
Major Wall Street indexes have suffered significant weekly declines, reflecting a broader shift away from riskier investments.
Technology companies have been particularly vulnerable as questions surrounding artificial intelligence valuations continue to attract attention. Even the record-breaking initial public offering of Anthropic has failed to restore confidence in the sector.
Investors are increasingly questioning whether the rapid growth of artificial intelligence businesses can justify the high expectations surrounding them.
This uncertainty has contributed to a wider retreat from equities, encouraging investors to reconsider their exposure to different asset classes.
Gold has also been affected by this change in sentiment.
During periods of severe financial stress, investors sometimes sell assets they would normally prefer to hold for long-term protection. This can happen when they need immediate access to cash, particularly to meet financial obligations or offset losses in other investments.
As a result, gold may experience temporary weakness even when broader economic uncertainty remains elevated.
Why Gold Is Struggling Despite Its Safe-Haven Reputation
Gold has historically attracted investors seeking protection against inflation, currency instability, and financial uncertainty. However, its safe-haven status does not guarantee that it will strengthen during every market downturn.
The relationship between gold and financial markets depends on several factors, including investor liquidity needs, interest rate expectations, and confidence in the global economy.
When stock markets experience sudden and widespread losses, investors may prioritize holding cash rather than maintaining positions in precious metals.
This behavior can create additional selling pressure on gold, especially when financial institutions and large investors need to reduce their overall exposure.
Another important factor is the growing appeal of interest-bearing assets.
Unlike government bonds or savings instruments, gold does not provide regular interest income. Its investment appeal depends largely on expectations about economic conditions, currency stability, and its ability to preserve wealth over time.
When investors believe interest rates will remain elevated, the opportunity cost of holding gold increases.
Consequently, some investors may prefer assets that offer regular returns, reducing demand for bullion.
Federal Reserve Interest Rate Outlook Creates Further Challenges
The US Federal Reserve remains a central influence on gold market sentiment.
Investors are increasingly preparing for the possibility that the central bank will maintain a restrictive monetary policy for longer than previously anticipated.
Persistent inflation has encouraged Federal Reserve officials to emphasize the importance of keeping financial conditions tight enough to bring consumer prices under control.
Expectations of additional interest rate increases have strengthened as policymakers express concern about the slow progress toward the central bank’s inflation objective.
Financial markets are also considering the possibility that monetary tightening could extend into 2027.
Such expectations create a challenging environment for gold because higher interest rates generally increase the attractiveness of assets that generate income.
They can also support the US Dollar by making dollar-denominated investments more appealing to international investors.
Since gold is commonly traded in US Dollars, a stronger American currency can make the precious metal more expensive for buyers using other currencies.
This relationship can weaken international demand and add pressure to gold during periods of monetary tightening.
However, the Federal Reserve’s future decisions will depend heavily on incoming economic information, particularly inflation, employment, and consumer spending trends.
Federal Reserve Officials Remain Concerned About Inflation
Recent comments from Federal Reserve policymakers have reinforced expectations that controlling inflation will remain a priority.
Philadelphia Federal Reserve President Anna Paulson indicated that additional monetary tightening may be necessary because inflation continues to remain above the central bank’s desired level.
Her remarks highlighted concerns that existing monetary conditions may not be sufficient to restore price stability.
Chicago Federal Reserve President Austan Goolsbee also expressed doubts about inflation returning to the Federal Reserve’s 2% objective without further policy action.
These statements suggest that policymakers remain cautious about easing their approach before inflation shows convincing signs of improvement.
For gold investors, this creates uncertainty about how long restrictive borrowing conditions might continue.
The longer interest rates remain elevated, the greater the competition gold faces from assets offering regular income.
At the same time, aggressive monetary tightening could eventually weaken economic activity, creating new concerns about growth and financial stability.
This makes the Federal Reserve’s policy outlook especially important for understanding changes in demand for precious metals.
US Treasury Bonds Attract Investors Seeking Stability
Government bonds have benefited from the recent turmoil in global equity markets as investors search for relatively stable investment alternatives.
US Treasury securities are widely viewed as among the safest financial assets because they are backed by the US government.
When uncertainty increases, investors often move money into government bonds to reduce exposure to volatile financial markets.
Stronger demand for Treasury securities generally pushes their yields lower.
The recent decline in US government bond yields reflects this movement toward assets perceived as safer during periods of financial stress.
Lower bond yields can sometimes benefit gold because they reduce the income advantage of holding interest-bearing investments.
However, this potential support has been limited by broader selling pressure and concerns about future Federal Reserve policy.
The situation highlights how several economic forces can influence gold simultaneously.
While declining bond yields may improve the relative appeal of bullion, expectations of additional monetary tightening can discourage investors from increasing their gold exposure.
US Dollar Weakness Offers Some Relief to Gold
The US Dollar has also experienced some weakness as government bond yields decline and investors reassess the economic outlook.
A softer Dollar can provide support to gold by making the precious metal more affordable for international buyers.
This relationship is particularly important because gold is traded globally and demand comes from investors, central banks, jewelry manufacturers, and other buyers across different economies.
When the Dollar weakens, purchasing gold becomes relatively less expensive for buyers holding foreign currencies.
However, the recent improvement in currency conditions has not been enough to reverse the broader pressure affecting bullion.
Investors remain focused on the possibility that the Federal Reserve could continue raising borrowing costs.
If expectations of tighter monetary policy persist, the Dollar may retain support even as financial markets experience periods of uncertainty.
For this reason, changes in the US currency will remain an important factor influencing gold demand.
US Consumer Inflation Expectations Show Signs of Improvement
Recent consumer survey results have provided some encouraging information about inflation expectations in the United States.
The University of Michigan’s final November survey showed that Americans expect inflation to moderate compared with earlier estimates.
Expectations for inflation over the coming year declined noticeably, while longer-term expectations also showed a modest improvement.
Consumer sentiment remained broadly consistent with forecasts, suggesting that households continue to face economic concerns despite some easing in inflation expectations.
These findings are important because consumer expectations can influence spending decisions, wage demands, and broader inflation behavior.
If households believe inflation will gradually decline, it may become easier for the Federal Reserve to achieve its price stability objective.
Nevertheless, improving expectations alone may not be enough to convince policymakers that inflation is sustainably returning to target.
Officials will likely require additional evidence from actual consumer inflation data and other economic reports before changing their policy stance.
For gold, sustained improvement in inflation conditions could eventually reduce concerns about further interest rate increases.
Summary
Gold remains under considerable pressure as global stock market losses, changing investor behavior, and expectations of tighter Federal Reserve policy create a difficult environment for the precious metal.
The widespread equity sell-off has encouraged some investors to raise cash, while concerns about persistent inflation continue to support expectations of restrictive US monetary policy.
Although falling Treasury yields and a softer US Dollar have offered some relief, these developments have not fully offset the broader challenges facing gold.
Looking ahead, the direction of Federal Reserve policy, developments in global equity markets, and upcoming US economic reports will be important in shaping investor confidence.
Gold’s longer-term appeal as a store of value remains relevant, but its near-term performance will depend on how financial markets respond to inflation risks, monetary policy decisions, and changing economic conditions.
EURUSD Faces Pressure as US Inflation Overshadows ECB Policy
The Euro continues to face pressure against the US Dollar, even as recent economic reports from the Eurozone offer several encouraging signs. Stronger inflation figures, improving investor confidence, and weaker US manufacturing data would normally provide some support for the European currency. However, the Euro has struggled to benefit from these developments.
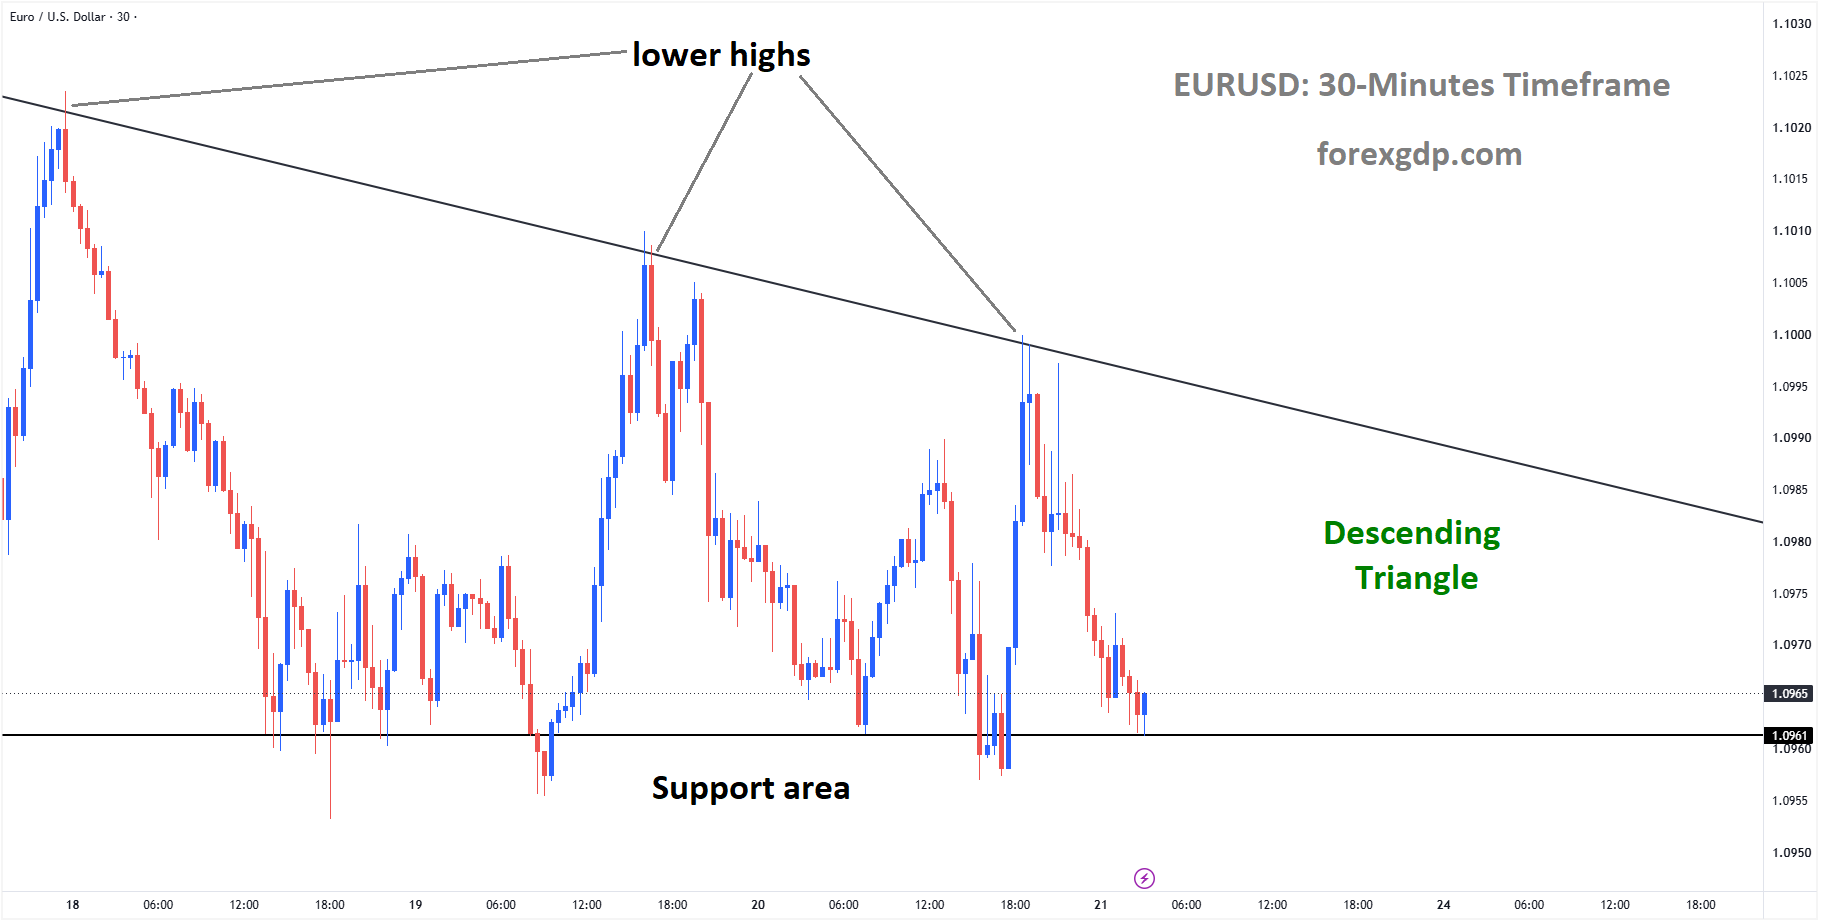
EURUSD reached the support area of the descending triangle pattern
The main reason behind this weakness appears to be the difference between monetary policy expectations in Europe and the United States. Although the European Central Bank (ECB) is widely expected to raise interest rates, investors have already accounted for much of that possibility. Meanwhile, the Federal Reserve remains focused on controlling inflation through a potentially tighter monetary policy.
Political uncertainty in France and concerns about government borrowing costs have also created challenges for the Euro. With several important economic announcements approaching, investors are closely watching whether the European economy can provide enough confidence to improve the currency’s outlook.
Strong Eurozone Inflation Fails to Support the Euro
Recent inflation figures from the Eurozone suggest that underlying price pressures remain stronger than initially expected.
According to Eurostat’s final October report, annual core inflation was revised upward to 2.6%, compared with the earlier estimate of 2.5%. Meanwhile, headline inflation remained unchanged at 4.0%.
Core inflation excludes certain volatile categories, such as food and energy, making it an important measure for central banks when evaluating longer-term inflation trends.
The upward revision indicates that inflation remains a significant concern for European policymakers. It also strengthens expectations that the ECB will maintain a firm approach toward controlling rising consumer prices.
However, the Euro failed to gain meaningful support from the revised figures.
One explanation is that investors had already anticipated a more restrictive monetary policy from the ECB. When financial markets strongly expect a particular decision, even supportive economic news may have little additional influence on currency sentiment.
This situation highlights an important feature of currency markets: economic data does not always produce the reaction that might initially seem logical. Expectations about future developments can matter just as much as the actual figures.
Improving German Economic Sentiment Offers Encouragement
Another positive development came from Germany’s ZEW economic sentiment survey.
The survey recorded a reading of 26.5, comfortably exceeding the expected figure of 19.1. This improvement suggests that financial analysts and institutional investors have become more optimistic about Germany’s economic prospects.
Germany plays a central role in the Eurozone economy because of its large manufacturing sector, international trade relationships, and significant contribution to regional economic activity.
An improvement in German economic confidence can therefore influence expectations for the wider European economy.
The stronger ZEW reading suggests that investors see opportunities for economic conditions to improve in the coming months. Nevertheless, optimism about future growth does not necessarily mean that businesses and households are already experiencing a meaningful recovery.
European companies continue to face challenges involving financing costs, international competition, and uncertain demand.
As a result, the positive sentiment report was not enough to change the broader cautious attitude toward the Euro.
ECB Interest Rate Expectations Remain a Major Influence

The European Central Bank is expected to play a decisive role in shaping the Euro’s near-term outlook.
Investors have assigned a probability of more than 90% to an ECB interest rate increase at its December 17 meeting. Such a decision would raise the deposit rate from 2.50% to 2.75%.
Higher interest rates can make a currency more attractive because investors may receive better returns from assets denominated in that currency.
However, the relationship between interest rates and currency strength is not always straightforward.
When an expected policy decision is already widely anticipated, its ability to influence investor behavior may be limited. This helps explain why expectations of an ECB increase have not generated stronger enthusiasm for the Euro.
The central bank also faces a difficult balancing act.
Keeping monetary policy restrictive can help reduce inflation, but higher borrowing costs may place additional pressure on businesses, consumers, and governments.
European policymakers must therefore consider whether further action against inflation could weaken economic activity or create financial difficulties in vulnerable member countries.
Investors will be particularly interested in the ECB’s explanation of its policy decisions and its assessment of future inflation risks.
Federal Reserve Policy Keeps the US Dollar Attractive
While European policymakers consider their next steps, the Federal Reserve remains another major influence on the currency relationship.
Minutes from the Fed’s October meeting revealed that almost all officials expected additional interest rate increases. Some policymakers were also willing to consider a larger increase at the December meeting.
Federal Reserve Governor Christopher Waller separately supported a more substantial policy adjustment.
These comments suggest that US policymakers remain concerned about inflation and are prepared to maintain restrictive financial conditions.
At the October meeting, the Federal Reserve voted 10-2 to leave interest rates unchanged. Both dissenting officials favored an increase.
The decision illustrates that policymakers disagree primarily about the timing and speed of further tightening rather than the importance of addressing inflation.
The Federal Reserve’s interest rate range of 3.75% to 4.00% also remains higher than the ECB’s deposit rate.
This difference can encourage international investors to favor US assets, particularly when the outlook for European economic growth remains uncertain.
Consequently, the Dollar may continue attracting interest even when individual US economic reports disappoint.
Weak US Manufacturing Data Creates Mixed Economic Signals
Recent US economic indicators have raised questions about the strength of the country’s industrial sector.
The Empire State Manufacturing Survey and Philadelphia Fed Manufacturing Survey both delivered results substantially weaker than economists had expected.
Additionally, US industrial production declined by 0.4% in October, suggesting reduced activity across important areas of the economy.
Weekly unemployment claims also increased to 203,000.
Together, these figures indicate that some parts of the US economy may be experiencing slower momentum.
Manufacturing surveys are particularly useful because they provide early insight into business conditions, including production activity, employment expectations, and demand.
However, disappointing manufacturing results do not automatically mean that the entire economy is weakening significantly.
The Federal Reserve must assess a much broader range of information, including consumer spending, employment conditions, wage growth, and inflation.
For currency investors, the key question is whether weaker economic activity will eventually persuade the Fed to reconsider its approach to interest rates.
Until policymakers signal a meaningful change in direction, disappointing economic reports alone may not substantially reduce confidence in the Dollar.
France’s Budget Challenges Add Pressure to the Eurozone
Political and fiscal developments in France have introduced another source of uncertainty for the European currency.
France continues to face disagreements over its 2027 national budget, with lawmakers struggling to resolve important questions about government spending and public finances.
Concerns about the country’s fiscal position have increased attention on the additional borrowing costs faced by the French government compared with Germany.
Investors generally regard German government debt as a relatively secure benchmark within the Eurozone.
When concerns about another country’s finances increase, investors may demand greater compensation for holding its government debt.
Earlier in November, the difference between French and German government borrowing costs reached levels associated with previous periods of serious Eurozone financial stress.
Bank of France Governor Moulin also warned about France’s budget difficulties while emphasizing that the country’s circumstances differ significantly from those experienced by Greece during its debt crisis.
These developments matter because higher ECB interest rates could make government borrowing more expensive.
Although tighter monetary policy may support the Euro through improved returns, it can simultaneously create additional challenges for countries already facing fiscal pressure.
This combination makes the ECB’s decisions especially complicated.
Upcoming Economic Events Could Shape Currency Sentiment
Several important economic releases and policy developments are approaching, offering investors further opportunities to assess conditions on both sides of the Atlantic.
The Eurozone Purchasing Managers’ Index reports, scheduled for Monday, will provide insight into activity across manufacturing and services.
These surveys can help determine whether European businesses are experiencing improving demand or continuing economic difficulties.
Wednesday’s US core Personal Consumption Expenditures report will be another major event.
The core PCE measure is particularly important because the Federal Reserve uses it to evaluate underlying inflation pressures.
A stronger-than-expected reading could reinforce expectations of restrictive US monetary policy, while weaker inflation may encourage discussion about a less aggressive approach.
On Thursday, the publication of ECB meeting accounts will offer additional information about policymakers’ concerns, disagreements, and future priorities.
Investors will also monitor the European Union leaders’ meeting on November 26 and 27, especially as France’s budget uncertainty remains unresolved.
Taken together, these developments could provide a clearer picture of how monetary policy and economic conditions may evolve.
Final Summary
The Euro’s recent weakness reflects more than the latest economic statistics. Although Eurozone inflation and German investor sentiment have exceeded expectations, these improvements have not been sufficient to overcome broader concerns.
Expectations of an ECB interest rate increase are already firmly established, limiting the impact of supportive European data. At the same time, the Federal Reserve’s commitment to controlling inflation continues to strengthen the Dollar’s appeal.
France’s fiscal challenges add another layer of uncertainty, particularly because higher European interest rates could increase government financing pressures.
Looking ahead, Eurozone business activity reports, US inflation figures, and ECB policy accounts will be important for understanding the next phase of monetary policy.
For the Euro to regain stronger investor confidence, encouraging economic reports may need to be accompanied by clearer signs of sustainable growth, financial stability, and a more favorable balance between European and US monetary policy expectations.
GBPUSD Faces Fresh Pressure as UK Economic Data Raises Policy Uncertainty
The British Pound is facing renewed pressure against the US Dollar as weaker-than-expected economic figures from the United Kingdom change expectations for future interest rate decisions. Recent reports on inflation and wage growth suggest that price pressures in Britain may be easing, giving the Bank of England (BoE) more room to reconsider its monetary policy plans.
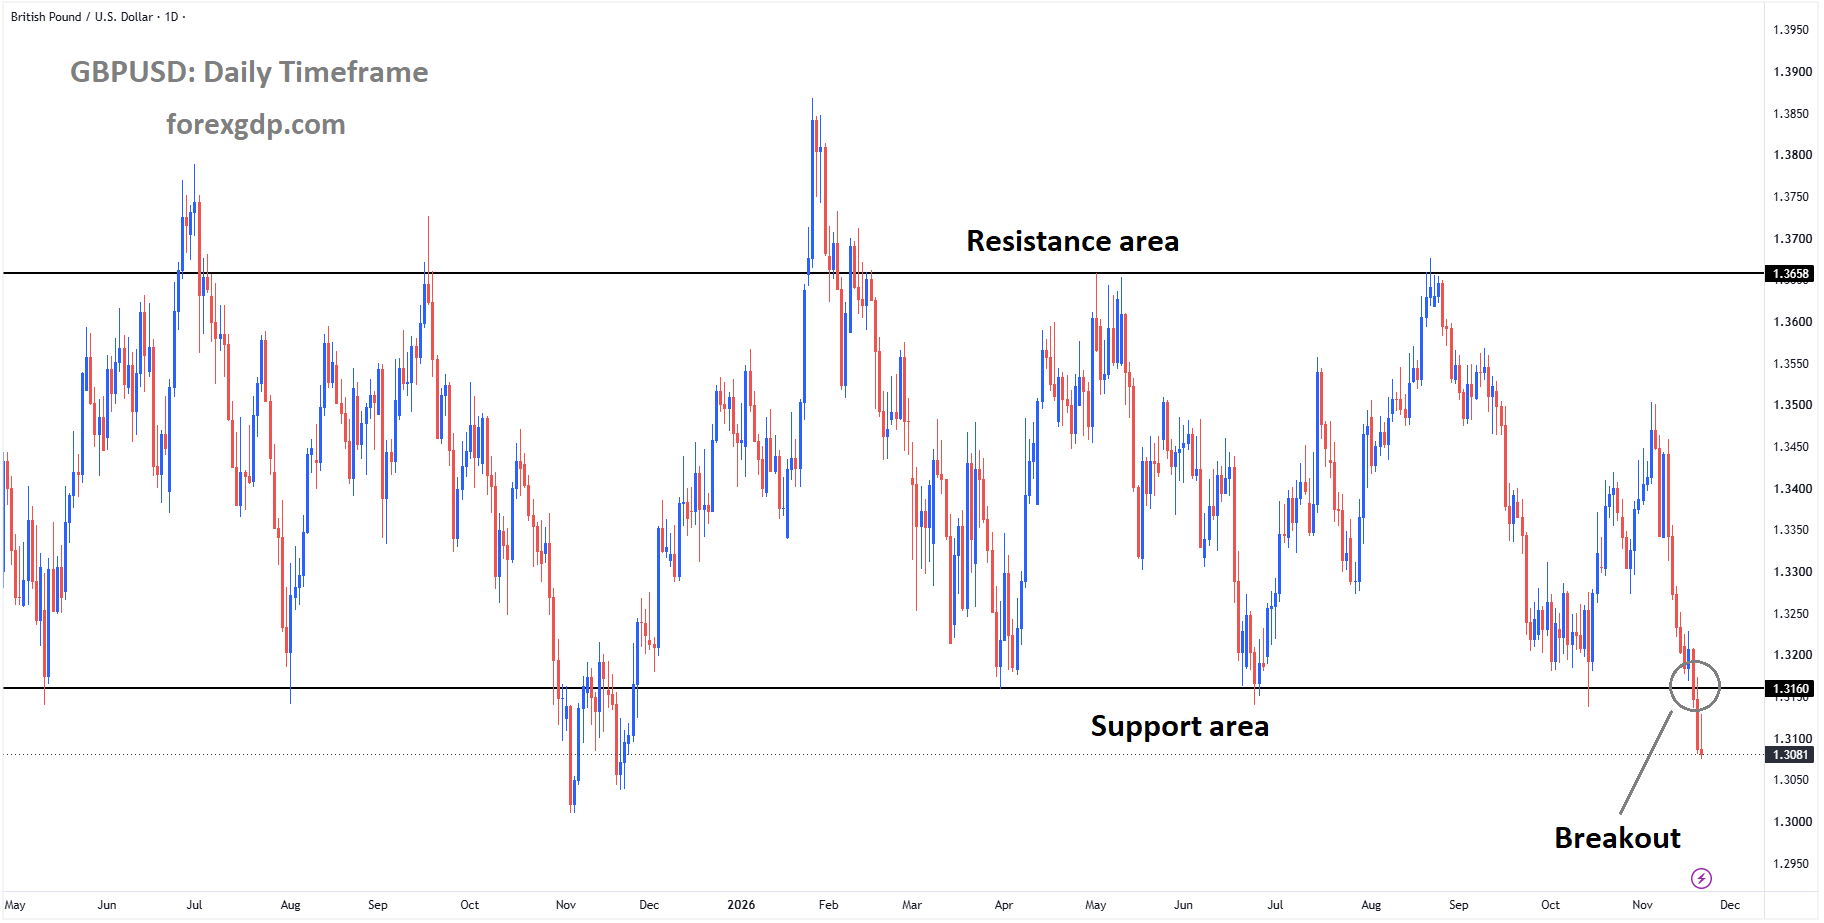
GBPUSD broken the box pattern to the downside
While slowing inflation offers welcome relief to households struggling with living costs, it also creates uncertainty about whether the central bank will move ahead with another interest rate increase.
Meanwhile, the US Federal Reserve faces its own difficult decisions as policymakers debate the direction of American monetary policy. With important economic reports approaching in both countries, the GBP/USD outlook remains closely tied to central bank expectations, consumer spending, and broader economic conditions.
UK Inflation Slows as Household Cost Pressures Ease
The latest UK inflation report delivered encouraging news for consumers. Annual Consumer Price Index (CPI) inflation reached 3.6%, slightly below the expected 3.7%. Core inflation, which excludes more volatile categories such as food and energy, remained unchanged at 2.8%.
Although the difference between the actual inflation figure and economists’ expectations was relatively small, it carried important implications for monetary policy.
Lower inflation suggests that the rapid increases in everyday living costs may be gradually losing momentum. This can help households manage essential expenses and improve their ability to plan future spending.
However, inflation remains above the Bank of England’s 2% target, meaning policymakers cannot assume that the challenge of controlling prices has ended.
The latest figures also strengthen the argument for a cautious approach to interest rate decisions. If inflation continues to moderate, the central bank may feel less pressure to tighten monetary conditions further.
For the British Pound, this creates a complicated situation. Economic improvements that benefit consumers do not always provide immediate support for the currency, particularly when they reduce expectations of higher interest rates.
Slower UK Wage Growth Adds to Monetary Policy Uncertainty
Britain’s labour market figures have added another layer of uncertainty to the economic outlook.
Average earnings excluding bonuses increased by 3.5% during the three months ending in September. This was slightly below the anticipated 3.6% increase and represented a slowdown from the previous reading of 3.7%.
At the same time, the claimant count increased by 33,200, exceeding the expected rise of 28,100. This suggests that more people were seeking unemployment-related benefits than economists had predicted.
However, the unemployment rate declined to 4.6%, compared with expectations of 4.7%.
These mixed results suggest that the labour market is changing rather than experiencing a clear deterioration.
Why Wage Growth Matters to the Bank of England
Wage growth is an important consideration for central banks because higher earnings can support household spending and contribute to inflation.
When businesses face rising labour costs, they may increase the prices of their goods and services to protect profitability. This can make inflation more persistent, especially in service-based industries.
Slower wage growth may therefore reduce some of the pressure on the Bank of England to increase borrowing costs.
For workers, however, the benefits depend on whether wages are growing faster than consumer prices. Even when inflation slows, households can continue to experience financial pressure if their earnings fail to keep pace with living expenses.
The latest wage figures suggest that policymakers will need to balance inflation concerns against the risk of placing unnecessary pressure on economic activity.
Bank of England Faces a Difficult Interest Rate Decision
The Bank of England’s next policy decision has become an important focus for investors following the latest inflation and employment reports.
With the Bank Rate at 4%, policymakers must decide whether additional tightening is necessary to bring inflation sustainably back toward the official target.
Earlier economic projections suggested that inflation could reach approximately 5% by the middle of 2027. However, Governor Andrew Bailey subsequently indicated that inflation might peak below that estimate.
His comments introduced additional uncertainty about the strength and persistence of future price pressures.
BoE Deputy Governor Clare Lombardelli has also avoided committing to a specific timetable for further monetary policy changes, leaving different meeting dates open for consideration.
Chief Economist Huw Pill has taken a more cautious position on inflation risks. He previously argued that the central bank may have waited too long to respond and suggested that additional action could eventually become necessary.
These differences highlight the challenge facing the Monetary Policy Committee.
Some officials remain concerned that inflation could stay elevated for longer than expected. Others may place greater emphasis on slowing wage growth and the possibility of weaker economic activity.
The final decision will depend on how policymakers interpret the combined evidence rather than any single economic report.
UK Retail Sales Provide Some Encouragement for the Economy
Despite weaker inflation and wage figures, the latest retail sales report offered a more positive signal about British consumer activity.
Retail sales increased by 0.7% in October, outperforming expectations for no monthly growth.
This improvement suggests that consumers remained willing to spend despite ongoing financial pressures.
Stronger retail activity can support economic growth by helping businesses maintain revenue, employment, and investment plans.
It may also indicate that some households are becoming more confident about their financial circumstances as inflation gradually moderates.
However, one positive retail sales report does not necessarily establish a lasting recovery.
Consumer confidence, borrowing costs, employment conditions, and household disposable income will continue to influence spending decisions.
For the Bank of England, stronger retail sales provide evidence that domestic demand has not completely weakened. Nevertheless, policymakers will need to determine whether this improvement can continue alongside slower wage growth.
Federal Reserve Policy Adds Another Layer of Uncertainty
Developments in the United States are equally important for the broader GBP/USD outlook.
The Federal Reserve has been debating the appropriate direction of monetary policy as officials assess inflation risks and economic resilience.
Minutes from its October meeting indicated that many policymakers expected additional interest rate increases to remain necessary.
Federal Reserve Governor Christopher Waller also supported a larger policy adjustment, reflecting concerns about the need to address inflation effectively.
However, changing financial conditions have complicated expectations surrounding the Fed’s next decision.
Uncertainty in US equity markets and differences among central bank officials have encouraged investors to reassess the likelihood of further tightening.
The relationship between British and American interest rates remains particularly important.
When investors expect US monetary policy to become more restrictive than UK policy, the Dollar may become more attractive. Conversely, expectations of a more cautious Federal Reserve can reduce some of that advantage.
The outcome will depend on upcoming economic evidence and how both central banks respond to changing conditions.
Upcoming UK PMI Reports Could Shape Economic Expectations
The next set of UK Purchasing Managers’ Index (PMI) reports will provide another important assessment of business conditions.
The surveys cover activity across major parts of the economy and offer insight into demand, employment, business confidence, and operating conditions.
Previous readings showed the composite PMI at 52.9 and the services PMI at 52.8, indicating expansion in business activity.
Fresh results will help determine whether the economy is maintaining momentum or beginning to lose strength.
A stronger performance could reassure policymakers that businesses remain resilient despite inflation concerns and slower earnings growth.
Weaker readings, however, may increase concerns about economic growth and strengthen arguments for a more cautious monetary policy approach.
Comments from BoE Chief Economist Huw Pill will also attract attention, particularly regarding his assessment of inflation persistence and the need for future policy action.
US Core PCE Inflation Remains a Key Economic Event
Another major development will be the release of the US core Personal Consumption Expenditures (PCE) inflation report.
This measure is closely followed by the Federal Reserve because it provides important information about underlying consumer price pressures.
The upcoming report was expected to show monthly growth of 0.3% and annual inflation of 3.2%, compared with the previous annual reading of 3.1%.
An increase in underlying inflation could strengthen the argument for maintaining restrictive monetary policy.
Alternatively, softer inflation data may encourage policymakers to consider whether existing measures are sufficient to control price pressures.
The report will therefore play an important role in shaping expectations for the Federal Reserve’s next decision.
Final Summary
The GBP/USD outlook is being shaped by a combination of slowing UK inflation, weaker wage growth, resilient consumer spending, and uncertainty surrounding central bank policy.
Recent British economic figures offer some encouragement for households but have also raised questions about the need for further Bank of England tightening.
Meanwhile, the Federal Reserve continues to assess inflation developments and the strength of the US economy.
Upcoming PMI surveys, central bank speeches, and US inflation figures will provide valuable insight into the direction of monetary policy.
Ultimately, the British Pound’s broader outlook will depend on whether the UK economy can maintain steady growth while inflation continues to ease, and how that performance compares with developments in the United States.
USDJPY Faces Heavy Pressure as Broad Market Turmoil Boosts Yen Strength
The Japanese Yen (JPY) has emerged as one of the strongest major currencies as a widespread sell-off in global stock markets pushes investors toward safer assets. Growing uncertainty across international financial markets has increased demand for the Yen, helping the currency outperform its major counterparts despite weaker-than-expected inflation figures from Japan.
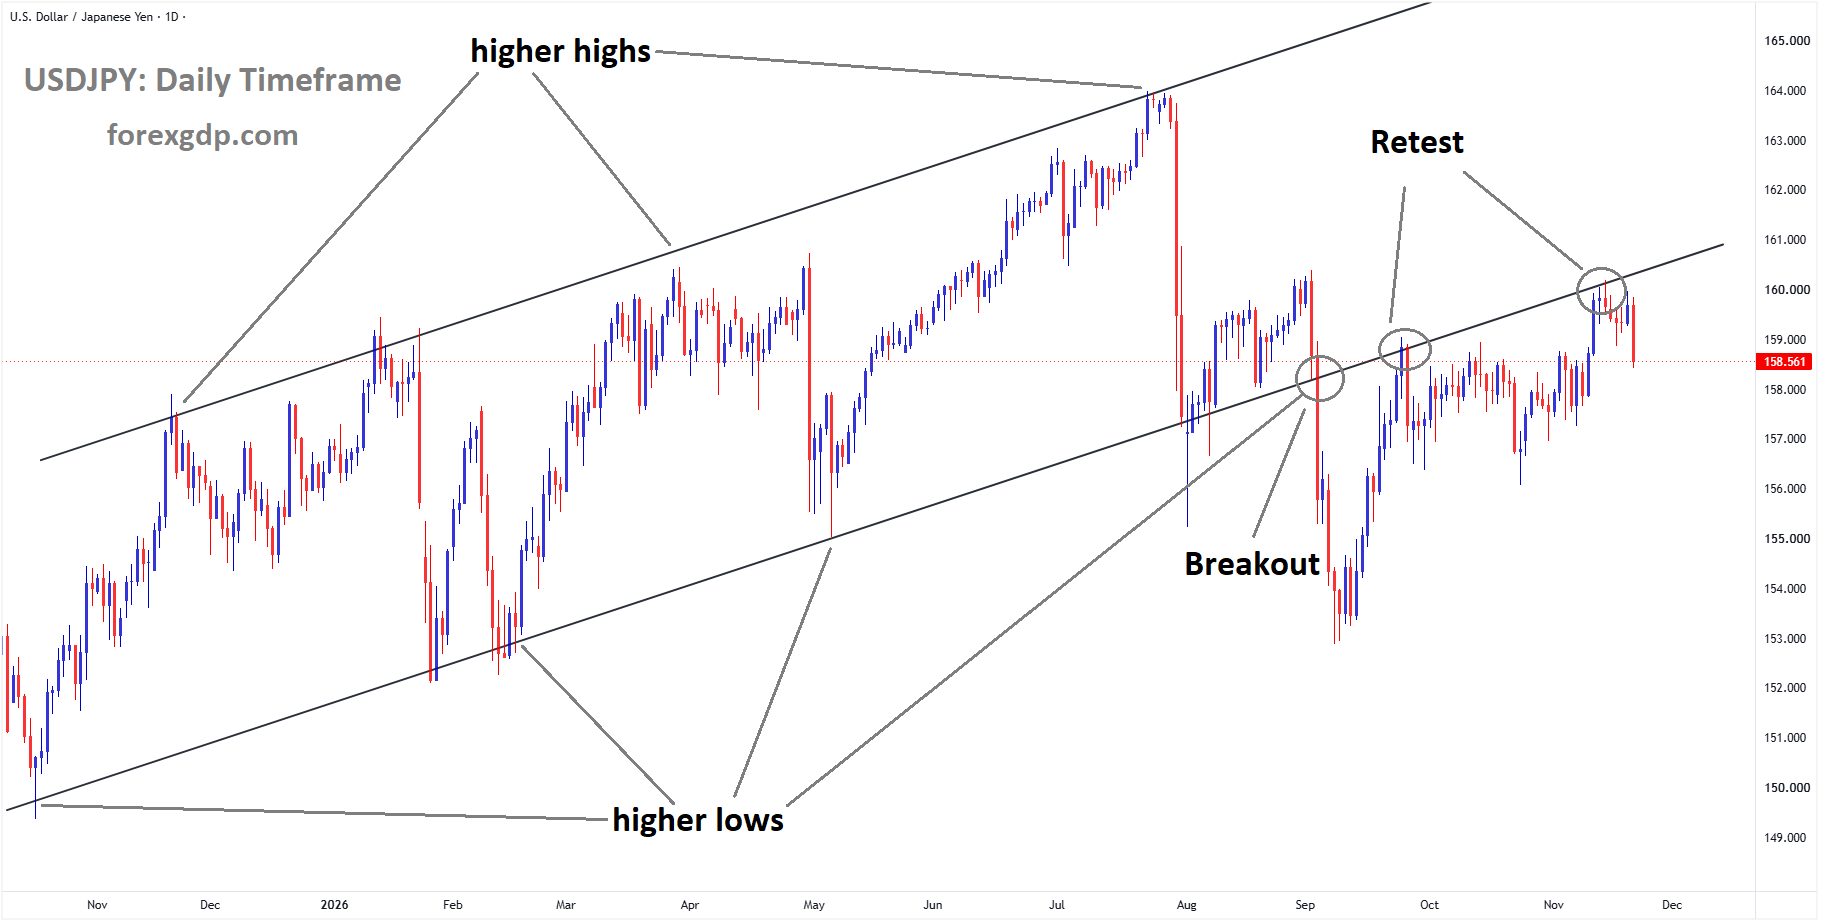
USDJPY reached the retest area of the broken ascending channel
At the same time, the US Dollar (USD) is facing pressure as investors reassess their exposure to riskier assets. The combination of a stronger Japanese Yen and a softer US Dollar has weighed on the USD/JPY currency pair.
However, expectations that the US Federal Reserve will maintain a firm approach to monetary policy could prevent the Yen from strengthening too aggressively against the Dollar. This creates a complicated environment in which global risk sentiment and central bank expectations are pulling currencies in different directions.
Japanese Yen Benefits From Rising Global Market Uncertainty
The Japanese Yen has traditionally been viewed as a safe-haven currency during periods of financial instability. When investors become concerned about economic conditions, geopolitical developments, or falling stock markets, they often reduce their exposure to riskier investments and seek assets considered more stable.
This behavior has become particularly noticeable as global equity markets experience significant selling pressure.
The latest decline in international stocks has encouraged investors to reconsider their investment strategies. Concerns about the outlook for technology companies, economic growth, and broader financial stability have contributed to a cautious mood.
As investors move away from riskier assets, demand for the Japanese Yen has increased. This has allowed the currency to strengthen even though recent economic figures from Japan have not been particularly encouraging.
The Yen’s performance highlights an important feature of currency markets: investor confidence and global financial conditions can sometimes have a greater immediate influence on a currency than domestic economic reports.
Global Stock Market Sell-Off Increases Demand for Safer Assets
Financial markets around the world have faced heavy selling pressure, with major stock indexes across the United States, Asia, and Europe experiencing substantial declines.
In the United States, technology-related shares have been among the areas attracting significant attention. Investors are increasingly questioning whether the rapid growth and high expectations surrounding artificial intelligence companies can continue without interruption.
The stock market debut of artificial intelligence company Anthropic failed to ease these concerns. Instead, uncertainty surrounding the broader AI investment sector continued to weigh on market sentiment.
The weakness has extended beyond technology stocks, affecting companies across several industries. This suggests that investor concerns are becoming more widespread rather than remaining limited to one sector.
Asian markets have also experienced considerable pressure. Japan’s Nikkei 225 and South Korea’s Kospi have suffered sharp declines, reflecting the global nature of the sell-off.
European equities have followed a similar direction, showing that nervousness among investors is not restricted to a particular region.
When stock markets decline across several major economies at the same time, investors often become more defensive. This change in behavior can benefit currencies such as the Japanese Yen, which have historically attracted demand during uncertain periods.
Softer Japanese Inflation Fails to Weaken the Yen
One of the more interesting developments is the Yen’s ability to strengthen despite softer-than-expected inflation data from Japan.
Inflation plays an important role in shaping the monetary policy decisions of the Bank of Japan (BoJ). When consumer prices rise steadily, policymakers may have greater confidence in maintaining or increasing interest rates.
On the other hand, weaker inflation can reduce the urgency for tighter monetary policy, especially if economic growth is also showing signs of weakness.
Under normal circumstances, disappointing inflation figures could place pressure on the Japanese Yen because they may lead investors to expect a more cautious approach from the Bank of Japan.
However, the current market environment has created a different situation.
Investors appear to be placing greater importance on protecting their investments from global financial uncertainty than on the immediate implications of Japan’s inflation figures.
As a result, safe-haven demand has provided support for the Yen despite economic data that might otherwise have weakened the currency.
This development shows how quickly the main drivers of currency movements can change when financial markets become unsettled.
US Dollar Faces Pressure as Investor Sentiment Weakens
The US Dollar has also been affected by the changing mood in global markets.
Although the Dollar is widely considered a safe-haven currency, its performance depends on several factors, including US economic expectations, Federal Reserve policy, and international investment flows.
During the latest period of market uncertainty, the Dollar has softened against the Japanese Yen.
One possible reason is that investors are adjusting positions after an extended period of Dollar strength. When financial markets experience sudden stress, investors may close existing trades and move funds into currencies that are traditionally associated with lower-risk strategies.
The Japanese Yen can benefit from this process, particularly when investors reduce positions financed through borrowing in Yen.
At the same time, uncertainty surrounding US equities has encouraged market participants to reconsider their expectations for the American economy.
Nevertheless, weakness in the Dollar does not necessarily indicate a lasting change in its broader outlook.
The Federal Reserve’s policy direction remains an important factor that could influence how the Dollar performs in the coming weeks.
Federal Reserve Expectations Could Limit Further Yen Strength
Despite the Japanese Yen’s recent strength, expectations surrounding the US Federal Reserve may provide some support for the Dollar.
A hawkish Federal Reserve generally refers to a central bank that is focused on controlling inflation and is willing to maintain relatively restrictive monetary conditions.
If Federal Reserve officials remain concerned about inflation, they may be reluctant to ease monetary policy quickly, even when financial markets become unsettled.
Such an approach can make the US Dollar more attractive to investors seeking returns from interest-bearing assets.
The difference between US and Japanese interest rates is particularly important for the USD/JPY currency pair.
Japan has maintained a different monetary policy environment from the United States for many years. Although the Bank of Japan has been moving away from its earlier ultra-loose policies, the direction and speed of future changes remain important considerations.
If US interest rates remain comparatively elevated, the Dollar may continue to attract demand from investors.
This could limit the extent of the Yen’s gains, even if safe-haven buying remains strong.
Consequently, the relationship between the Federal Reserve and the Bank of Japan will remain central to the currency outlook.
Bank of Japan Policy Remains an Important Factor

The Bank of Japan faces a challenging balancing act as it considers inflation, wage growth, domestic demand, and international financial conditions.
Softer inflation could encourage policymakers to proceed carefully with any additional monetary tightening.
However, the central bank must also consider whether wage increases and broader economic developments can support sustainable inflation over time.
A stronger Yen can create additional complications for Japan’s economy.
While currency appreciation may help reduce the cost of imported goods and energy, it can also affect the overseas earnings of Japanese exporters.
This makes the Yen’s strength a mixed development for the Japanese economy.
For investors, upcoming statements from Bank of Japan officials will be important in understanding whether policymakers remain confident about the country’s economic outlook.
Any change in the central bank’s policy expectations could influence the Yen once global financial markets become more stable.
What Could Influence USD/JPY in the Coming Days?
Several developments could shape the direction of USD/JPY as investors respond to the latest financial market uncertainty.
Global stock market sentiment will likely remain one of the most important influences. Continued weakness in international equities could encourage further demand for the Japanese Yen.
US economic data will also deserve attention, particularly reports related to inflation, employment, and consumer spending. These figures can influence expectations about future Federal Reserve decisions.
Meanwhile, Japanese economic releases and comments from Bank of Japan officials may help clarify the country’s monetary policy outlook.
Another important consideration is whether concerns surrounding artificial intelligence investments continue to affect global confidence.
If investors regain confidence and return to riskier assets, demand for safe-haven currencies could weaken.
However, if uncertainty persists, the Japanese Yen may continue attracting interest from investors seeking stability.
The balance between these developments will determine whether safe-haven demand or interest rate expectations have the stronger influence on the currency pair.
Summary
The Japanese Yen has strengthened against major currencies as a widespread global stock market sell-off encourages investors to seek safer assets. Despite softer Japanese inflation data, demand for the Yen has remained strong because financial market uncertainty has become the dominant concern.
Weakness in US equities, worries surrounding artificial intelligence investments, and declining investor confidence across Asia and Europe have contributed to the cautious environment.
However, expectations that the Federal Reserve will maintain a restrictive monetary policy stance could provide support for the US Dollar and limit further Yen appreciation.
Looking ahead, the direction of USD/JPY will depend largely on global risk sentiment, economic developments in Japan and the United States, and the monetary policy outlook of both central banks.
For now, the Japanese Yen’s performance demonstrates how strongly investor behavior can influence currency markets during periods of global financial uncertainty.
USDCAD Pulls Back From Multi-Month Peak as Canada’s Spending Strength Lifts the Loonie
The USD/CAD currency pair has moved slightly lower after reaching its highest level in 19 months, as stronger-than-expected Canadian retail sales and a softer US Dollar provided some support for the Canadian Dollar. Despite the recent decline, the broader outlook remains influenced by differences in monetary policy between the Federal Reserve (Fed) and the Bank of Canada (BoC).
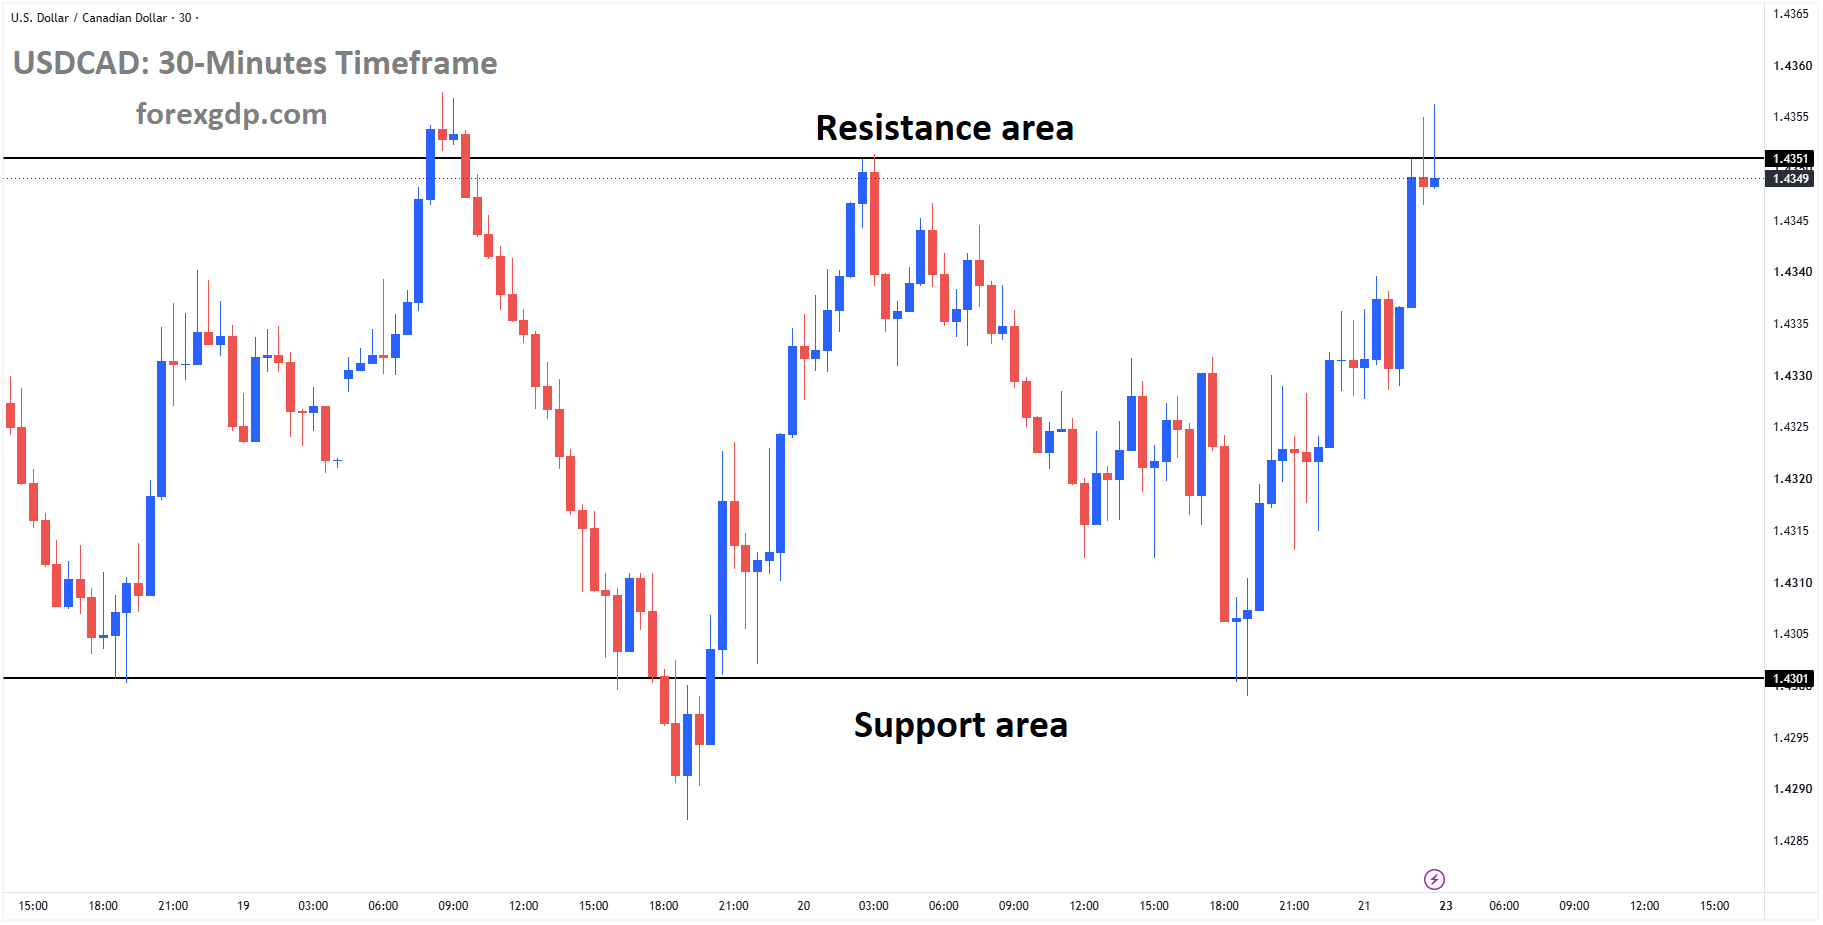
USDCAD reached the resistance area of the box pattern
The currency pair had recorded gains in seven of the previous eight trading sessions before losing some momentum on Friday. However, the pullback has been relatively limited, suggesting that the factors supporting the US Dollar have not completely disappeared.
Investors are now turning their attention to upcoming economic reports and central bank commentary, which could provide fresh insights into the direction of monetary policy in both countries.
Canadian Dollar Finds Support From Stronger Retail Sales
Canada’s latest retail sales report offered some encouraging news for the domestic economy. According to Statistics Canada, retail sales increased by 0.8% in September, exceeding economists’ expectations of a 0.7% rise.
Although the difference between the actual figure and the forecast was small, the report showed that Canadian consumers continued spending despite economic uncertainty and changing borrowing conditions.
Retail sales excluding automobiles increased by 1%, indicating that spending growth extended beyond vehicle purchases. This broader improvement helped strengthen confidence in consumer activity and provided temporary support for the Canadian Dollar, commonly known as the Loonie.
Gasoline stations were among the strongest contributors to September’s retail sales growth, recording a 6.9% increase. This improvement played an important role in lifting the overall sales figure.
However, the report also revealed that retail sales volumes increased by just 0.1%. This suggests that much of the growth in the value of sales did not translate into a similarly strong increase in the quantity of goods purchased.
The distinction matters because higher sales values do not always indicate stronger consumer demand. Changes in prices can influence total spending figures even when the amount of merchandise sold changes very little.
October Retail Sales Estimate Raises Concerns About Consumer Spending
While September’s retail sales figures exceeded expectations, the outlook for October appears less encouraging.
Statistics Canada’s preliminary estimate suggests that retail sales declined by 1.5% in October. If confirmed, this would represent a notable reversal from the previous month’s improvement.
The early estimate raises questions about the strength of Canadian household spending and whether consumers can maintain their purchasing activity in the coming months.
Consumer spending is an important part of Canada’s economy. When households purchase more goods and services, businesses generally benefit from stronger demand. However, a slowdown in spending can affect company revenues, hiring decisions, and overall economic growth.
The expected October decline also highlights the uneven nature of Canada’s economic recovery. A positive report for one month does not necessarily mean that consumer activity will continue improving.
It is important to remember that preliminary retail sales estimates can change when more complete information becomes available. Nevertheless, the early October reading may encourage investors and policymakers to remain cautious about the strength of domestic demand.
For the Canadian Dollar, this creates a mixed economic picture. September’s better-than-expected performance offers some encouragement, but the possibility of weaker spending in October limits the positive impact.
Federal Reserve and Bank of Canada Policies Remain in Focus
Monetary policy continues to play a central role in shaping expectations for USD/CAD.
The Federal Reserve’s policy interest rate stands within a range of 3.75% to 4.00%, while the Bank of Canada’s policy rate stands at 2.50% following its October 28 decision.
Both central banks are scheduled to announce their next interest rate decisions on December 9, making the upcoming meetings particularly important for investors.
Market expectations described in the latest policy outlook point toward another interest rate increase from the Federal Reserve. A quarter-percentage-point increase has been widely anticipated, while some Fed officials have discussed the possibility of a larger adjustment.
The difference between US and Canadian interest rates can influence the relative attractiveness of their currencies.
When US interest rates are higher, certain US Dollar-denominated investments may offer more attractive returns than comparable Canadian assets. This can encourage demand for the American currency.
However, interest rate differences are only one part of the broader picture. Economic growth, inflation, employment conditions, and expectations about future central bank decisions also influence currency demand.
The Bank of Canada faces its own challenges as policymakers assess consumer spending, economic activity, and inflation developments.
If Canadian economic conditions weaken, the central bank may need to balance concerns about growth against its responsibility to maintain price stability.
Interest Rate Differences Influence Currency Sentiment
The difference between US and Canadian government bond yields has also attracted attention.
During November, the gap between two-year government bond yields in the two countries widened by approximately one-fifth of a percentage point.
This development reflects changing expectations about the future direction of interest rates and monetary policy.
Government bond yields often respond to expectations about central bank decisions. When investors anticipate tighter monetary conditions in one country compared with another, the difference between their bond yields may increase.
A wider gap favoring US government bonds can strengthen interest in US Dollar assets, particularly when investors expect American monetary policy to remain relatively restrictive.
For Canada, weaker consumer spending expectations and uncertainty surrounding economic growth could influence how investors assess the Bank of Canada’s future decisions.
These differences help explain why the US Dollar has remained relatively resilient against the Canadian Dollar despite occasional improvements in Canadian economic data.
Weak Crude Oil Sentiment Adds Pressure on the Canadian Dollar
Developments in the energy market are another important factor affecting Canada’s currency.
Crude oil has been heading toward a third consecutive weekly decline, creating additional challenges for the Canadian Dollar.
Canada is a major oil-producing and exporting country, making energy sector performance particularly relevant to its economy.
When crude oil demand and industry conditions are strong, Canadian energy companies may benefit from increased export revenues and investment activity. These developments can support economic growth and improve sentiment toward the Canadian Dollar.
Conversely, prolonged weakness in the oil market can reduce optimism about Canada’s energy sector and its contribution to the wider economy.
The relationship between oil and the Canadian Dollar is not always consistent. Currency movements depend on several factors, including global economic conditions, central bank policies, and international demand for financial assets.
Still, weaker energy market sentiment can remove an important source of support for the Loonie.
With uncertainty surrounding consumer spending and monetary policy already influencing the currency, softer crude oil conditions add another layer of concern.
Upcoming Economic Events Could Shape the USD/CAD Outlook
Investors are preparing for several important developments that could influence expectations for both currencies.
Bank of Canada Governor Tiff Macklem is scheduled to speak on Tuesday. His comments may offer additional insight into how Canadian policymakers view economic conditions and the future direction of interest rates.
Investors will be particularly interested in any discussion of consumer spending, inflation, and the overall health of Canada’s economy.
On Wednesday, attention will shift toward the United States, where the core Personal Consumption Expenditures (PCE) inflation report and Gross Domestic Product (GDP) figures are due.
The core PCE report is especially important because it is a closely watched measure of underlying inflation used by the Federal Reserve when assessing monetary policy.
A stronger-than-expected inflation reading could reinforce expectations that the Fed will maintain a restrictive policy approach. Softer inflation, meanwhile, could encourage a reassessment of future interest rate decisions.
US GDP data will provide another important perspective by showing how the American economy is performing.
Together, these reports could influence expectations for the December Federal Reserve meeting and affect broader sentiment toward the US Dollar.
Summary
USD/CAD has experienced a modest retreat after reaching a 19-month high, supported by stronger Canadian retail sales and a temporary weakening of the US Dollar.
However, the broader economic picture remains uncertain. Canada’s September retail sales exceeded expectations, but the preliminary October estimate points toward a significant slowdown in consumer spending.
At the same time, differences between Federal Reserve and Bank of Canada monetary policies continue to influence currency sentiment. Weakness in crude oil adds further pressure on the Canadian Dollar.
The upcoming remarks from Bank of Canada Governor Tiff Macklem, alongside US core PCE inflation and GDP reports, will provide important information about economic conditions and potential central bank decisions.
For now, the outlook for USD/CAD remains closely connected to monetary policy expectations, consumer spending trends, and developments in the energy market.
USDCHF Struggles to Hold Gains as Artificial Intelligence Stocks Face Heavy Selling
The Swiss Franc has gained strength against the US Dollar as growing concerns about a possible artificial intelligence (AI) bubble create uncertainty across global financial markets. Investors are becoming increasingly cautious about the high valuations of technology companies, particularly those closely connected to the rapid growth of AI.
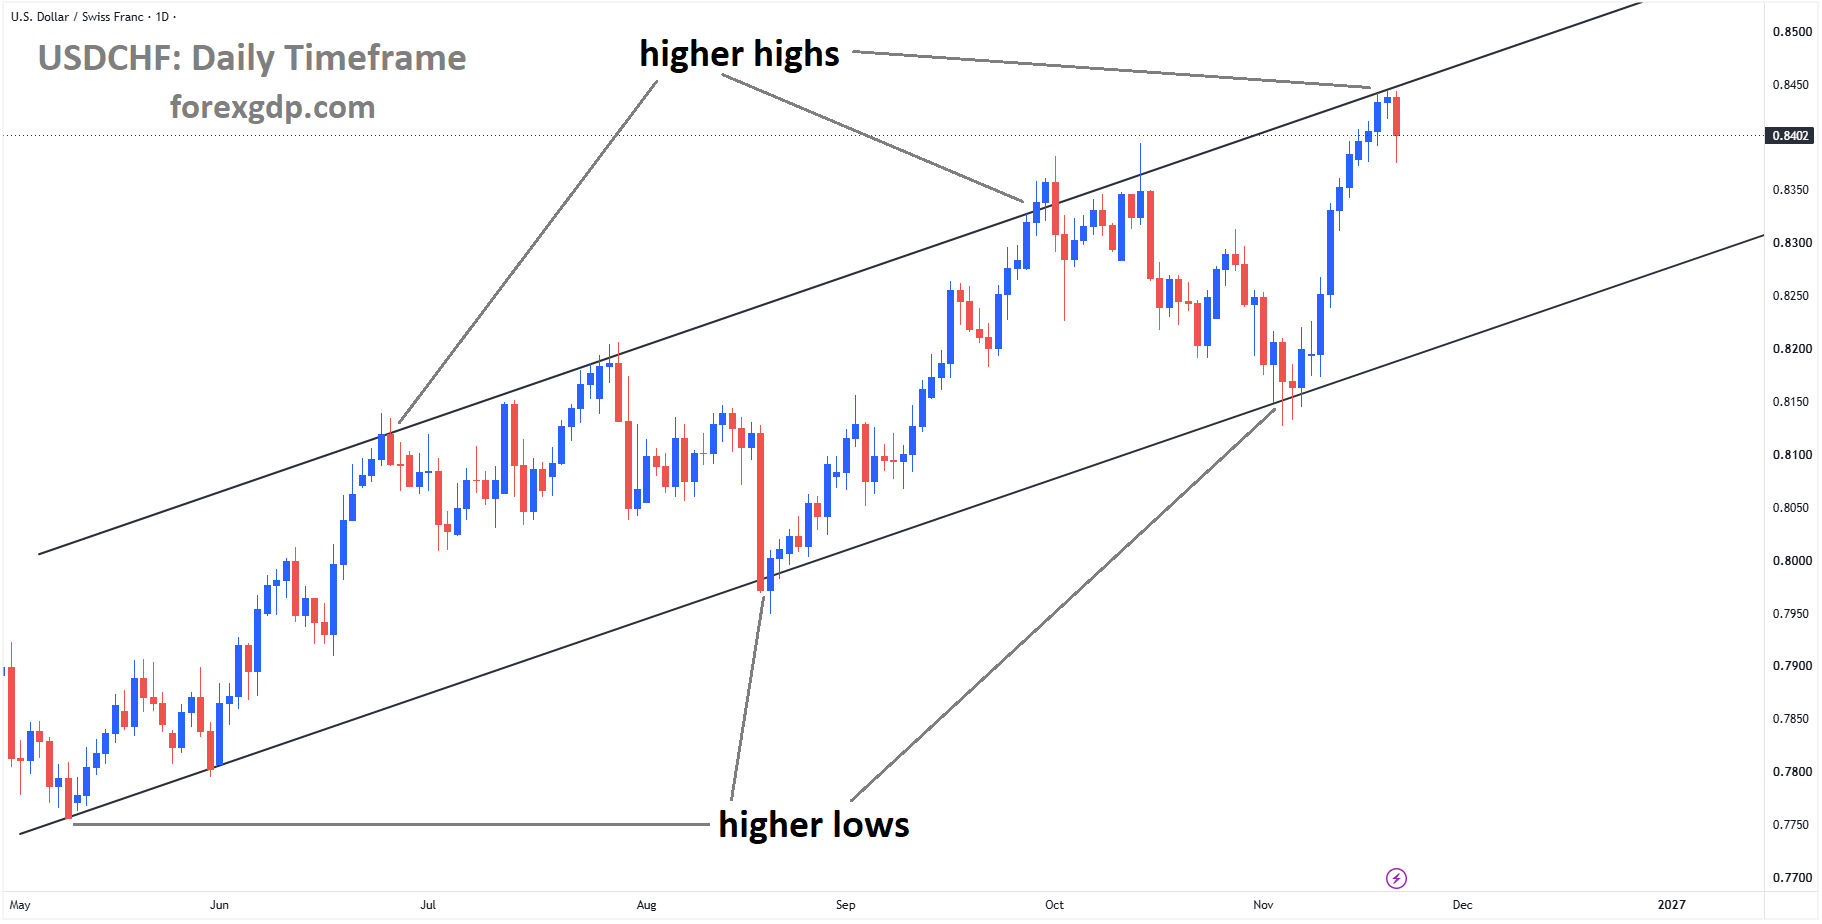
USDCHF reached the higher high area of the ascending channel
The US Dollar, which previously benefited from strong investment flows into American technology businesses, is now facing pressure as investors reconsider their exposure to the sector. At the same time, expectations surrounding the Federal Reserve’s monetary policy are adding another layer of uncertainty to the outlook for the US currency.
The changing market environment has helped the Swiss Franc attract renewed interest, highlighting its traditional role as a safe-haven currency during periods of financial instability.
Swiss Franc Gains Strength as Investors Become More Cautious
The Swiss Franc has emerged as one of the stronger major currencies as investors respond to growing concerns about the sustainability of the AI investment boom. The shift reflects a broader change in market sentiment, with investors becoming less willing to take risks in sectors that have experienced rapid growth.
Switzerland’s currency has historically attracted demand during uncertain economic conditions. The country’s reputation for financial stability, disciplined economic management, and a well-established banking system makes the Franc appealing when confidence in global markets weakens.
Recent developments in the technology sector have strengthened this appeal. Investors who previously focused on high-growth opportunities are beginning to reconsider their investment strategies as questions emerge about whether AI companies can deliver the financial results needed to justify their valuations.
This change in sentiment has supported the Swiss Franc while creating additional challenges for the US Dollar.
Although the American currency remains an important part of the global financial system, its performance can be influenced by international investment flows and changes in investor confidence.
AI Bubble Fears Put Pressure on the US Dollar
Artificial intelligence has become one of the most influential investment themes in recent years. Companies involved in AI software, advanced computing, semiconductor manufacturing, and cloud infrastructure have attracted considerable attention from investors worldwide.
The excitement surrounding AI has encouraged substantial investment in American technology companies, strengthening demand for US financial assets.
However, concerns are increasing that expectations for future AI growth may have moved ahead of what businesses can realistically achieve.
Investors are questioning whether the enormous spending on AI development will generate sufficient profits over time. While artificial intelligence has the potential to transform industries, commercial success may take longer than some investors initially expected.
These concerns have contributed to weaker confidence in technology stocks and have encouraged investors to reassess the risks associated with highly valued businesses.
For the US Dollar, the consequences could extend beyond the stock market.
Foreign investors often need US Dollars to purchase American financial assets. When international demand for these investments increases, it can provide additional support for the currency.
If investors begin reducing their exposure to American technology companies, some of those investment flows could reverse.
Such a development may reduce demand for the US Dollar, particularly if investors transfer funds into assets denominated in other currencies.
Why the AI Investment Boom Matters for the US Economy
The rapid expansion of artificial intelligence has played an important role in attracting international capital to the United States.
American technology companies have been at the center of AI innovation, benefiting from strong demand for advanced computing systems, data centers, and software solutions.
This leadership has helped make the United States an attractive destination for global investment.
Beyond technology companies themselves, AI-related spending has supported several connected industries, including energy infrastructure, digital services, and specialized manufacturing.
However, the scale of investment has also raised questions about long-term profitability.
Developing AI systems requires significant financial resources. Businesses must invest heavily in computing equipment, electricity, research, and skilled workers before they can fully benefit from their projects.
If revenue growth fails to meet expectations, companies may face pressure to reduce spending or delay expansion plans.
A slowdown in AI investment could affect businesses across multiple industries and weaken one of the important sources of optimism surrounding the American economy.
For currency markets, this matters because international investors consider both economic prospects and expected investment returns when deciding where to allocate capital.
A decline in confidence in the US technology sector could therefore influence broader perceptions of American financial assets.
Federal Reserve Policy Creates Additional Uncertainty
The Federal Reserve remains another major influence on the outlook for the US Dollar.
Expectations that the central bank could maintain restrictive monetary conditions or consider further interest rate increases have previously supported the American currency.
Higher interest rates can make US-denominated investments more attractive to international investors, particularly when returns elsewhere are less competitive.
However, tighter monetary policy can also create difficulties for businesses that depend on borrowing and continued investment.
Technology companies are especially sensitive to changes in financing conditions because many rely on substantial spending to develop new products, expand operations, and support future growth.
When borrowing costs rise, businesses may become more selective about new projects. Investors may also become less willing to pay high valuations for companies whose expected profits are concentrated far into the future.
This creates a difficult balance for the US Dollar.
On one hand, expectations of higher interest rates can encourage demand for the currency. On the other hand, those same expectations may weaken confidence in technology investments and contribute to capital moving away from American assets.
The overall effect depends on which influence becomes stronger.
Rising Interest Rates Could Challenge AI Companies
The relationship between interest rates and technology investment is becoming increasingly important as concerns about AI valuations grow.
Artificial intelligence development requires substantial long-term financial commitments. Companies are investing in advanced chips, large computing facilities, software development, and specialized infrastructure to remain competitive.
These investments can create significant opportunities, but they also involve uncertainty about future earnings.
If monetary conditions become more restrictive, companies may face higher financing costs and greater pressure to demonstrate that their AI spending can generate sustainable revenue.
Investors may also place more importance on current profitability rather than relying heavily on expectations of future expansion.
This could encourage a more cautious approach toward businesses with ambitious growth plans but limited evidence of consistent financial returns.
For the wider technology sector, such a shift may lead to more disciplined investment decisions.
Although this adjustment could support healthier long-term business development, it may also create short-term uncertainty in financial markets.
That uncertainty can influence currency demand, particularly when investors begin moving funds toward assets they consider more stable.
Safe-Haven Demand Supports the Swiss Franc
The Swiss Franc’s recent strength also reflects its reputation as a reliable currency during periods of market stress.
Switzerland benefits from strong institutions, a stable financial environment, and a long history of attracting international capital.
When investors become concerned about economic developments or financial market volatility, they often look for ways to reduce exposure to risk.
The Swiss Franc can benefit from this behavior, especially when uncertainty affects major international investment destinations.
However, safe-haven demand is not automatic. Currency movements also depend on central bank policies, economic conditions, and changes in global capital flows.
The Swiss National Bank’s monetary policy decisions can influence the Franc’s attractiveness, particularly when interest rate expectations differ between Switzerland and the United States.
Nevertheless, concerns surrounding AI-related investments have created an environment in which the Swiss currency may receive additional attention from cautious investors.
Global Investor Sentiment Remains a Key Factor
The direction of the US Dollar and Swiss Franc will depend partly on how investors respond to developments in the AI industry.
If technology companies demonstrate stronger profitability and provide convincing evidence that AI investments are delivering meaningful business results, confidence could improve.
Such a recovery may encourage renewed investment in American financial assets and help support demand for the US Dollar.
Alternatively, continued concerns about excessive valuations and uncertain returns could encourage investors to reduce their exposure to technology-related investments.
Federal Reserve policy will also remain important. Investors will closely consider how the central bank balances inflation concerns, economic growth, and financial conditions.
The interaction between monetary policy and technology-sector confidence could shape international investment decisions.
For now, the Swiss Franc’s resilience reflects a market environment in which financial stability and risk management are becoming increasingly important.
Summary
The Swiss Franc has strengthened against the US Dollar as concerns about a potential artificial intelligence bubble weigh on investor confidence.
The rapid growth of AI-related investment has attracted substantial international capital to the United States, but questions about company valuations and future profitability are creating uncertainty.
A reduction in foreign investment in American technology companies could weaken demand for the US Dollar, while greater risk aversion may encourage interest in the Swiss Franc.
At the same time, expectations surrounding Federal Reserve interest rate policy present a complicated situation. Tighter monetary conditions may support the Dollar but could also increase financial pressure on technology businesses.
The outlook for USD/CHF will therefore remain closely connected to investor confidence in artificial intelligence, global capital flows, and monetary policy developments in both countries.
As markets assess the long-term potential of AI, the balance between growth expectations and financial stability is likely to remain an important influence on both currencies.
AUDUSD Weakens Further as Australian Currency Faces Persistent Selling Pressure
The Australian Dollar (AUD) continues to face pressure against the US Dollar (USD), with the currency heading toward its third consecutive weekly decline. The weakness comes as investors reassess the Reserve Bank of Australia’s (RBA) interest rate outlook, while the US Federal Reserve maintains a firm approach to monetary policy.
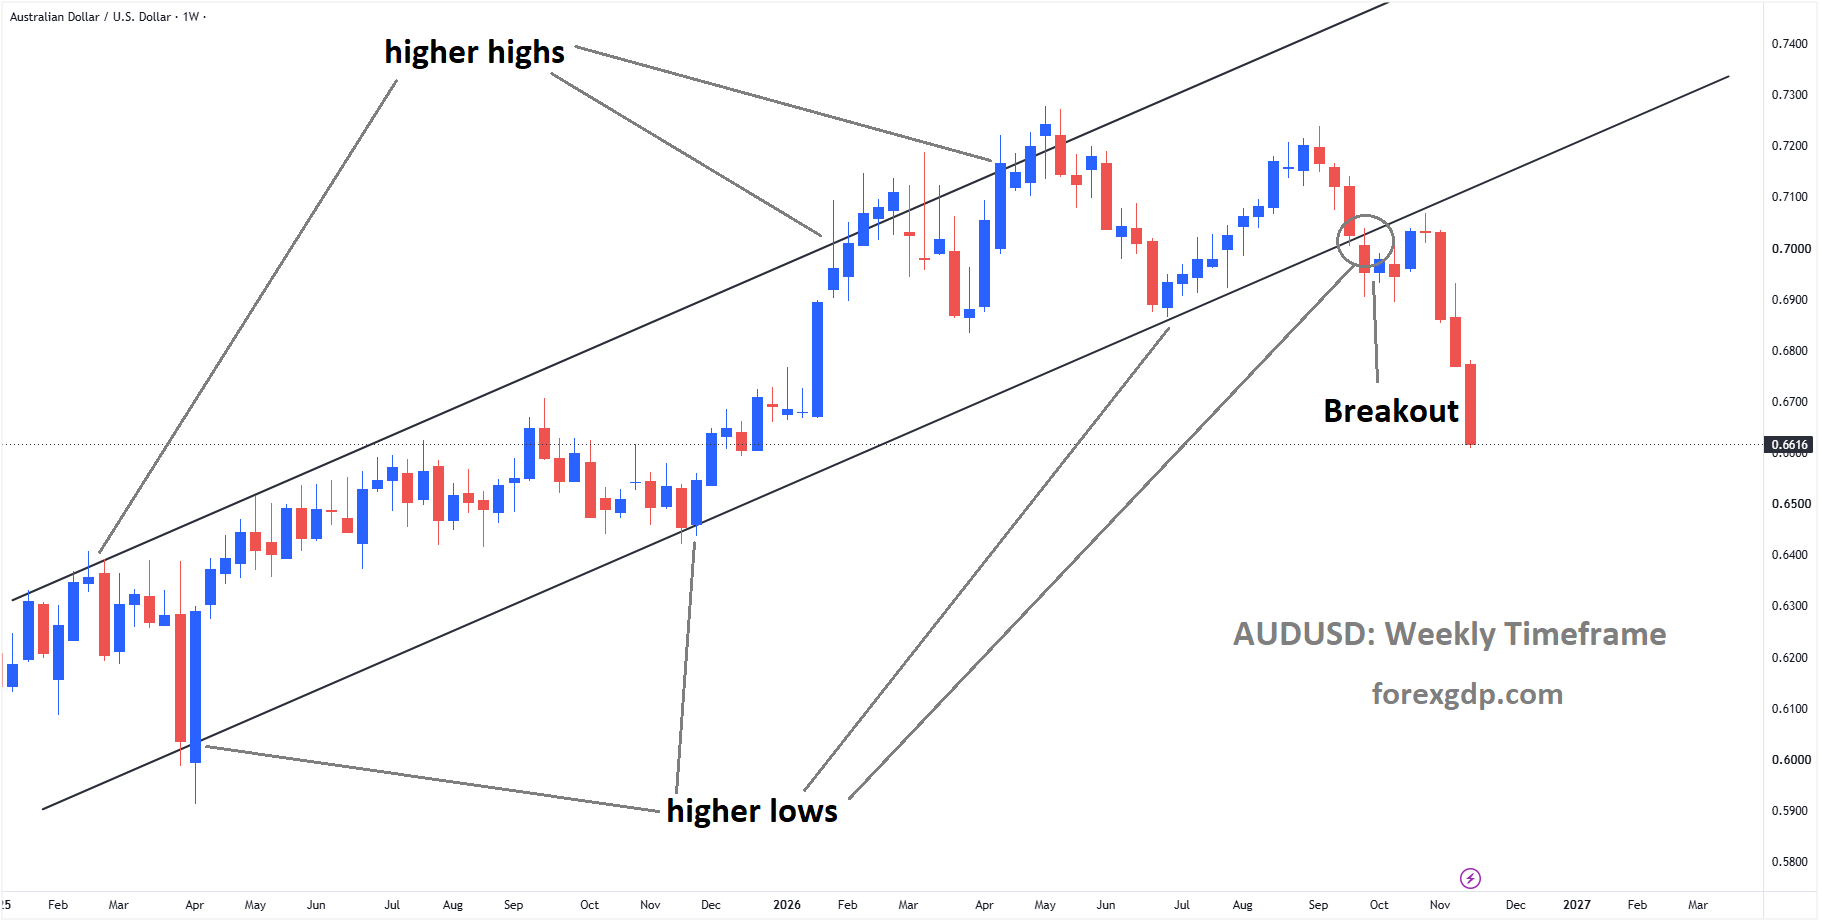
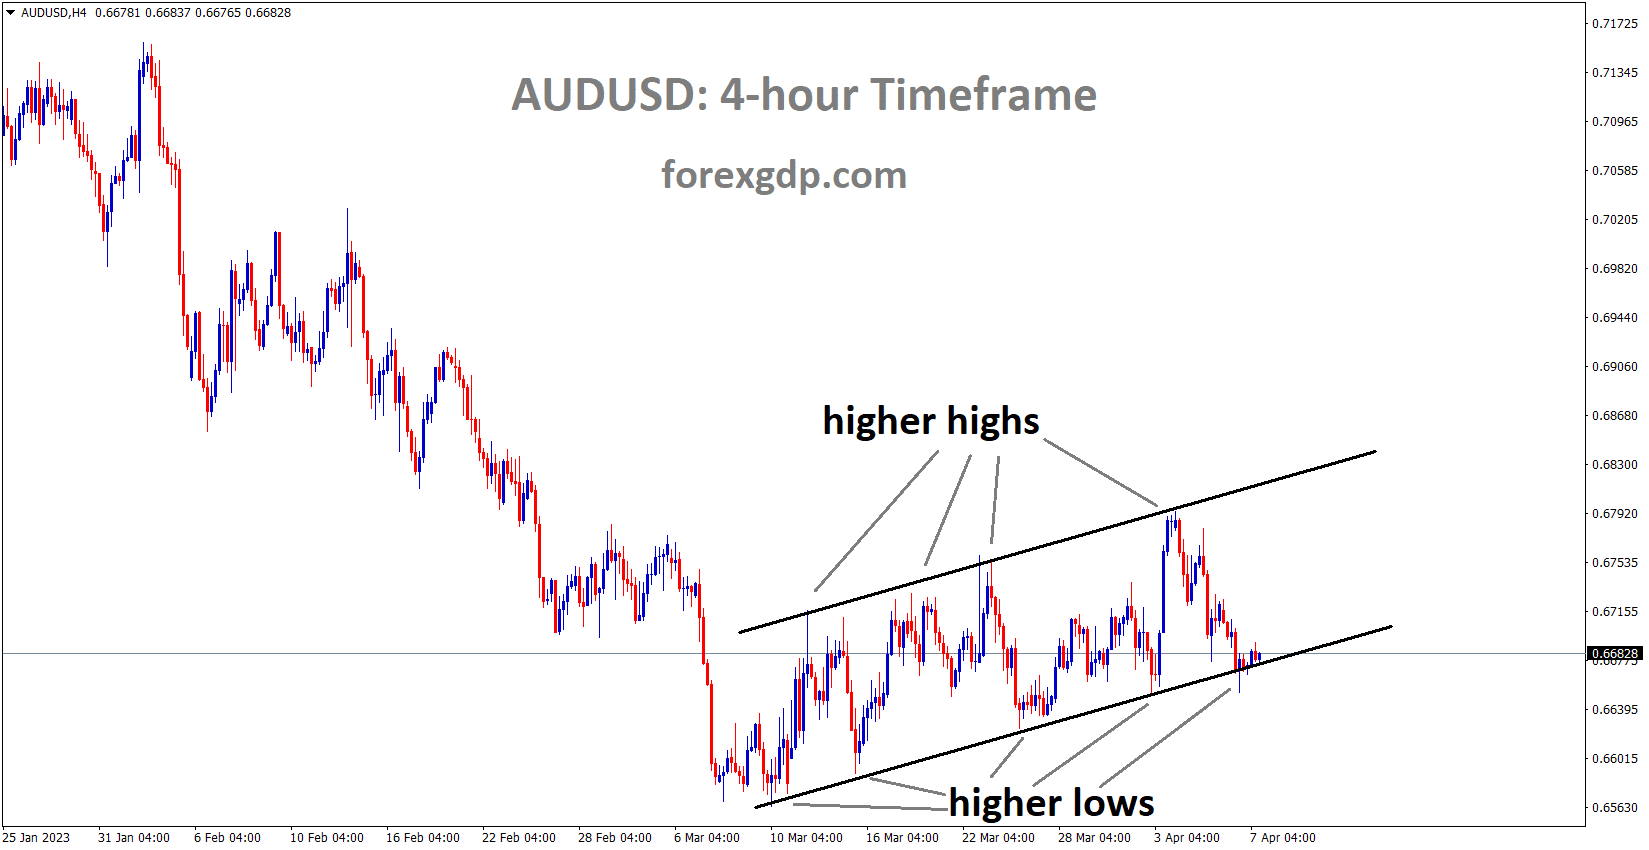
AUDUSD has broken the ascending channel to the downside
The Australian currency has struggled to attract sustained buying interest as expectations for further interest rate increases in Australia have weakened. At the same time, the US Dollar has benefited from the Federal Reserve’s willingness to keep monetary conditions restrictive to control inflation.
These developments have created a challenging environment for the Australian Dollar, with differences between Australian and US monetary policy expectations becoming an important factor in currency market sentiment.
Australian Dollar Struggles Amid Changing Interest Rate Expectations
The Australian Dollar has experienced another difficult week as investors become less confident that the Reserve Bank of Australia will continue raising interest rates.
Earlier expectations of additional monetary tightening had helped support the Australian currency. However, those expectations have gradually faded as market participants increasingly believe the central bank may have reached the end of its interest rate hiking cycle.
The change in sentiment has reduced the Australian Dollar’s appeal among investors who previously expected higher Australian interest rates to provide additional support for the currency.
Interest rate expectations play an important role in foreign exchange markets because they influence international investment decisions. When investors expect a country’s central bank to raise borrowing costs, its currency can become more attractive.
On the other hand, when expectations for further rate increases weaken, investors may reconsider their exposure to that currency.
This shift has contributed to the Australian Dollar’s recent underperformance against its US counterpart.
Although the Australian currency has shown occasional signs of recovery, the broader market environment remains challenging because of uncertainty surrounding Australia’s monetary policy outlook.
Reserve Bank of Australia May Have Completed Its Tightening Cycle
The Reserve Bank of Australia has played a central role in shaping the Australian Dollar’s performance.
During the monetary tightening period described in the original market report, the central bank introduced several interest rate increases to address persistent inflationary pressures.
The RBA delivered five quarter-percentage-point rate increases during the period covered, reflecting its determination to bring inflation under control and maintain economic stability.
However, investors have increasingly questioned whether additional tightening will be necessary.
The possibility that the RBA has completed its rate hiking cycle has become a significant concern for the Australian Dollar.
Why the RBA’s Policy Outlook Matters
Central banks influence currency movements through their decisions on interest rates and their communication about future monetary policy.
Higher interest rates can encourage international investors to hold assets denominated in a particular currency because those investments may offer more attractive returns.
When a central bank signals that its tightening cycle is nearing completion, expectations for additional returns can weaken.
For Australia, the changing outlook has affected investor confidence in the currency.
Market participants are also considering whether previous interest rate increases have already done enough to slow economic activity and reduce inflation.
If borrowing costs remain restrictive for an extended period, Australian households and businesses may face additional financial pressure.
This creates a difficult balancing act for the RBA, which must control inflation without causing unnecessary damage to economic growth.
Federal Reserve’s Hawkish Position Supports the US Dollar
While expectations surrounding Australian monetary policy have softened, the US Federal Reserve has maintained a comparatively hawkish position.
A hawkish monetary policy stance generally means that a central bank remains focused on controlling inflation, even when doing so requires keeping interest rates elevated.
The Federal Reserve’s commitment to managing inflation has strengthened confidence in the US Dollar.
Investors have interpreted the Fed’s communication as a sign that restrictive monetary conditions could remain in place until policymakers see convincing evidence that inflation is moving toward their objectives.
This approach has helped the US Dollar maintain its appeal in global currency markets.
The contrast between the Federal Reserve and the Reserve Bank of Australia has become particularly important for the AUD/USD currency pair.
While the Australian central bank appears closer to ending its tightening cycle, the Fed’s firm policy message has encouraged investors to favor the US currency.
As a result, the Australian Dollar has faced additional difficulty maintaining its position against the Greenback.
Differences Between the RBA and Fed Influence Investor Sentiment
Monetary policy differences between major central banks often have a direct influence on international capital flows.
Investors regularly compare economic conditions, interest rate expectations, and central bank statements before deciding where to allocate their funds.
When two central banks follow different policy paths, their currencies can respond accordingly.
In the case of Australia and the United States, the changing relationship between the RBA and Fed has become a major influence on investor sentiment.
The RBA’s apparent move toward a more cautious approach suggests that Australian policymakers are becoming increasingly aware of the economic effects of previous rate increases.
Meanwhile, the Federal Reserve’s continued focus on inflation has reinforced expectations that US monetary policy could remain restrictive.
This difference may encourage some investors to favor US Dollar-denominated assets over Australian alternatives.
However, central bank policy is not the only factor influencing currency demand.
Economic growth, employment conditions, international trade, and global financial confidence also contribute to the relative strength of the Australian and US currencies.
Australia’s Economic Outlook Remains Important for the Aussie

The Australian Dollar is closely connected to the broader health of the Australian economy.
As a country with significant exports of natural resources and agricultural products, Australia is particularly sensitive to changes in global demand and international trade conditions.
Economic developments among Australia’s major trading partners can therefore influence confidence in the currency.
Stronger international demand for Australian exports may support business activity, employment, and overall economic growth.
However, weaker global economic conditions can create challenges for export-oriented industries and reduce investor enthusiasm for the Australian Dollar.
Domestic economic conditions are equally important.
Australian households have faced the effects of higher borrowing costs, particularly through mortgage repayments and other forms of credit.
Businesses may also become more cautious about investment and expansion when financing remains expensive.
These pressures help explain why the RBA must carefully evaluate the need for additional monetary tightening.
If economic activity slows more than expected, policymakers may prefer to maintain existing restrictions rather than introduce further increases.
Such decisions could influence how investors assess the Australian Dollar’s longer-term prospects.
Global Risk Sentiment Adds Another Challenge for the Australian Dollar
The Australian Dollar is often considered a currency that responds strongly to changes in global investor confidence.
During periods of economic optimism, investors may show greater interest in currencies associated with international trade and global growth.
Australia’s strong connections with commodity markets and Asian economies make its currency particularly sensitive to these developments.
However, when uncertainty increases, investors often become more cautious and seek assets they consider relatively secure.
The US Dollar frequently benefits from this behavior because of its central role in international finance and global trade.
As a result, the Australian Dollar can face pressure even when domestic economic developments are relatively stable.
Concerns about global growth, geopolitical uncertainty, and changing expectations for major economies may all influence the direction of the currency.
For the Aussie to regain stronger investor confidence, improvements in global economic sentiment could prove helpful.
What Could Influence the Australian Dollar Going Forward?
The Australian Dollar’s future performance will depend on several economic and policy developments.
One of the most important factors will be the Reserve Bank of Australia’s communication regarding future interest rate decisions.
Investors will pay close attention to whether policymakers confirm that additional tightening is unnecessary or leave the possibility of further action open.
Australian inflation figures, employment reports, consumer spending, and economic growth data will also help shape expectations.
In the United States, Federal Reserve statements and major economic releases will remain important drivers of US Dollar sentiment.
If the Fed continues emphasizing inflation risks and restrictive monetary policy, the US Dollar may retain an advantage.
However, a change in US economic conditions or a softer Federal Reserve outlook could alter the balance between the two currencies.
Global trade developments and overall investor confidence will provide additional influences.
Summary
The Australian Dollar is facing a difficult period against the US Dollar as changing monetary policy expectations weigh on investor confidence.
The prospect that the Reserve Bank of Australia has completed its interest rate tightening cycle has reduced expectations for additional support from Australian monetary policy.
At the same time, the Federal Reserve’s hawkish approach has strengthened the US Dollar’s position and created further challenges for the Aussie.
Although the Australian currency has experienced brief periods of stability, uncertainty surrounding domestic economic conditions and international monetary policy continues to influence sentiment.
Looking ahead, the direction of the Australian Dollar will depend on how the RBA and Federal Reserve respond to inflation, economic growth, and financial conditions.
For now, the difference between the two central banks’ policy outlooks remains a central reason behind the Australian Dollar’s continued weakness against the US Dollar.
NZDUSD Regains Momentum as US Dollar Faces Fresh Pressure
The New Zealand Dollar (NZD) has regained some strength against the US Dollar (USD), ending a prolonged period of weakness that began on November 10. The NZD/USD recovery comes as the Greenback faces renewed pressure from uncertainty surrounding the US technology sector, changing investor sentiment, and concerns about the long-term sustainability of artificial intelligence investments.
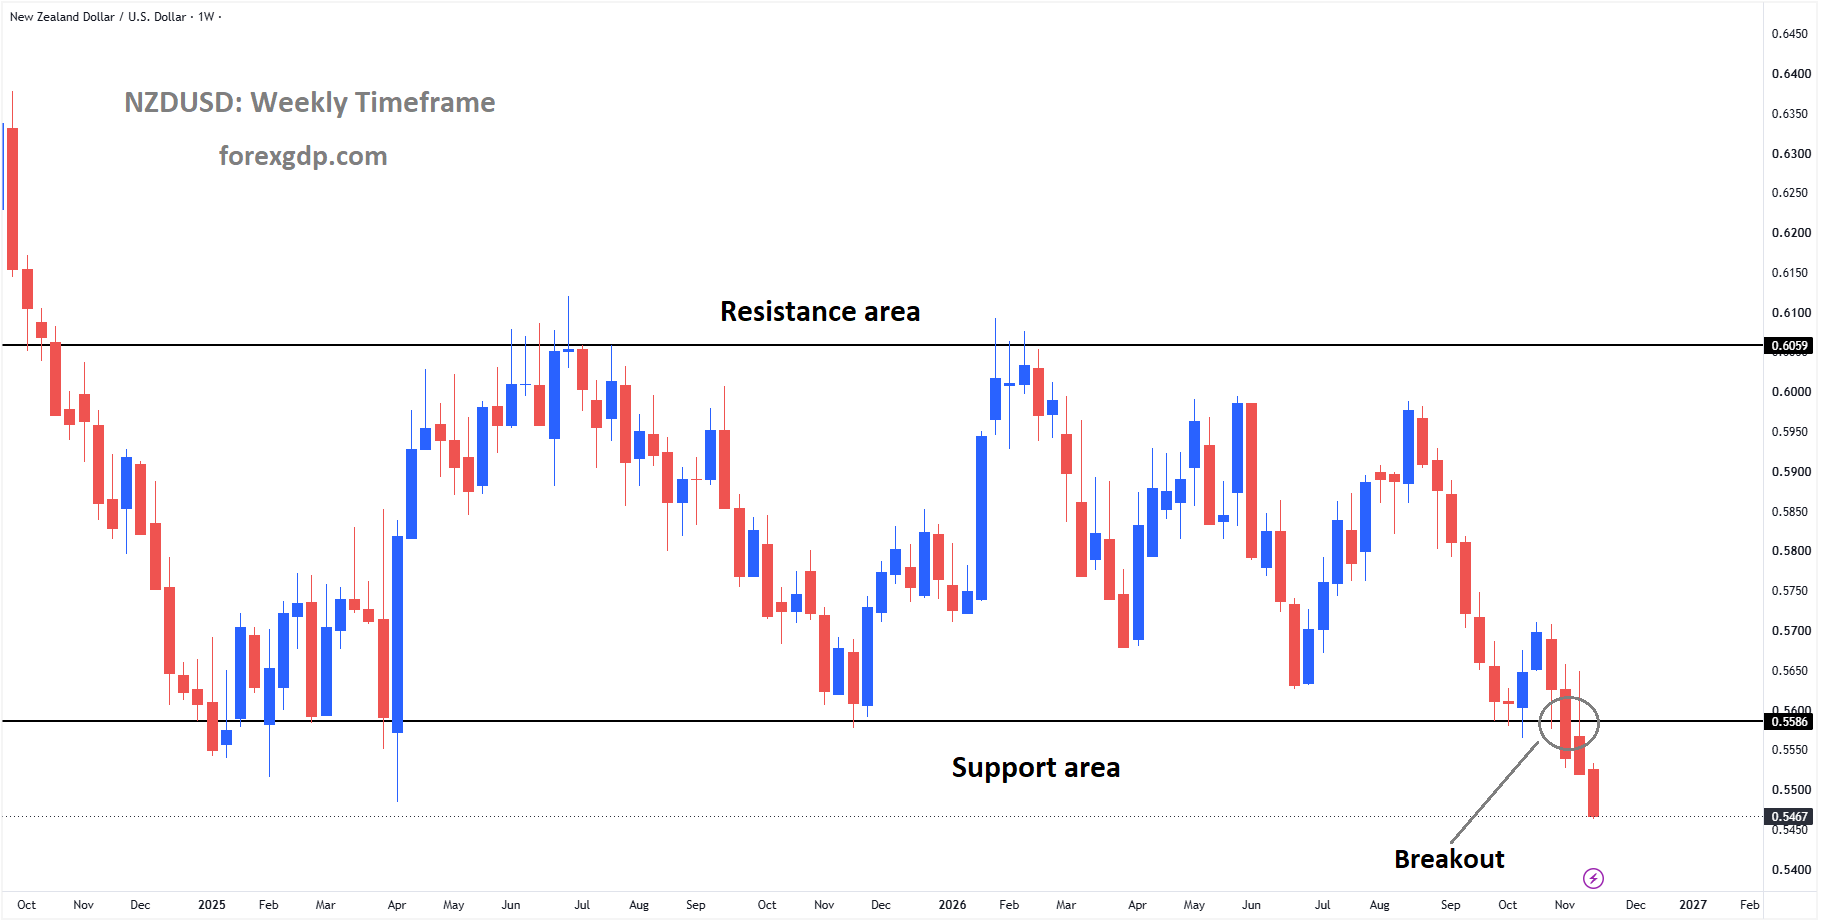
NZDUSD broken the box pattern to the downside
Despite the improvement in the New Zealand Dollar, the broader economic environment remains uncertain. Expectations of further interest rate increases by the Federal Reserve could support the US Dollar, while China’s decision to maintain its benchmark lending rates provides some stability for New Zealand’s economic outlook.
Investors are now paying close attention to monetary policy developments, global financial conditions, and economic activity in China to understand what could influence the NZD/USD currency pair in the coming weeks.
NZD/USD Ends Losing Streak as US Dollar Faces Renewed Pressure
The NZD/USD currency pair has shown signs of recovery after experiencing several consecutive sessions of losses. The improvement reflects a softer US Dollar rather than a significant change in New Zealand’s domestic economic conditions.
The Greenback has struggled to maintain its strength despite continued demand for safe-haven assets. During periods of financial uncertainty, investors often prefer the US Dollar because of its global importance and widespread use in international transactions.
However, the relationship between market uncertainty and US Dollar demand is not always straightforward. Concerns about the American economy, particularly its technology sector, can also discourage international investors from increasing their exposure to US assets.
Recent developments in artificial intelligence have added another layer of uncertainty. Questions about investment returns, corporate financing, and the sustainability of rapid AI expansion have affected confidence across global equity markets.
As investors reconsider their exposure to American technology companies, the US Dollar may face additional pressure. This situation has created an opportunity for the New Zealand Dollar to recover some of its recent losses.
Nevertheless, the recovery remains vulnerable to changes in global investor confidence and expectations surrounding US monetary policy.
Artificial Intelligence Investment Concerns Weigh on US Dollar Sentiment

The rapid expansion of artificial intelligence has become an important influence on global financial markets. Major technology companies have attracted substantial investment as businesses increase spending on AI infrastructure, advanced computing systems, and related services.
These investments have helped direct international capital toward the United States, supporting demand for American financial assets and the US Dollar.
However, growing concerns about the financial sustainability of the AI boom have raised questions about whether these capital inflows can continue at the same pace.
Investors are increasingly examining whether companies can generate sufficient revenue to justify their large commitments to artificial intelligence development.
Uncertainty surrounding financing requirements and future profitability has also contributed to weaker confidence in technology-related investments.
Commerzbank Highlights Risks to Dollar Strength
Analysts at Commerzbank have warned that the US Dollar’s dependence on investment flows into American technology companies could become a source of vulnerability.
If concerns about the sustainability of artificial intelligence spending lead to a broader decline in US equities, international investors may reconsider their positions in American assets.
Such a shift could reduce capital inflows into the United States and weaken demand for the Greenback.
However, Commerzbank does not expect the rapid development of artificial intelligence infrastructure to end suddenly. The bank considers an abrupt halt to AI expansion unlikely, suggesting that investment activity could continue despite temporary periods of uncertainty.
This distinction is important because short-term changes in investor confidence do not necessarily indicate a lasting decline in the technology sector.
For the US Dollar, the main concern is whether changing investment behavior could create additional uncertainty in international currency markets.
Federal Reserve Interest Rate Expectations Could Support the US Dollar
Although the US Dollar has recently faced selling pressure, expectations surrounding Federal Reserve monetary policy could help restore confidence in the currency.
The Federal Reserve plays a central role in determining global financial conditions because its interest rate decisions influence borrowing costs, investment flows, and international currency demand.
When the Fed raises interest rates, US financial assets may become more attractive to investors seeking higher returns. This can increase demand for the US Dollar, particularly when other major central banks maintain comparatively accommodative policies.
According to the reported minutes of the October Federal Open Market Committee meeting, nearly all participating officials expected that additional monetary tightening would be necessary.
Their concerns centered on inflation risks and the possibility that existing monetary conditions might not be restrictive enough to control rising prices.
These expectations have encouraged investors to consider the possibility of further interest rate increases.
Inflation Concerns Keep Monetary Policy in Focus
Inflation remains one of the most important factors shaping Federal Reserve decisions.
When consumer prices rise too quickly, the central bank may increase borrowing costs to reduce spending and bring inflation under control.
Federal Reserve Governor Christopher Waller has also emphasized the importance of responding appropriately to persistent price pressures.
His comments have reinforced expectations that policymakers could maintain a restrictive approach if inflation continues to threaten economic stability.
The reported CME FedWatch probabilities indicate overwhelming expectations of a December interest rate increase, with investors favoring a smaller adjustment over a more aggressive move.
However, these probabilities represent market expectations rather than confirmed Federal Reserve decisions.
Any unexpected change in inflation, employment conditions, or economic activity could influence policymakers’ decisions.
For NZD/USD, the direction of US monetary policy remains particularly important because higher American interest rates can strengthen the Greenback and limit gains in the New Zealand Dollar.
China’s Decision to Maintain Lending Rates Provides Stability for New Zealand
China’s monetary policy decisions are another important influence on the New Zealand Dollar.
As one of New Zealand’s major trading partners, China plays a significant role in supporting demand for New Zealand exports, including dairy products, agricultural goods, and other commodities.
Changes in Chinese economic activity can therefore affect New Zealand’s export earnings, business confidence, and broader economic performance.
The People’s Bank of China has maintained its benchmark one-year and five-year loan prime rates, continuing its existing lending policy.
The decision was widely anticipated and provided a degree of stability for investors monitoring economic developments across the Asia-Pacific region.
Why China’s Lending Policy Matters for the New Zealand Dollar
China’s loan prime rates influence borrowing conditions for businesses and households.
The one-year rate is particularly relevant to corporate lending, while the five-year rate plays an important role in longer-term financing, including property-related borrowing.
By keeping these rates unchanged, Chinese authorities have signaled continuity in their approach to monetary policy.
For New Zealand, stable financial conditions in China can help reduce uncertainty surrounding trade and economic demand.
However, unchanged lending rates do not automatically guarantee stronger Chinese economic growth.
Investors must also consider consumer spending, industrial production, property market conditions, and demand for imported goods.
A stronger Chinese economy could benefit New Zealand exporters and improve confidence in the NZD. Conversely, weaker Chinese demand could create challenges for New Zealand businesses that depend heavily on international trade.
Global Economic Uncertainty Remains Important for NZD/USD
The outlook for NZD/USD depends on several interconnected economic developments.
US Dollar sentiment remains closely linked to Federal Reserve policy, inflation expectations, and international investment flows.
At the same time, the New Zealand Dollar is sensitive to global economic confidence because New Zealand operates as a relatively small, trade-dependent economy.
When investors become more comfortable taking financial risks, currencies such as the NZD may benefit from improving sentiment.
During periods of heightened uncertainty, however, investors may shift toward assets traditionally considered safer, potentially reducing demand for the New Zealand Dollar.
Developments in China add another important consideration, particularly because changes in Chinese demand can influence New Zealand’s export sector.
As a result, the NZD/USD outlook is likely to reflect a combination of American monetary policy, global investment confidence, and economic developments across the Asia-Pacific region.
Summary
The New Zealand Dollar has recovered against the US Dollar as concerns about artificial intelligence investments and weaker confidence in American financial assets place pressure on the Greenback.
However, expectations of further Federal Reserve interest rate increases could provide renewed support for the US currency, potentially limiting the NZD’s recovery.
Meanwhile, China’s decision to maintain its benchmark lending rates offers some stability for New Zealand’s trade-related economic outlook.
Looking ahead, Federal Reserve policy decisions, inflation developments, Chinese economic activity, and global investor sentiment will remain central to the direction of NZD/USD.
EURGBP Slides as Strong UK Consumer Spending Fuels Sterling Strength
The EUR/GBP currency pair came under mild pressure during Friday’s early European trading session as stronger-than-expected UK retail sales helped the British Pound maintain its strength against the Euro. The latest consumer spending figures offered encouraging signs for the British economy, suggesting that household demand remained resilient despite ongoing economic uncertainty.
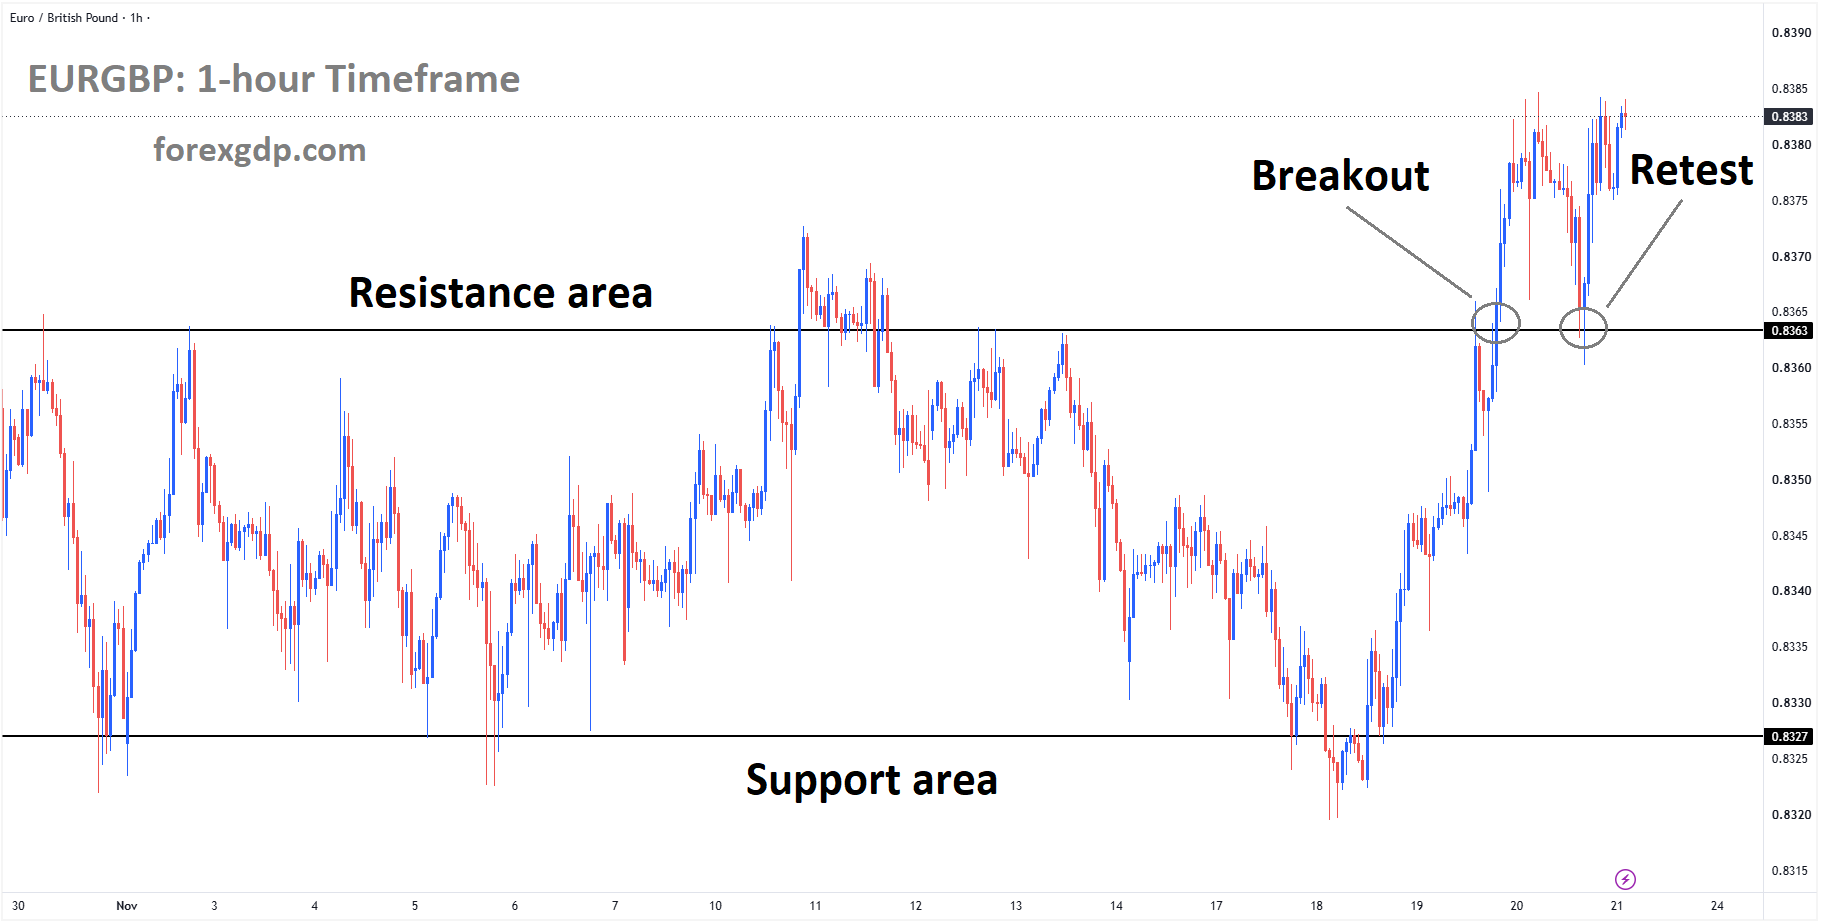
EURGBP is rebounding from the retest area of the box pattern
Meanwhile, the Euro continued to receive support from rising inflation across the Eurozone and growing expectations that the European Central Bank (ECB) could raise interest rates in December. However, uncertainty surrounding the central bank’s next decision has kept investors cautious.
The contrasting economic developments in the United Kingdom and the Eurozone have created a mixed outlook for EUR/GBP, with both currencies finding support from different factors.
British Pound Strengthens Following Better-Than-Expected UK Retail Sales
The British Pound remained relatively firm after the United Kingdom released encouraging retail sales figures for October. The data, published by the Office for National Statistics (ONS), showed that consumer spending performed considerably better than economists had anticipated.
UK retail sales increased by 0.7% month over month in October, recovering from a 0.4% decline recorded in September. Economists had expected retail sales to remain unchanged during the month, making the actual improvement a positive surprise.
The annual figures also exceeded expectations. Retail sales grew by 2.3% compared with the same month a year earlier, comfortably surpassing the forecast of 1.7%. The previous annual reading had been revised to 0.4%, making October’s performance particularly encouraging.
These results suggest that British consumers continued spending despite concerns about household finances, borrowing costs, and the wider economic environment.
Retail sales are an important measure of economic activity because household spending contributes significantly to the UK’s overall economic performance. When consumers increase their purchases, businesses can benefit from stronger demand, potentially supporting employment and broader economic growth.
For the British Pound, better-than-expected economic figures can improve investor confidence in the country’s economic outlook. This helps explain why Sterling maintained its position against the Euro following the release.
UK Consumer Spending Provides Encouraging Economic Signals
The recovery in retail sales is particularly important because consumer confidence plays a major role in determining the direction of the British economy.
Households often adjust their spending habits when they face uncertainty about inflation, wages, employment, or future borrowing costs. A meaningful improvement in retail activity can therefore suggest that consumers are becoming more willing to make purchases.
October’s figures indicate that demand improved after September’s disappointing performance. Although one month of stronger sales does not establish a lasting recovery, the results provide a welcome indication that consumer activity has not weakened as much as previously feared.
The stronger annual growth figure also adds weight to the positive assessment. It suggests that retail spending improved not only compared with the previous month but also relative to the same period in the previous year.
However, retail sales alone cannot provide a complete picture of the UK economy. Other factors, including business investment, employment conditions, wage growth, and inflation, remain important when assessing the country’s economic health.
Investors will therefore continue monitoring upcoming economic releases to determine whether the improvement in household spending can be sustained.
For now, the latest retail figures have provided the British Pound with a supportive economic backdrop.
Euro Finds Support as Eurozone Inflation Reaches Three-Year High
While the British Pound benefited from stronger UK consumer spending, the Euro received support from developments in Eurozone inflation.
Final figures released by Eurostat confirmed that headline inflation reached 4.0% in October, marking its highest level in three years.
The increase has attracted attention because inflation remains one of the most important considerations influencing monetary policy decisions by the European Central Bank.
Core inflation, which excludes certain volatile components to provide a clearer picture of underlying price pressures, was also revised slightly higher. The final reading increased to 2.6%, compared with the earlier estimate of 2.5%.
This upward revision suggests that inflationary pressure may be more persistent than initially expected.
When inflation remains elevated, central banks may consider raising interest rates to reduce demand and encourage price stability. Higher borrowing costs can discourage spending and investment, helping to ease inflation over time.
However, monetary tightening can also create challenges for businesses and households by making loans and credit more expensive.
The latest inflation figures have therefore strengthened expectations that the ECB could consider another interest rate increase at its December policy meeting.
Such expectations can support the Euro because investors often respond to changes in the anticipated direction of monetary policy.
Nevertheless, the relationship between inflation, interest rates, and currency movements is not always straightforward. Economic growth, investor confidence, and developments in other major economies can also influence the Euro’s performance.
ECB December Interest Rate Decision Remains Uncertain

Despite growing expectations of a December interest rate increase, the European Central Bank has not committed to taking that step.
ECB President Christine Lagarde previously made it clear that she could not guarantee an interest rate hike at the upcoming meeting.
Her comments highlight the uncertainty surrounding the central bank’s next move and suggest that policymakers are keeping their options open.
Central banks generally examine several economic indicators before changing borrowing costs. Inflation is a major consideration, but officials also assess economic growth, employment conditions, financial stability, and the potential consequences of tighter monetary policy.
For the ECB, the challenge is to control inflation without placing unnecessary pressure on an already uncertain economic environment.
Raising interest rates could help address persistent price pressures, but it could also increase financing costs for households and businesses across the Eurozone.
On the other hand, leaving rates unchanged while inflation remains elevated could raise questions about how quickly price stability can be restored.
Lagarde’s cautious remarks suggest that policymakers want to evaluate the available evidence before making a final decision.
As a result, upcoming economic reports and statements from ECB officials are likely to play an important role in shaping expectations ahead of December.
Widening US-Eurozone Interest Rate Gap Adds Another Consideration
Another development attracting attention is the growing difference between short-term interest rate expectations in the United States and the Eurozone.
According to ING, the gap between US and Eurozone two-year swap rates widened by approximately one-third of a percentage point, reaching its broadest level since September 2025.
Swap rates reflect financial market expectations about future borrowing costs and monetary policy conditions.
A widening difference can indicate that investors expect the two regions to follow different interest rate paths.
This development matters for the Euro because international investors frequently compare interest rate expectations across major economies when deciding where to allocate capital.
If expected returns become more attractive in one region than another, international investment flows may change accordingly.
Although the US-Eurozone interest rate difference does not directly determine EUR/GBP movements, it can influence the Euro’s broader appeal and affect investor sentiment toward the European currency.
The impact will also depend on how monetary policy expectations develop in the United Kingdom.
For EUR/GBP, the relative outlook for the ECB and the Bank of England remains especially important, as changes in either institution’s policy direction can affect demand for the Euro and British Pound.
EUR/GBP Outlook Depends on Economic Data and Central Bank Expectations
The near-term outlook for EUR/GBP remains influenced by competing economic developments.
On one side, stronger UK retail sales have reinforced confidence in British consumer activity and provided support for Sterling.
On the other, elevated Eurozone inflation has increased expectations of a possible ECB interest rate hike, offering the Euro its own source of strength.
The uncertainty surrounding December’s ECB decision makes the situation more complicated. While inflation data may encourage policymakers to consider tighter monetary conditions, Lagarde’s comments indicate that an increase is not guaranteed.
Investors will also pay attention to future UK economic releases and any signals from the Bank of England regarding its monetary policy outlook.
Ultimately, the relative strength of the two currencies will depend on whether upcoming information supports the current expectations for each economy.
Final Summary
The British Pound has maintained a firm position against the Euro following stronger-than-expected UK retail sales figures for October. Monthly sales increased by 0.7%, while annual growth reached 2.3%, suggesting an improvement in consumer spending and providing encouragement about the British economy.
At the same time, Eurozone inflation reaching a three-year high of 4.0% has strengthened expectations that the European Central Bank may raise interest rates in December. However, ECB President Christine Lagarde has avoided making a firm commitment, leaving uncertainty about the upcoming decision.
The widening gap between US and Eurozone short-term interest rate expectations adds another factor influencing sentiment toward the Euro.
With economic developments offering support to both currencies, the EUR/GBP outlook remains closely connected to incoming economic data, inflation trends, and the monetary policy decisions of the ECB and Bank of England.
GBPJPY Remains Under Pressure as Japan’s Monetary Policy Outlook Challenges Sterling
The British Pound continues to face pressure against the Japanese Yen, even after stronger-than-expected UK Retail Sales figures provided some temporary relief. The GBP/JPY currency pair managed to recover slightly from its recent weakness, but the improvement failed to develop into a sustained rebound as investors remained cautious about the monetary policy outlook in both countries.
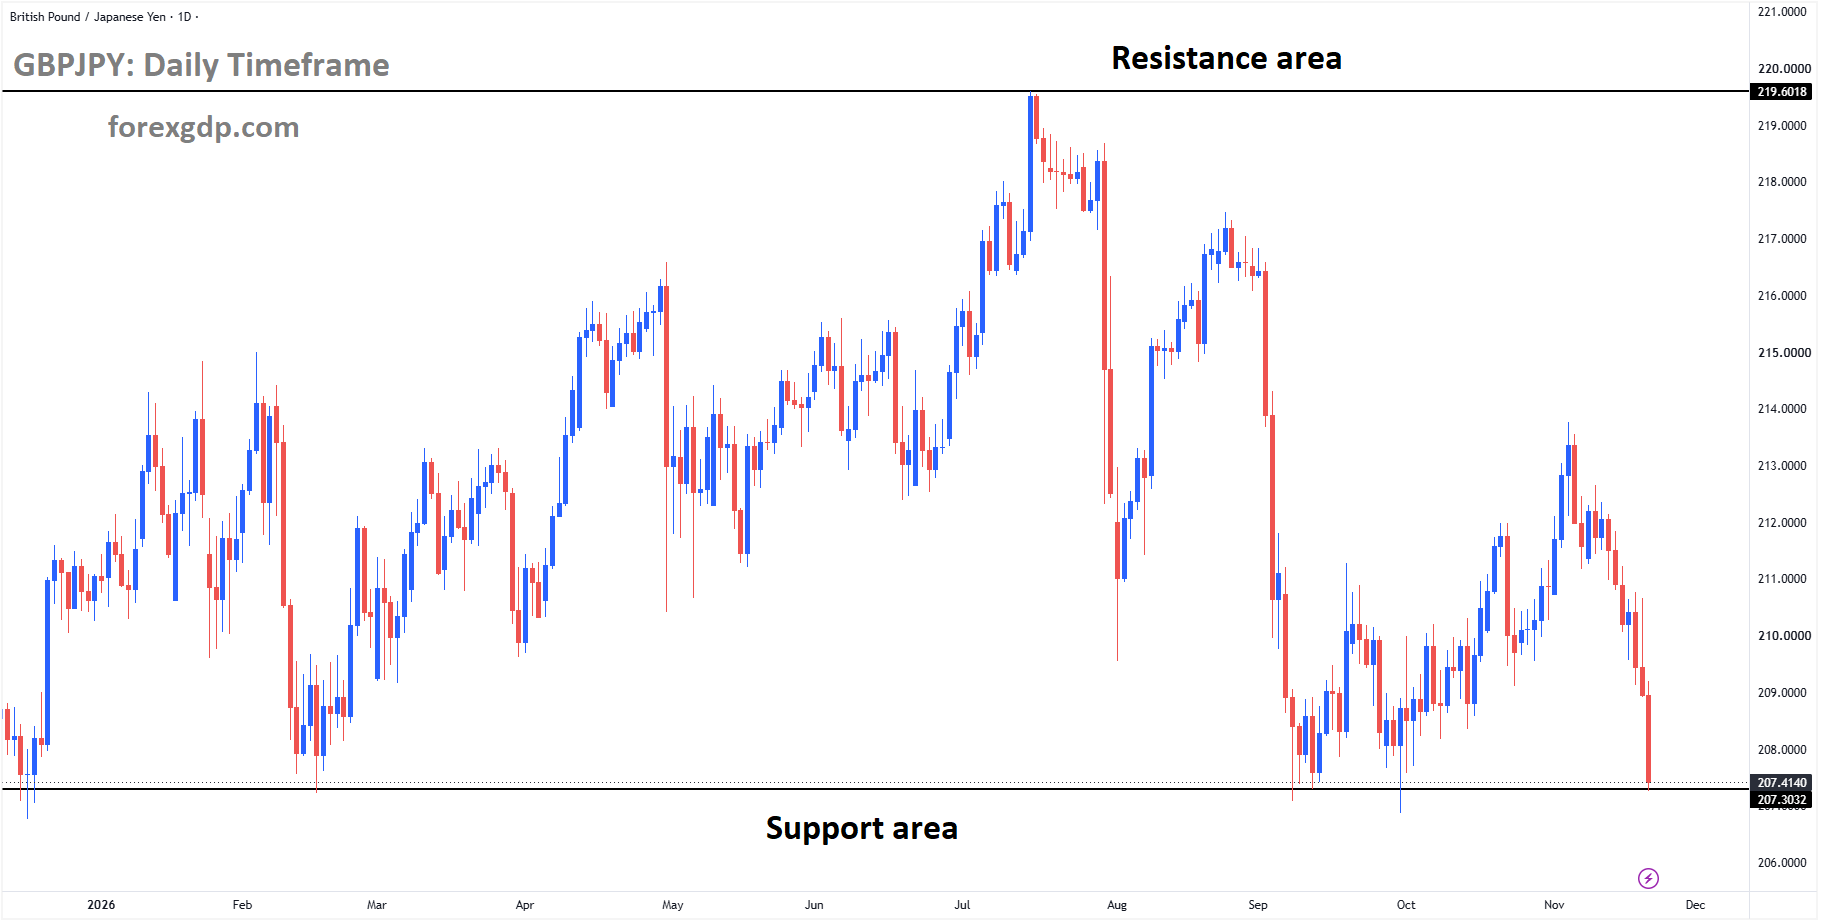
GBPJPY reached the support area of the box pattern
While encouraging UK consumer spending data offered some support to the Pound Sterling, changing expectations surrounding the Bank of England’s (BoE) interest rate decisions have limited its strength. Meanwhile, the Japanese Yen has benefited from growing confidence that the Bank of Japan (BoJ) could tighten monetary policy further.
Japan’s latest inflation figures, along with warnings from government officials about excessive currency movements, have added to the Yen’s appeal. These developments have created a challenging environment for the British Pound, leaving GBP/JPY vulnerable to continued selling pressure.
Strong UK Retail Sales Provide Temporary Support to the British Pound
The latest UK Retail Sales report delivered a positive surprise, suggesting that British consumers remained willing to spend despite ongoing economic uncertainty.
According to the Office for National Statistics (ONS), retail sales increased by 0.7% in October. This performance exceeded economists’ expectations, which had pointed to no monthly growth. The improvement was particularly encouraging because September’s figures had been revised downward to show a 0.6% decline.
The stronger reading indicates that consumer activity recovered following the previous month’s weakness. Retail spending is an important part of the British economy because household purchases contribute significantly to overall economic growth.
When consumers spend more on goods and services, businesses may experience stronger demand, potentially supporting employment, investment, and broader economic activity.
For the British Pound, better retail sales figures can be encouraging because they suggest that the economy may be more resilient than previously expected.
However, a single positive economic report is rarely enough to change the overall direction of a currency. Investors also consider inflation, employment conditions, business confidence, and central bank policy before making decisions.
In this case, the encouraging retail sales figures helped ease some immediate pressure on Sterling, but they were not sufficient to overcome the wider concerns affecting the currency.
Bank of England Interest Rate Uncertainty Limits Pound Sterling Recovery
One of the main reasons behind the Pound’s limited recovery is the changing outlook for Bank of England monetary policy.
Investors have become less confident that the BoE will introduce another interest rate increase at its December 17 policy meeting. This shift followed mixed UK consumer inflation figures, which raised questions about whether additional monetary tightening would be necessary.
Central banks use interest rates to influence inflation, borrowing, spending, and economic growth. Higher borrowing costs can help control inflation by reducing demand, although they may also slow economic activity.
For currencies, expectations of higher interest rates can provide support because investors may find assets denominated in that currency more attractive.
However, when markets begin to anticipate fewer rate increases, that potential advantage can weaken.
The latest UK inflation figures appear to have encouraged investors to reconsider the likelihood of further action from the Bank of England. Although inflation remains an important concern for policymakers, economic conditions also influence how aggressively the central bank can respond.
The BoE must balance its responsibility to maintain price stability with the need to avoid unnecessary damage to economic growth.
This uncertainty has made investors hesitant to build stronger positions in the British Pound, even when economic reports deliver positive surprises.
As a result, Sterling has struggled to benefit fully from the improvement in consumer spending.
Japanese Inflation Data Strengthens Expectations of Bank of Japan Tightening

While the British Pound faces uncertainty over future interest rate increases, the Japanese Yen is receiving support from a different monetary policy outlook.
Japan’s latest National Consumer Price Index (CPI) report has reinforced expectations that the Bank of Japan could raise borrowing costs at its next policy meeting.
The CPI measures changes in the prices consumers pay for everyday goods and services. It is one of the most closely watched economic reports because it helps policymakers assess inflationary pressure across the economy.
For many years, Japan maintained exceptionally low interest rates as authorities worked to encourage spending, investment, and sustainable inflation.
However, changing inflation conditions have gradually shifted attention toward the possibility of further monetary policy normalization.
The latest consumer inflation report has strengthened the view that the BoJ may have enough justification to continue adjusting borrowing costs.
Expectations of higher Japanese interest rates can support the Yen by making Japanese financial assets relatively more attractive to investors.
They can also influence international investment decisions, particularly among market participants who borrow in lower-interest-rate currencies to invest elsewhere.
If Japanese borrowing costs rise, some investors may reconsider those strategies, potentially increasing demand for the Yen.
This changing policy environment has become an important factor behind the Japanese currency’s recent strength.
Japanese Government Intervention Warnings Add Support to the Yen
Apart from monetary policy expectations, the Japanese Yen has also received support from concerns about possible government intervention in the foreign exchange market.
Japanese authorities have repeatedly expressed discomfort with rapid and one-sided depreciation of their national currency.
Prime Minister Sanae Takaichi, Finance Minister Satsuki Katayama, and senior currency diplomat Atsushi Mimura have all warned about excessive currency movements and emphasized the importance of maintaining orderly financial markets.
Their comments suggest that Japanese officials are closely monitoring developments and remain concerned about movements that could create economic instability.
A weaker Yen can benefit Japanese exporters by making their products more competitive overseas. However, excessive depreciation can also increase the cost of imported goods, including energy, food, and industrial materials.
Higher import costs can place additional pressure on households and businesses, particularly when domestic wages do not increase at the same pace.
For this reason, Japanese authorities often distinguish between gradual currency adjustments and sudden movements that may disrupt economic conditions.
Officials have also referred to coordination with US authorities regarding orderly currency markets.
Although verbal warnings do not necessarily mean that direct intervention will follow, they can influence investor behavior.
Market participants may become reluctant to sell the Yen aggressively when they believe authorities could take steps to address excessive weakness.
This caution can create additional demand for the Japanese currency and make it more difficult for other currencies, including the British Pound, to strengthen against it.
Diverging Central Bank Expectations Shape the GBP/JPY Outlook
The contrasting monetary policy outlooks in the United Kingdom and Japan remain central to the GBP/JPY story.
In Britain, mixed inflation data has reduced confidence in another Bank of England rate increase. In Japan, consumer inflation developments have reinforced expectations of additional tightening by the Bank of Japan.
This difference matters because currency movements are often influenced by the relative attractiveness of financial assets across countries.
When investors expect interest rates to rise in one economy while becoming less confident about further increases in another, capital flows and currency demand may change.
For GBP/JPY, the possibility of tighter Japanese monetary policy alongside a less aggressive Bank of England creates an environment that favors the Yen.
Nevertheless, future developments remain uncertain.
Upcoming UK economic reports could influence expectations for the BoE, while Japanese inflation, wage growth, and broader economic conditions will remain important for the BoJ’s decisions.
Statements from central bank officials and Japanese government representatives may also affect investor confidence.
Until there is greater clarity, the British Pound may struggle to establish a lasting recovery against the Japanese Yen.
Final Summary
The GBP/JPY currency pair remains under pressure despite stronger-than-expected UK Retail Sales data. Although the improvement in consumer spending briefly supported the British Pound, uncertainty surrounding the Bank of England’s next interest rate decision has limited the currency’s recovery.
Meanwhile, Japan’s inflation report has strengthened expectations of further monetary tightening by the Bank of Japan, providing an important source of support for the Japanese Yen.
Warnings from Japanese officials about excessive currency depreciation have added another layer of caution, discouraging aggressive selling of the Yen.
The combination of reduced confidence in additional UK interest rate increases, growing expectations of tighter Japanese monetary policy, and potential intervention risks continues to weigh on GBP/JPY.
Looking ahead, the direction of the currency pair will depend largely on how economic conditions develop and whether the two central banks maintain their contrasting policy outlooks.
Crude Oil Gains Fresh Momentum as Gulf Tensions Fuel Global Energy Uncertainty
The global oil market is facing a period of uncertainty as rising tensions in the Middle East create fresh concerns about energy supplies. Recent missile attacks, incidents involving oil tankers, and growing political tensions have raised questions about the safety of major shipping routes and the stability of regional oil production.
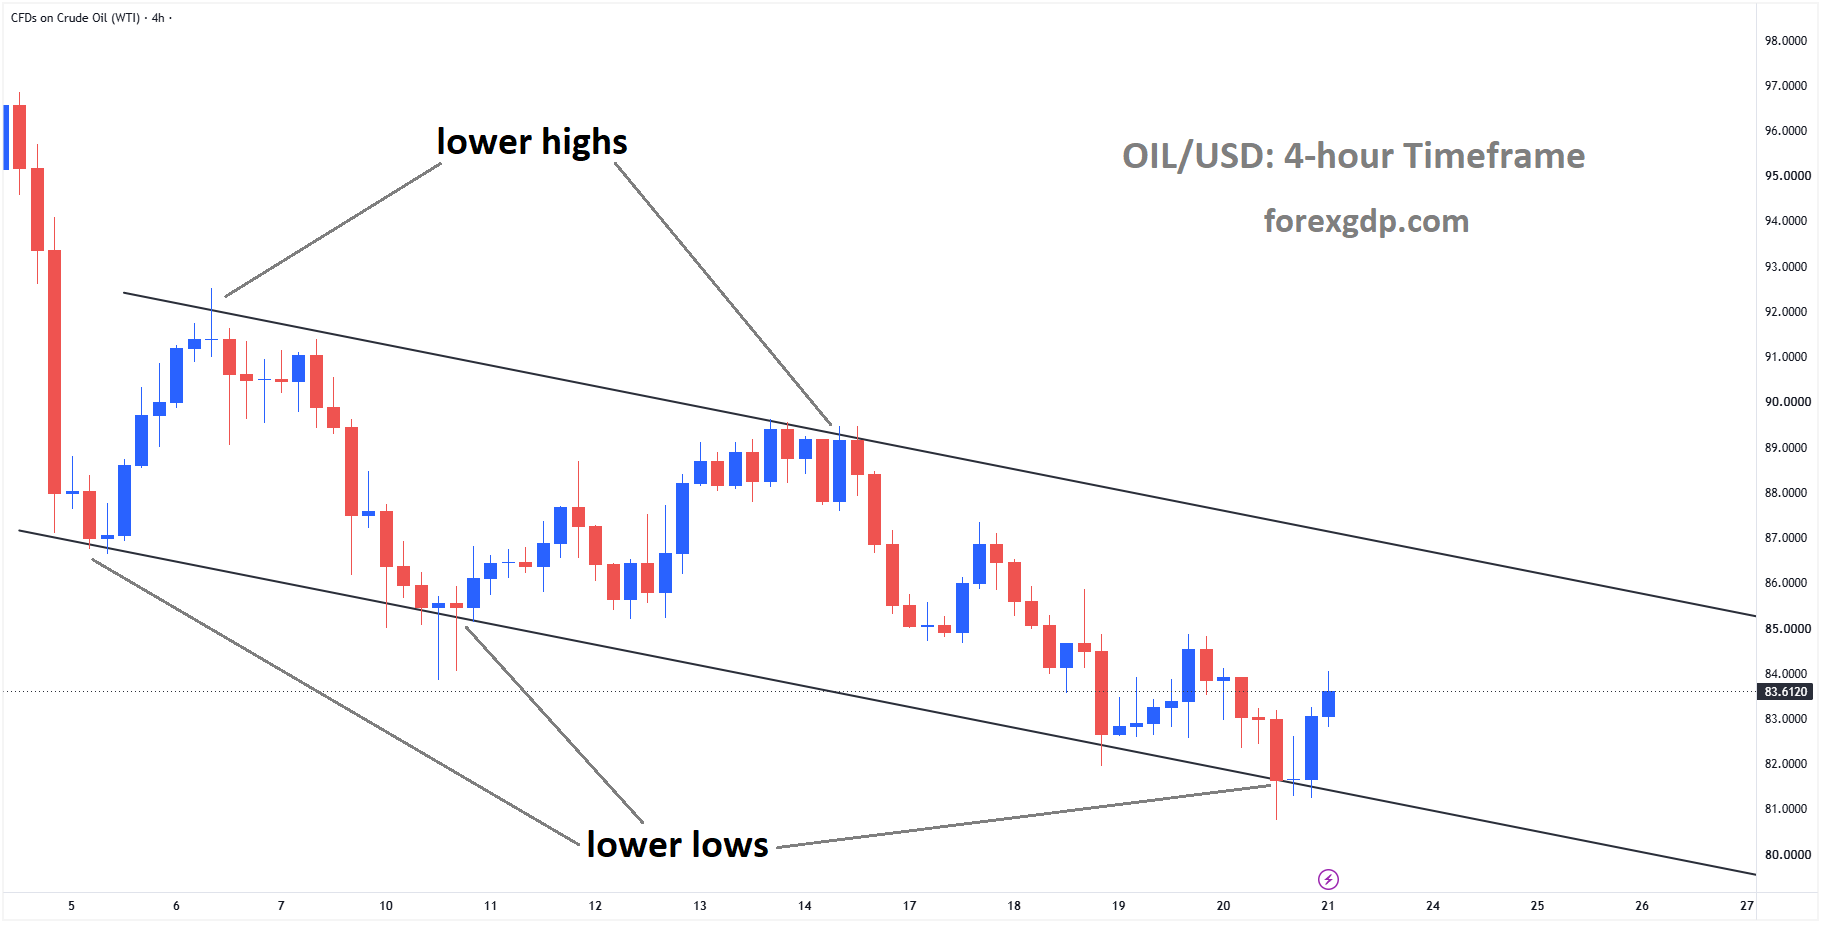
Crude Oil is rebounding from the lower low area of the descending channel
However, the broader global supply situation presents a different picture. Major energy-producing countries are working to increase petroleum supplies, while international energy organizations expect oil production to remain strong. This combination of geopolitical uncertainty and expanding global output has created a complicated environment for the energy industry.
Developments involving Saudi Arabia, Iran, the United States, China, and Russia are now attracting significant attention. At the same time, the International Energy Agency (IEA) expects global oil supplies to exceed demand during the current quarter, suggesting that the world could have enough petroleum to absorb some unexpected disruptions.
Houthi Missile Attacks Increase Middle East Security Concerns
Security concerns intensified on Thursday after the Iran-aligned Houthi movement launched missile attacks targeting Riyadh, the capital of Saudi Arabia.
The incident added another layer of uncertainty to an already tense regional situation. Saudi Arabia plays a central role in global energy production, making developments involving the country particularly important for international oil supplies.
Although the attacks targeted the Saudi capital, the wider concern involves the possibility of continued military activity affecting important energy infrastructure and transportation networks.
Saudi Arabia has extensive oil production facilities, processing centers, and export terminals that support energy deliveries to countries around the world. Any serious interruption to these operations could create difficulties for refiners, shipping companies, and businesses that depend on reliable petroleum supplies.
The latest incident also highlights the broader security challenges facing the Middle East. Regional conflicts can affect energy markets even when production facilities remain operational because companies may become more cautious about transportation, insurance, and shipping arrangements.
For global energy consumers, the main concern is whether these tensions will remain limited or develop into a wider confrontation.
Oil Tanker Incidents Raise Questions About Strait of Hormuz Safety
Another major development occurred in the Strait of Hormuz, where Iran’s navy reported that two oil tankers struck naval mines and experienced explosions on Thursday.
The reported incidents raised serious concerns about maritime security in one of the world’s most important energy transportation routes.
The Strait of Hormuz connects the Persian Gulf with the Gulf of Oman and provides a vital passage for petroleum shipments traveling from Middle Eastern producers to international destinations.
Countries across Asia and other regions depend heavily on energy supplies transported through this narrow waterway. As a result, even temporary shipping disruptions can create challenges for the global energy supply chain.
Why the Strait of Hormuz Matters to Global Oil Supplies
The Strait of Hormuz is particularly important because it handles large volumes of crude oil and petroleum products exported by major Gulf producers.
Its strategic location makes it difficult to replace with alternative shipping routes. Although some countries have pipelines that can transport oil around the strait, these alternatives cannot necessarily accommodate every shipment that would normally pass through the waterway.
Incidents involving naval mines also create additional safety concerns for commercial vessels. Shipping operators may need to review their routes, strengthen security procedures, or wait for further information before entering potentially dangerous areas.
Such precautions can affect delivery schedules and increase uncertainty for companies responsible for moving energy supplies between countries.
The latest tanker incidents demonstrate how maritime security can influence the energy industry even when oil production itself remains unaffected.
Record Oil Flows Offer Reassurance Despite Regional Tensions
Despite the security incidents, recent statements from US officials suggest that oil transportation through the Strait of Hormuz has remained strong.
US Energy Secretary Chris Wright indicated that petroleum flows through the strategic shipping route had reached record levels. He also pointed to recovering production across the Middle East.
These developments suggest that regional energy operations have continued to function despite growing political and military tensions.
Strong shipping activity is important because it allows oil-producing countries to maintain deliveries to international customers. It also helps refineries secure the raw materials needed to produce gasoline, diesel, aviation fuel, and other petroleum products.
The recovery in Middle Eastern production provides another source of reassurance. Higher output can help maintain adequate supplies and reduce the risk of shortages if isolated disruptions occur.
However, strong current shipments do not completely eliminate future risks. The situation could change if military activity intensifies or if shipping companies face additional threats along major transportation routes.
For this reason, energy companies and governments are likely to continue monitoring security developments closely.
United States, China, and Russia Agree to Increase Refined Petroleum Supplies
In another significant development, the United States, China, and Russia reportedly reached a trilateral agreement on Thursday to increase the production and supply of refined petroleum products.
The agreement brings together three major countries with substantial influence over global energy production, consumption, and trade.
Refined petroleum products are essential for transportation, manufacturing, agriculture, and many other economic activities. Maintaining sufficient supplies is therefore important for businesses and households worldwide.
The reported cooperation could help strengthen the availability of fuels during a period of geopolitical uncertainty.
How Higher Fuel Production Could Support Energy Security

Increasing refined petroleum production may provide several benefits for the global energy system.
Greater fuel availability can help countries manage unexpected changes in demand and reduce pressure on existing supply networks. It may also give import-dependent economies more flexibility when arranging deliveries from international suppliers.
Cooperation between major energy economies could support more stable distribution arrangements, particularly when transportation routes face security concerns.
However, the effectiveness of the reported agreement will depend on how participating countries implement their commitments.
Production capacity, refinery operations, export policies, and transportation infrastructure will all influence how additional supplies reach international consumers.
International Energy Agency Expects a Global Oil Supply Surplus
While geopolitical tensions continue to attract attention, the International Energy Agency expects global oil production to exceed consumption during the current quarter.
According to the agency’s projection, the global petroleum market could experience a supply surplus of approximately two million barrels per day.
This outlook suggests that production growth may be outpacing demand, creating a potential buffer against temporary supply interruptions.
An oil surplus generally means that more petroleum is available than the market currently requires. This additional supply can provide flexibility for importing countries and help reduce the immediate impact of unexpected disruptions.
Goldman Sachs has also warned about the possibility of excess global oil supplies extending into the following year.
Together, these assessments indicate that the energy industry may face a period of abundant production even as political uncertainty continues.
Nevertheless, supply projections depend on several factors, including economic activity, industrial demand, transportation needs, and decisions made by major oil-producing nations.
Unexpected geopolitical developments could also change the outlook, particularly if they affect production facilities or international shipping routes.
Trump’s Iran Decision Adds Another Layer of Uncertainty
Political developments in Washington are another important factor influencing the outlook for Middle Eastern energy security.
President Donald Trump has indicated that he is not rushing to make a decision regarding Iran, despite reports suggesting an increased possibility of further US military strikes.
His position leaves uncertainty surrounding the direction of American policy and the potential for additional regional confrontation.
Relations between Washington and Tehran have long influenced security conditions across the Persian Gulf. Any further escalation could affect shipping operations, diplomatic relations, and energy infrastructure.
At the same time, delaying a decision may allow additional opportunities for diplomatic discussions and assessments of the regional situation.
For the international energy industry, the central question is whether political tensions will lead to direct disruptions or remain contained.
Final Summary
The global oil industry is navigating two contrasting developments: rising security risks in the Middle East and growing petroleum supplies worldwide.
Houthi missile attacks targeting Riyadh and reported naval mine incidents involving tankers in the Strait of Hormuz have increased concerns about regional stability and maritime transportation.
Meanwhile, record oil flows, recovering Middle Eastern production, and reported cooperation between the United States, China, and Russia suggest that global energy supplies remain resilient.
The International Energy Agency’s projected supply surplus further indicates that the market may have additional capacity to withstand limited disruptions.
However, uncertainty surrounding US policy toward Iran remains an important concern. The coming period will depend heavily on whether regional tensions intensify, shipping routes remain accessible, and major producers continue maintaining reliable energy supplies.
Ultimately, the balance between geopolitical security and global production growth will play a major role in shaping the stability of the international oil industry.
BTCUSD Struggles for Momentum as Fed Concerns Mount
Bitcoin continues to face strong selling pressure as the cryptocurrency market struggles with falling investor confidence, declining institutional demand, and uncertainty surrounding US monetary policy. The world’s largest cryptocurrency is heading toward its seventh consecutive week of losses, highlighting the challenges facing digital assets during a period of growing financial uncertainty.
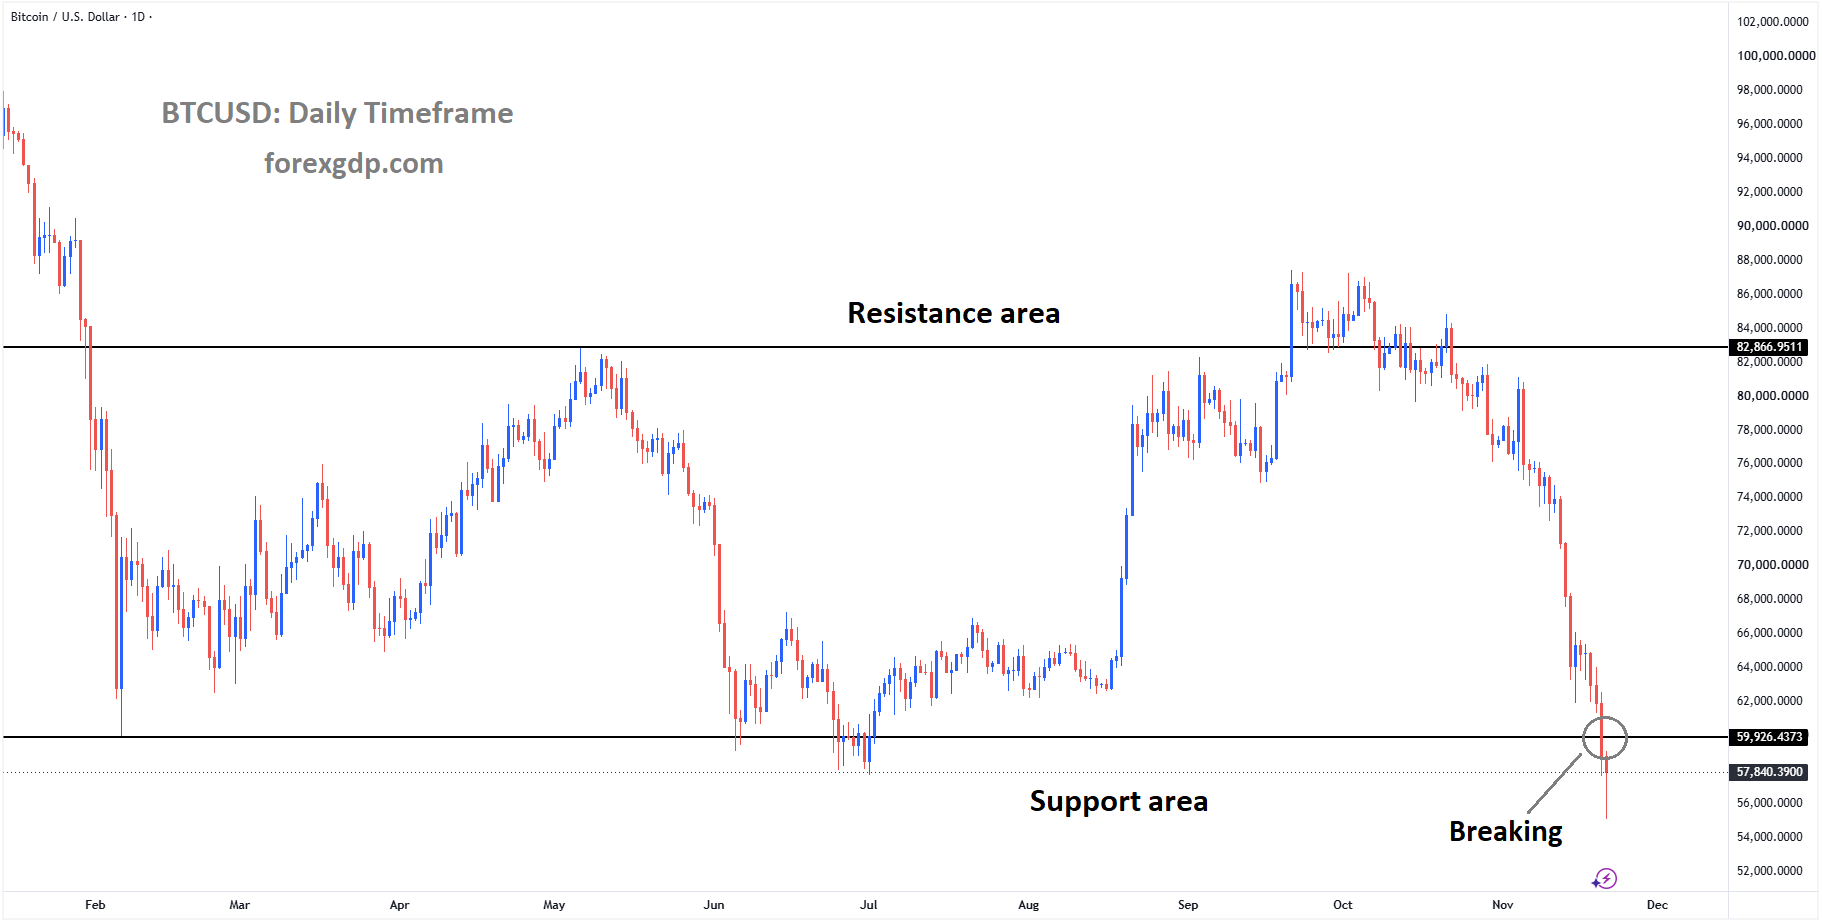
BTCUSD is breaking the support area of the box pattern
The ongoing decline has raised concerns about whether Bitcoin can regain investor confidence in the near future. Large withdrawals from US-listed spot Bitcoin exchange-traded funds (ETFs), increased liquidations, and cautious signals from the Federal Reserve have created a difficult environment for the cryptocurrency.
While Bitcoin remains an important part of the global digital asset market, recent developments suggest that both institutional and individual investors are becoming more careful about taking financial risks.
Bitcoin Selling Pressure Continues as Investor Confidence Weakens
Bitcoin’s extended losing streak reflects a broader change in market sentiment. Investors who previously showed strong interest in cryptocurrencies are now taking a more cautious approach as economic uncertainty increases.
Several factors have contributed to this shift, including concerns about inflation, expectations of tighter monetary policy, and reduced demand from major financial institutions.
Bitcoin is often viewed as an alternative investment that offers opportunities outside traditional financial markets. However, it remains sensitive to changes in global financial conditions, particularly when investors become less willing to hold risky assets.
During uncertain economic periods, many investors prefer to protect their capital rather than increase their exposure to volatile investments. This behavior can affect cryptocurrencies because their demand often depends on confidence in future economic growth and financial stability.
The latest weakness also shows how closely Bitcoin has become connected to traditional financial markets. Decisions made by central banks, institutional investment firms, and large asset managers can influence sentiment across the cryptocurrency industry.
Spot Bitcoin ETF Outflows Highlight Declining Institutional Demand
One of the biggest concerns for Bitcoin investors is the continued withdrawal of money from US-listed spot Bitcoin ETFs.
These investment products allow investors to gain exposure to Bitcoin through traditional financial markets without directly purchasing or storing the cryptocurrency.
Spot Bitcoin ETFs have become an important connection between digital assets and institutional finance. Their investment flows provide useful information about how professional investors and major financial institutions view Bitcoin.
Recent data from SoSoValue indicates that these funds are heading toward another consecutive week of net withdrawals. The continued movement of capital away from Bitcoin investment products suggests that institutional demand has weakened considerably.
Why ETF Withdrawals Matter for Bitcoin
When investors put money into spot Bitcoin ETFs, the funds generally acquire Bitcoin to support their investment products. This process can contribute to demand for the cryptocurrency.
However, when investors withdraw money, ETF providers may need to reduce their Bitcoin holdings. Sustained withdrawals can therefore contribute to selling pressure across the broader market.
The importance of these funds has grown as institutional participation in cryptocurrency investing has increased.
Large investment firms, wealth managers, and other professional investors often use regulated financial products to access digital assets. Changes in their investment decisions can influence market confidence.
Continued ETF withdrawals may also discourage smaller investors who monitor institutional activity when making their own financial decisions.
Although ETF outflows do not necessarily indicate a permanent loss of interest in Bitcoin, they suggest that some investors are currently prioritizing financial security over potential investment opportunities.
Institutional Bitcoin Investors Face Growing Unrealized Losses
Another challenge affecting market confidence is the growing number of institutional investors holding Bitcoin investments at a loss.
An unrealized loss occurs when an investment loses value compared with its original purchase cost but has not yet been sold.
These losses can influence investor behavior, especially when market uncertainty continues for an extended period.
Some investors may choose to hold their positions and wait for conditions to improve. Others may decide to reduce their exposure to prevent additional financial losses.
This difference in investor behavior can create uncertainty about future institutional demand.
How Unrealized Losses Affect Market Sentiment
Investors generally become more cautious when their holdings remain under pressure for a prolonged period.
For institutional investors, decisions about maintaining cryptocurrency exposure often involve portfolio management rules, risk limits, and broader financial objectives.
Investment managers may reassess their Bitcoin holdings when market conditions change or when clients become less comfortable with digital asset exposure.
If many investors decide to reduce their holdings around the same period, selling activity can increase.
However, unrealized losses do not automatically lead to withdrawals. Long-term investors may continue holding Bitcoin if they believe its broader investment potential remains attractive.
The key issue is whether confidence can recover enough to encourage renewed institutional participation.
Federal Reserve Policy Adds Pressure to Cryptocurrency Markets
US monetary policy is another major factor influencing Bitcoin’s recent weakness.
Minutes from the Federal Reserve’s October Federal Open Market Committee (FOMC) meeting revealed a cautious approach toward inflation and future interest rate decisions.
The discussions suggested that policymakers remained concerned about inflation risks and were prepared to maintain restrictive financial conditions if necessary.
Some officials also indicated that additional monetary tightening could become appropriate if economic data showed persistent inflation.
These signals have increased uncertainty about how quickly financial conditions might become more supportive of riskier investments.
Why Higher Interest Rates Can Hurt Bitcoin Demand
Interest rates influence investment decisions across global financial markets.
When borrowing costs remain elevated, businesses and consumers often become more careful about spending and investment.
Higher interest rates can also make traditional financial assets more attractive, particularly investments that offer relatively predictable returns.
As a result, some investors may move money away from cryptocurrencies and other volatile assets.
Bitcoin does not provide guaranteed income or interest payments simply through ownership. Its investment appeal depends partly on expectations about future demand, adoption, and long-term value.
When safer financial alternatives become more appealing, cryptocurrency demand may weaken.
A restrictive Federal Reserve policy can also support the US dollar, creating additional challenges for assets that are sensitive to global liquidity and investor risk appetite.
Rising Liquidations Increase Stress Across the Crypto Market
Alongside institutional withdrawals and monetary policy concerns, leveraged liquidations have contributed to Bitcoin’s difficult market environment.
Leverage allows traders to take larger positions by using borrowed funds. Although this can increase potential returns, it also raises the risk of substantial losses.
When the market moves against leveraged traders, their positions may be automatically closed if they cannot maintain the required collateral.
This process is known as liquidation.
During periods of heightened volatility, multiple liquidations can occur within a short period, adding to market instability.
Forced selling may place additional pressure on Bitcoin and affect confidence across other cryptocurrencies.
The impact can extend beyond individual traders because rapid liquidation activity sometimes causes investors to become more cautious about participating in the market.
For this reason, excessive leverage remains an important risk factor within the cryptocurrency ecosystem.
Concerns About AI Financing Add to Broader Financial Uncertainty
The Federal Reserve’s meeting discussions also highlighted concerns about financing activity connected to artificial intelligence.
Policymakers observed that debt associated with AI-related investments had expanded rapidly, with some financing arrangements becoming increasingly complex and difficult to assess.
Officials also expressed concern about financial exposure becoming concentrated among a relatively small group of companies.
These observations matter because artificial intelligence has become an important driver of investment activity across several industries.
If investors begin questioning the sustainability of AI-related borrowing or the financial strength of heavily exposed companies, broader market confidence could weaken.
Although these concerns are not directly related to Bitcoin, they contribute to the overall economic environment in which cryptocurrencies operate.
Financial uncertainty in one major investment sector can influence attitudes toward risk in other markets.
As a result, concerns about technology financing, inflation, and monetary policy may collectively encourage investors to maintain a defensive approach.
What Could Help Bitcoin Regain Investor Confidence?
A sustained improvement in Bitcoin sentiment will likely depend on several developments across institutional markets and the broader economy.
Renewed interest in spot Bitcoin ETFs could provide evidence that major investors are becoming more comfortable with cryptocurrency exposure.
Greater clarity from the Federal Reserve could also help reduce uncertainty about future financial conditions.
If inflation concerns ease and policymakers adopt a less restrictive approach, investors may become more willing to consider riskier assets.
A reduction in excessive leverage could further support a healthier cryptocurrency market by limiting the impact of forced liquidations.
However, none of these developments guarantees a recovery. Bitcoin remains exposed to economic uncertainty, changing investor expectations, and risks specific to the digital asset industry.
Summary
Bitcoin’s extended losing streak reflects a combination of weakening institutional demand, persistent ETF withdrawals, leveraged liquidations, and concerns about US monetary policy.
The Federal Reserve’s cautious stance on inflation has encouraged investors to reconsider their exposure to volatile assets, while unrealized losses among institutional Bitcoin holders have added to market uncertainty.
Concerns surrounding AI-related financing have also contributed to a more defensive investment environment.
Despite these challenges, Bitcoin remains a major part of the global cryptocurrency market. Its ability to regain momentum will depend largely on improving investor confidence, stronger institutional participation, and greater clarity about the economic outlook.
For now, the broader market environment suggests that caution is likely to remain an important theme in Bitcoin investing.
Don’t trade all the time, trade forex only at the confirmed trade setups
Get more confirmed trade signals at premium or supreme – Click here to get more signals, 2200%, 800% growth in Real Live USD trading account of our users – click here to see , or If you want to get FREE Trial signals, You can Join FREE Signals Now!